
Unfortunately, there are no properties on your watch list.
Do you have a question? Leave your contact details here and we will call you back!

Press Release
Top markets: REALOGIS analyses the market for logistics and industrial properties in the first half of 2024
- Take-up in new lettings and owner-occupation increases by +17.2%
- Tenants dominate the market, owner-occupiers continue to play a minor role
Munich, 31 July 2024 - In the first half of 2024, a total of around 1.13 million m² of space in logistics and industrial properties for rent or owner-occupation was newly taken up by all market participants in the top 8 locations in Germany. This is the result of the latest analysis by Realogis - Germany's leading consultancy for industrial and logistics properties and commercial properties.
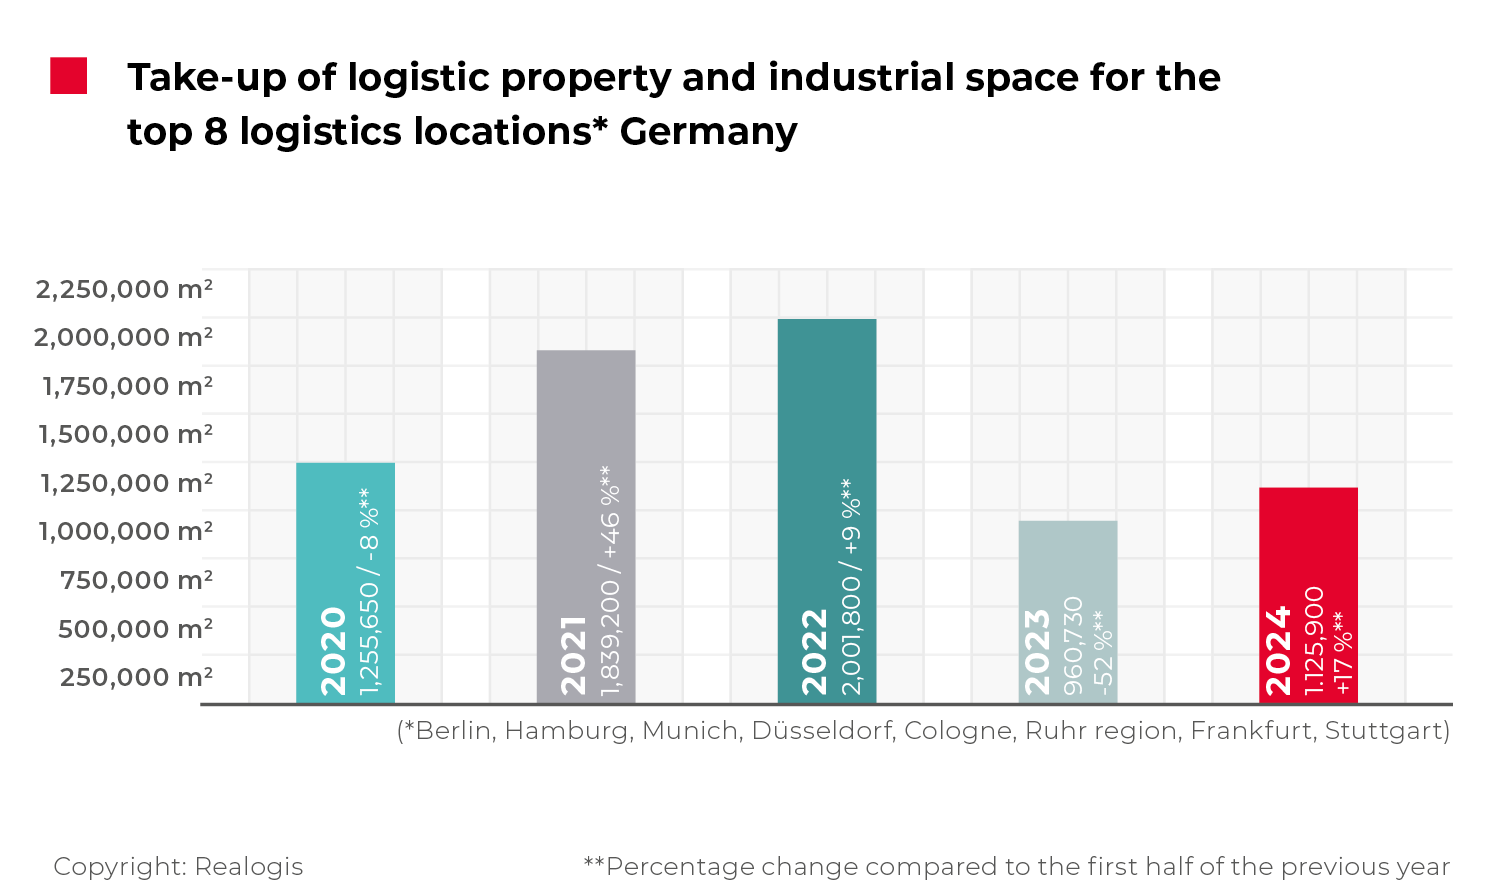
The result corresponds to an increase of 17.2% or 165,170 m² compared to the extremely weak prior-year period. The first half of 2023 was recorded with a delta of around one million (to 960,730 m²) in take-up, compared to 2 million m² in the first half of 2022.
The eight most important German markets include the metropolitan regions of Hamburg, Frankfurt, Berlin, Munich, Cologne, Düsseldorf and Stuttgart as well as the Ruhr region.
"We have bottomed out and the race to catch up in the markets has begun. After the start of 2023, the weakest first half of the year since our records began in 2014, take-up in the first six months of 2024 represents a trend reversal compared to the same period of the previous year. However, it should still be noted that this is the second weakest first half of our records since 2014," comments Bülent Alemdag, Managing Director of Realogis Immobilien Düsseldorf GmbH.
This is also reflected in the fact that the 5-year average for the first half of the year has currently been missed by around 22%, albeit less significantly than in the same period last year. The average for H1 2024 is 1.44 million m² (H1 2023: 1.48 million m², -35%).
Cologne and Munich are currently the only markets that are at or above the respective 5-year average for the first half of the year. Cologne exceeds this by 37%, while Munich is almost on a par. Berlin is the most clearly below the average with -54%, followed by Hamburg with -36%, Stuttgart with -32%, the Ruhr region with -26%, Düsseldorf with -11% and Frankfurt with -6%.
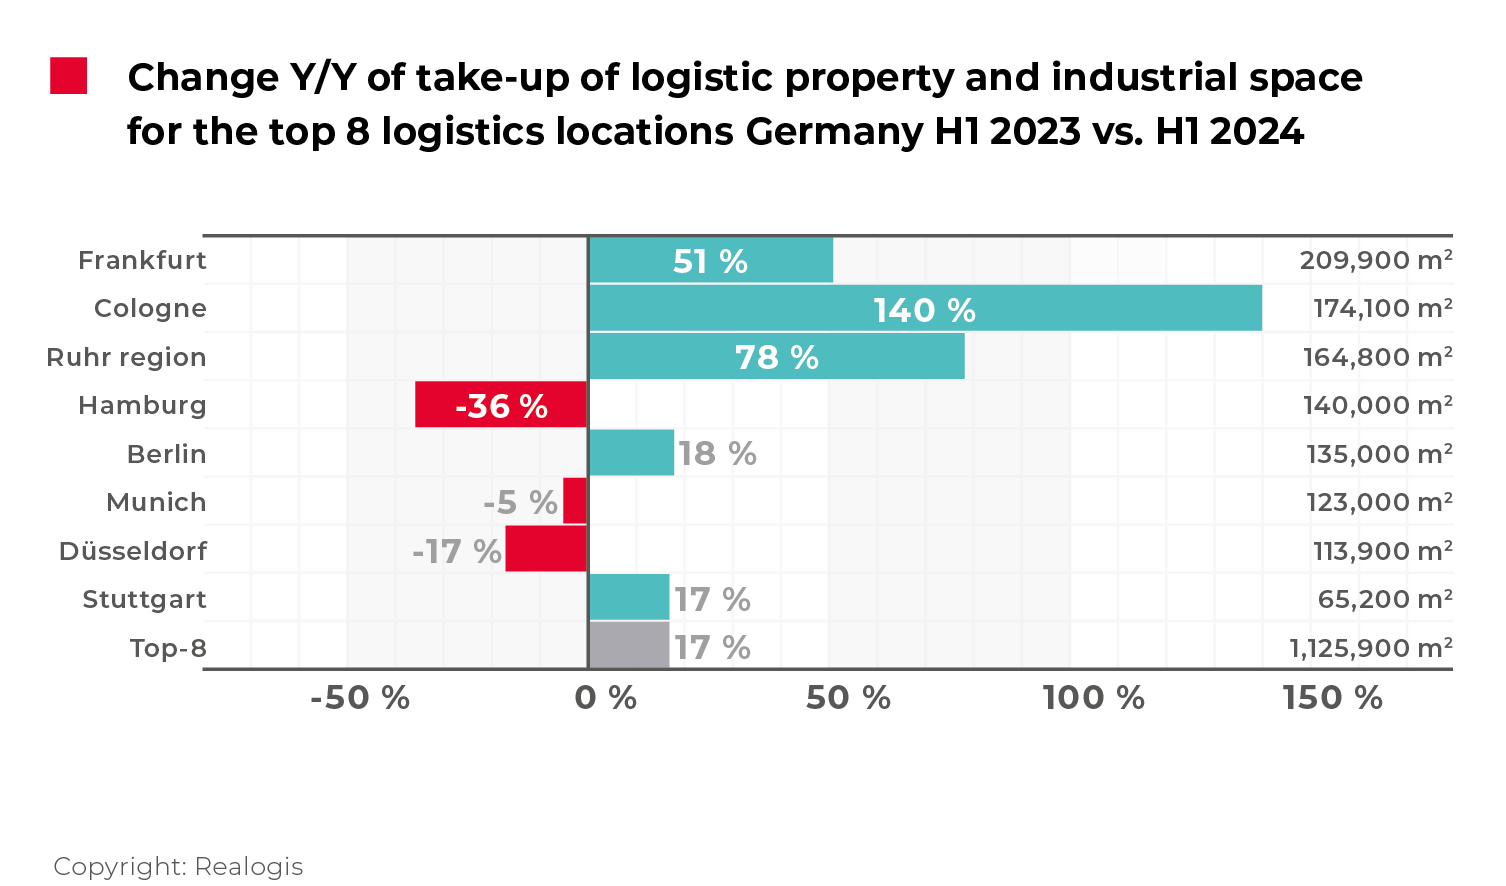
The year-on-year change is more positive: Here, Cologne in particular has made significant gains (+140% to a current 174,100 m²), followed by the Ruhr region with +78% (to 164,800 m²) and Frankfurt (+51% to 209,900 m²). Berlin (+18 % to 135,000 m²) and Stuttgart (+17 % to 65,200 m²) recorded moderate growth, while Düsseldorf ( -17 % to 113,900 m²) fell moderately. Munich is slightly below the previous year's level (-5% to 123,000 m²). Hamburg is the only city to fall more sharply, with a -36% drop to 140,000 m².
Tenants dominate the market, owner-occupiers continue to play a lesser role
"At 95.2% or around 1 million m², the majority of the decrease in space in the top 8 markets is attributable to tenants. Only 5.6% or 53,700 m² of total take-up in the first six months was attributable to owner-occupiers. This is still clear, but in the previous year we observed that owner-occupiers were even less important," reports Julian Petri, Managing Director of Realogis Immobilien Frankfurt GmbH.
In the previous year, the ratio was even clearer, with 97.8% or 939,630 m² on the tenant side and 2.2% or 21,100 m² on the owner-occupier side. In contrast, 24 months ago, around a quarter of the total take-up of all top markets in H1 2022 was attributable to owner-occupiers (or 527,700 m²) and 73.3% was accounted for by tenants with 1.47 million m².
Big boxes in first place, business parks lose significant take-up
In termsof building type, big box space took the lead with take-up of 489,700 m² or a 43.5 % share, moving up one place compared to the previous year (H1 2023: 332,300 m² or 34.6 %). Among all building types, they also recorded the most significant increase with around 157,000 m² or 47.3 %.
In second place was the previously third-placed category of other properties with 351,460 m² or 31.2 %, which corresponds to an increase of 90,227 m² or 34.5 % from 261,233 m².
Only business parks fell significantly year-on-year. Their take-up fell by -82,391 m² or -22.4 % to a current 284,740 m². Coming from second place with 367,131 m² or 38.2 %, they suffered the most significant loss of importance (-12.9 percentage points of the proportionate total take-up).
Sector ranking: logistics/distribution in first place, but with significant restraint
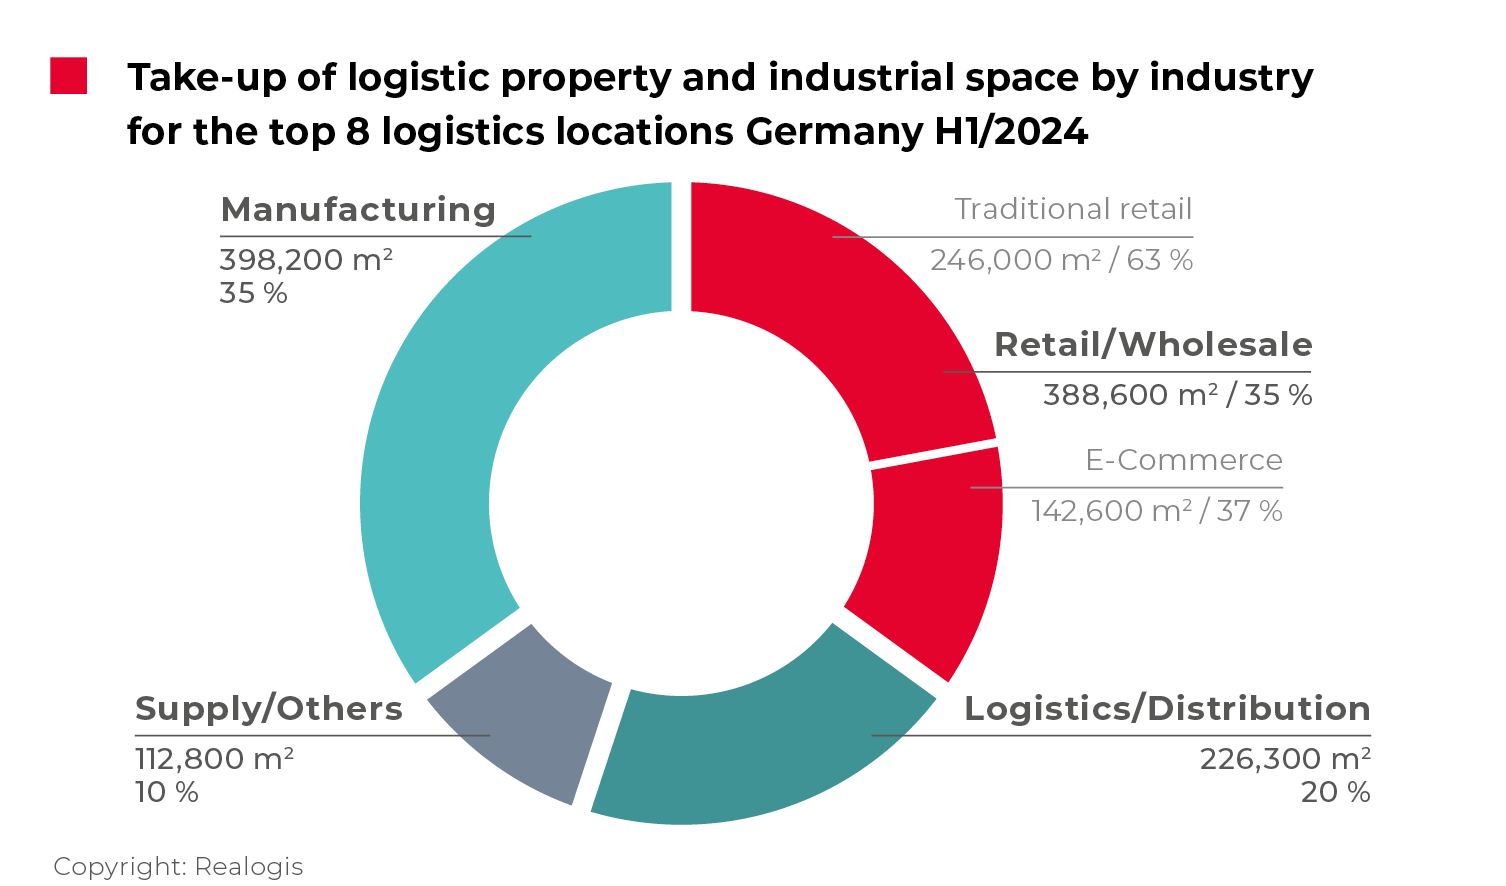
The leading sector in terms of take-up of the top 8 in the past six months is again logistics/distribution with 398,200 m² or 35.4 %, coming from 317,485 m² or 33 %. At 80,715 m² or 25.4 %, this corresponds to the second clearest increase of all sectors.
"Nevertheless, the 5-year average of 538,040 m² illustrates the reluctance of logistics companies and freight forwarders, which, with a drop of 26%, are the most below their own average of the last five first half-years of all sectors," says Jörg Lojewski, Managing Director of Realogis Immobilien Hamburg GmbH.
Retail is only just behind in second place with 388,600 m² or 34.5 %. Coming in at 261,860 m² or 27.3 %, the retail sector recorded the most significant year-on-year growth of all sectors in the first half of 2024 (+126,740 m² or +48.4 %). Despite the significant growth, the 5-year average of 486,871 m² was undercut by a substantial 20.2 %.
While the decrease in space was almost equally distributed between traditional retail and e-commerce in the previous year, there is currently a shift in favour of traditional retail. The sub-category accounted for 246,000 m² and thus almost two out of every three square metres taken up by the overall retail category (63.3%). Coming from 134,450 m², this represents an increase of 111,550 m² or 83%. This is followed by e-commerce with 142,600 m² or 36.7 %, up from 127,410 m² or 48.7 % (+ 15,190 m²).
Manufacturing remains in third place with 226,300 m² or 20.1 %, up from 258,470 m² or 26.9 %. This sector thus recorded the most significant year-on-year decline of all, with 32,170 m² or 12.4 %. At the same time, it is the second most significantly below the 5-year average (297,518 m²) of all sectors after retail at 23.9%.
In last place is the miscellaneous category with 112,800 m² or 10 %, down from 122,915 m² or 12.8 %. At 10,115 m² or 8.2 %, it suffered a more moderate loss in take-up and is the closest of all sectors to the 5-year average of 113,249 m², undercutting it by less than 1 %.
"The below-average half-year result can be attributed to the logistics/distribution, manufacturing and retail sectors, as they are all below their respective 5-year averages to a similar extent," says Stefan Imken, Managing Director of Realogis Immobilien Hamburg GmbH.
This can be seen most clearly in the logistics/distribution sector (-26 %), followed by manufacturing (-23.9 %) and retail (-20 %).
Large spaces with 36% growth
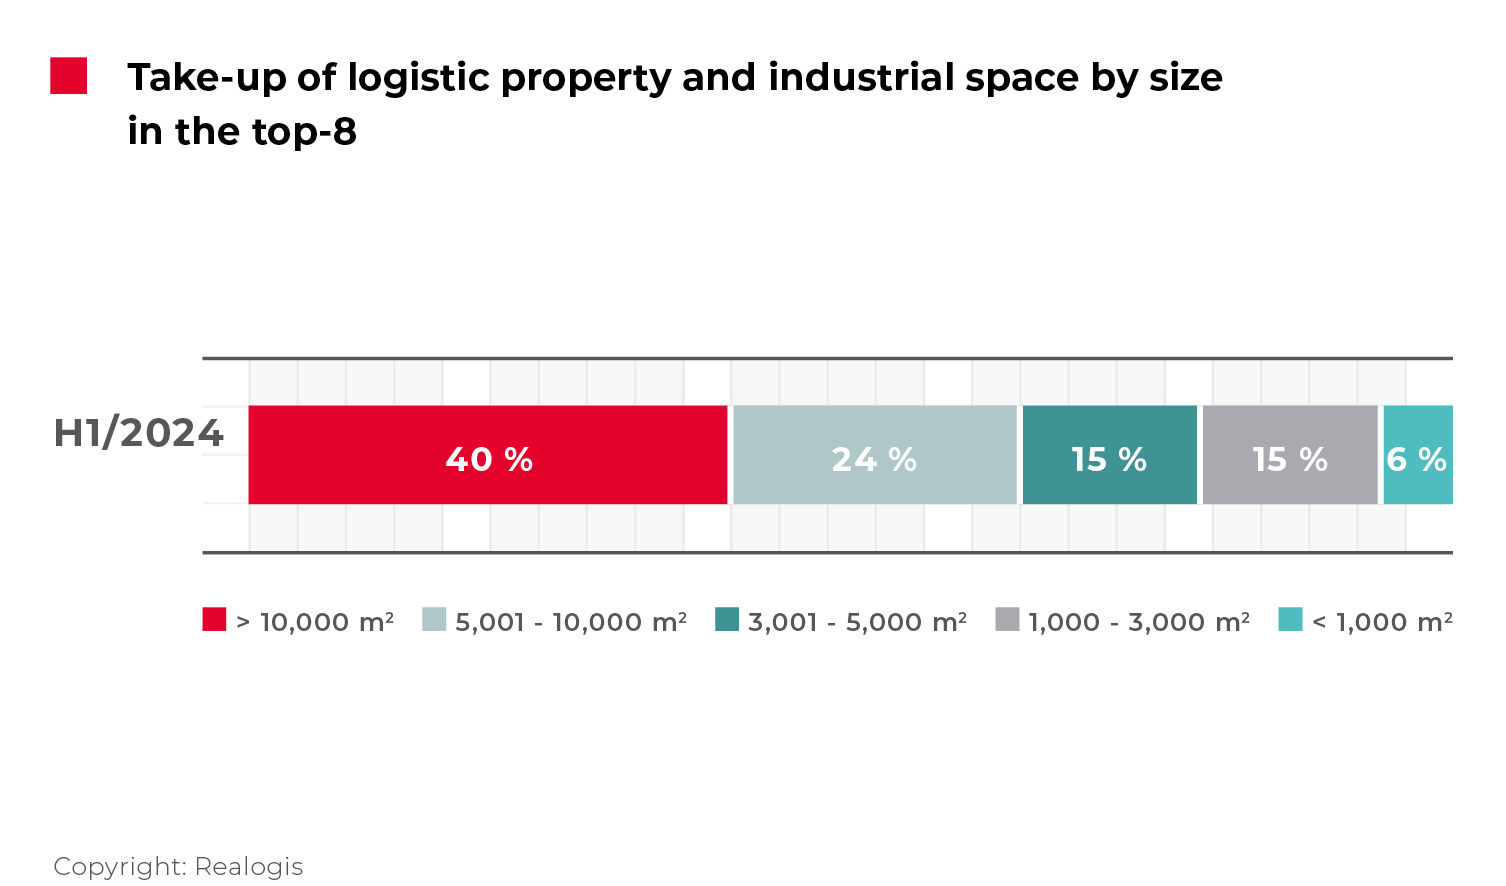
"An analysis of the size categories in all top 8 markets shows that space of 5,001 m² or more is responsible for two thirds or 64.4 % of total take-up. The ranking of the space segments remains unchanged from the previous year," reports Joel Adam, Managing Director of Realogis Immobilien Stuttgart GmbH.
Large spaces of 10,001 m² or more account for a total of 452,200 m² or 40.2 %. Coming from 332,527 m² or 34.6 %, this is a significant increase of 119,673 m² or 36 %.
Units between 5,001 and 10,000 m² are responsible for the second highest take-up with 273,085 m² or 24.3 %, coming from 234,516 m² or 24.4 %, which corresponds to the second highest increase of 38,569 m² or 16.4 %.
Space between 3,001 and 5,000 m² contributed 163,050 m² or 14.5 % and thus the fourth most space (up 36,755 m² from 126,295 m² or 13.1 %). Smaller spaces between 1,000 and 3,000 m² are currently still in third place, although they are the only size category to record a decline in take-up of 38,197 m² (-18.8 %). Very small spaces of less than 1,000 m² are in last place with 72,200 m² or 6.4 %, which corresponds to an increase of 8,370 m² or 13.1 %, coming from 63,346 m² or 7 %.
Prime rents in top 8 markets remain dynamic
"We have observed consistently rising prime rents for logistics properties in all of the top 8 markets for industrial and logistics properties," says Nicolas Werner, Managing Director of Realogis Immobilien München GmbH.
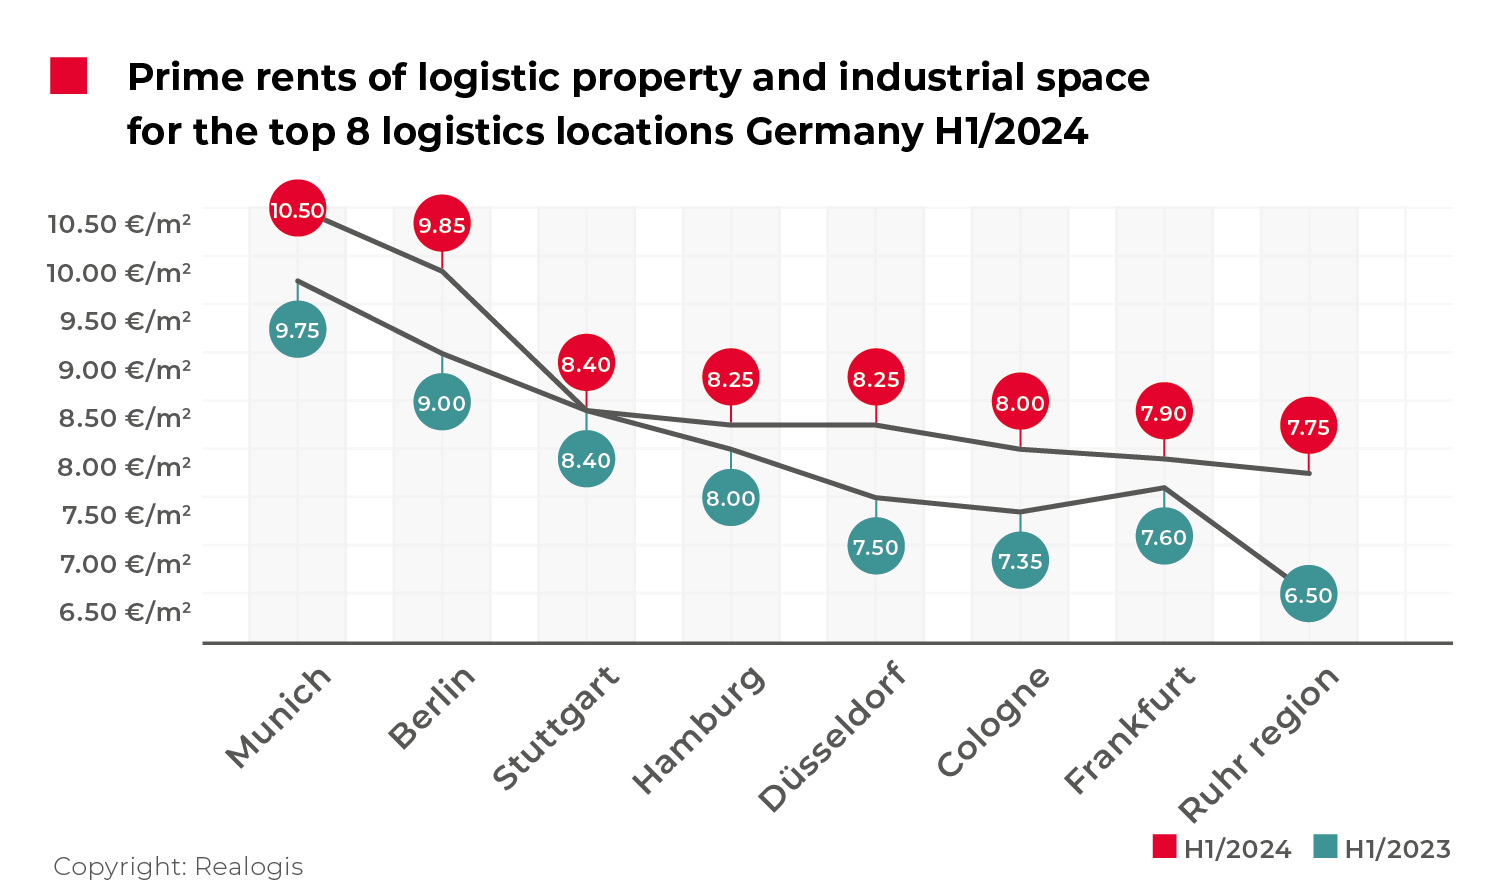
Munich continues to rank first in terms of prime rents with a new high of €10.50/m² (H1 2023: €9.75/m², +7.7%). Berlin also remains in the same position: at €9.85/m², the market ranks second out of the top 8 (H1 2023: €9.00/m², +9.4%). Stuttgart remains in third place at €8.40/m², followed by Hamburg and Düsseldorf, which are on a par at €8.25/m² (H1 2023: €8.00/m² or +3.1% and €7.50/m² or +10%).
Cologne follows in sixth place with €8.00/m² (H1 2023: €7.35/m², +8.8 %). The most favourable markets in terms of prime rents are Frankfurt and the Ruhr region: Frankfurt at €7.90/m² (H1 2023: €7.60/m², +3.9%) and the Ruhr region at €7.75/m² (H1 2023: €6.50/m², +19.2%).
Rent increases in the Ruhr region and Düsseldorf are in the double-digit range, while the rate of increase is in single figures in the other six markets. Only in Stuttgart are rents stagnating.
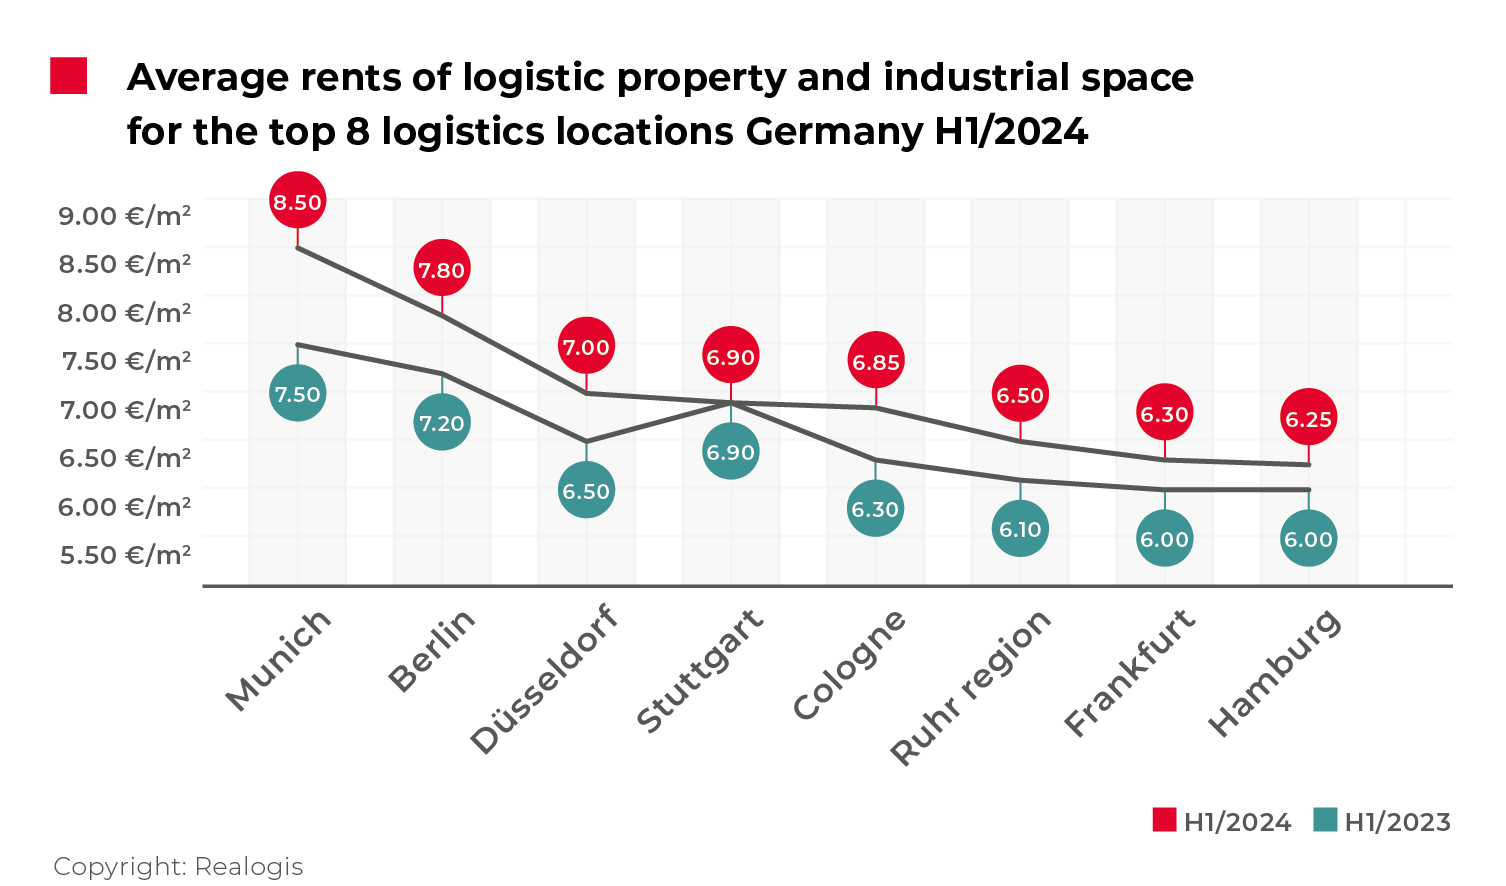
In terms of average rents, Munich is also the most expensive market at €8.50/m² (up from €7.50/m², +13.3%), followed by Berlin at €7.80/m² (H1 2023: €7.20/m², +8.3%). Düsseldorf follows in third place with €7.00/m², up from €6.50/m², which corresponds to an increase of 7.7% (up one place).
Stuttgart moves down one place to fourth place at €6.90/m² (sideways movement). Cologne remains in fifth place at €6.85/m² (H1 2023: €6.30/m², +8.7%), while the Ruhr region remains in sixth place at €6.50/m² (H1 2023: €6.10/m², +6.6%). The second lowest average rent in the top locations is Frankfurt at €6.30/m², ahead of Hamburg with an average rent of €6.25/m², coming in second to last at €6.00/m² (+4.2%).
REALOGIS press contact:
SH/Communication - Agency for Public Relations
Silke Westermann
Tel: +49/211/53 88 3-440
E-Mail: s.westermann@shcommunication.de
Company contact REALOGIS:
REALOGIS Holding GmbH
Silja Schuppler
Marketing
Leopoldstraße 154, 80804 München
Tel: +49/89/51 55 69 17
E-Mail: s.schuppler@realogis.de
www.realogis.de
REALOGIS. No. 1 for industrial and logistics properties
The REALOGIS Group is Germany’s leading player for the consulting and brokering of industrial, logistics and commercial properties. Founded in 2005 as a pioneer for the asset class of logistics and industry, the owner-operated group has enjoyed healthy growth, is crisis-resistant and knows the German market like no other. In 2022 Realogis generated nearly 1.25 million m² of usable space alone in the letting segment. The net commission revenue of all services in the financial year 2023 are around EUR 19 million.
In 2021, REALOGIS also won the German Real Estate Prize in the “Commercial Player” category, which honours companies for their outstanding commitment, creativity, innovative strength and sustainability.
Realogis is represented in the country’s seven top logistics locations of Berlin, Düsseldorf, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart, while a dedicated organisational unit ensures transparency in around 15 additional regional logistics markets. 70 real estate professionals advise national and international companies from the fields of logistics, e-commerce, retail and industry as well as private and institutional investors. Quick, flexible, regional, customer-oriented and with a high volume of transactions.
REALOGIS four core competencies are arranging highly creditworthy tenants for new and existing properties, assisting investors with property investments and project development of greenfields and brownfields, outstanding service for locating or selling sites, and the development and implementation of holistic property strategies.
In short, REALOGIS creates more room for its customers’ success in every sense. Further information: https://www.realogis.de/