
Unfortunately, there are no properties on your watch list.
Do you have a question? Leave your contact details here and we will call you back!

Press Release
Ruhr region: REALOGIS analyses the market for logistics and industrial properties in the first half of 2024
- Take-up increases after four half-year declines
- Brownfield completions compensate for total loss of new buildings on greenfield sites
- Sector ranking: Logistics/distribution takes up half of the space
- Big box spaces responsible for three quarters of space turnover
- Ranking of size categories: Large spaces with +168 %
- Prime rent increases by 19.2 % to 7.75 euros
- Outlook: New buildings will not be completed until 2025 and 2026
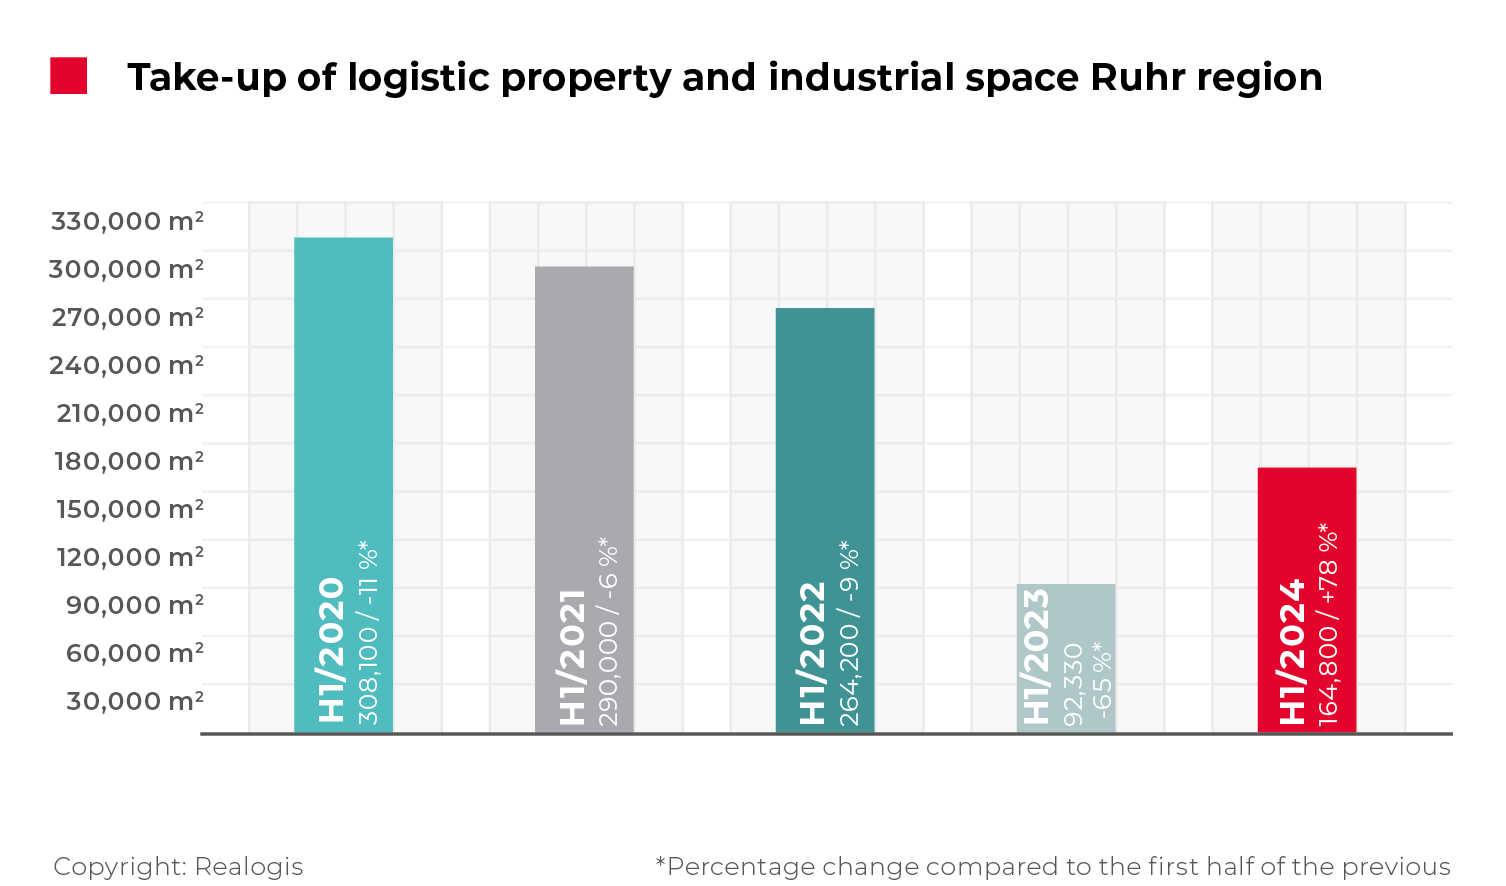
"After four consecutive declines in the first half of the year, we have registered an increase in take-up in the Ruhr region for the first time again," comments Bülent Alemdag, Managing Director of Realogis Immobilien Düsseldorf GmbH, which has been looking after all three top NRW markets of the Ruhr region, Düsseldorf and Cologne since 2007.
The half-year result for 2024 represents the most significant growth recorded by Realogis since the same period in 2019 (H1 2019: +162,177 m² or +87.7 %). Nevertheless, the first half of the year is well below average: the 5-year average of 223,886 m² has currently been missed by 26%.
Existing lettings are clearly in the lead with 107,700 m² or 65.4 %. This corresponds to an increase of 63,970 m² or more than double (+146%) compared to the first half of 2023 (43,730 m² or 47.4 %). Contracts for new builds on former brownfield sites, i.e. new build developments on former brownfield sites, accounted for take-up of 57,100 m² or 34.6 %. No transactions were recorded in this category in the same period of the previous year.
In contrast to previous years, completions in new builds on greenfield sites did not play a role in the first six months of 2024 (H1 2023: 48,600 m² or 52.6 %).
"The brownfield completions alone compensate for the total loss of new-build space. Added to this is the growth in existing space, resulting in a year-on-year increase of 72,470 m² in total," says Bülent Alemdag.
The Ruhr region is also a pure tenant market in the past six months; as in the first half of 2023 and 2022, no owner-occupier agreements were concluded.
In terms of building type, transactions in big-box properties continue to dominate the market. With a share of 75%, this category accounts for three out of every four square metres taken up, or 123,600 m² (H1 2023: 64,715 m²), almost doubling with an increase of 91%.
The other properties category (no properties in Bix Boxes or business parks) also made significant gains and is in second place. With a gain of 16,766 m², they doubled their take-up to 31,900 m² (H1 2023: 15,134 m²).
Transactions in business parks continue to play a subordinate role with 9,300 m² or 5.6 %: Compared to the same period last year, this is a decrease of 3,181 m² or -25.5 %.
Sector ranking: Logistics/distribution takes up half of the space
The leading sector in terms of take-up is currently logistics/distribution with 77,000 m² or 46.7 %. This represents a significant increase on the previous year (25,290 m² or 27.4 %, 3rd place). While in the previous year only just over one in four square metres was attributable to the decrease in logistics/distribution space, this figure is now almost one in two.
The most significant absolute increase of 51,710 m² represents more than a tripling (+204.5 %). Nevertheless, the long-term average of the last five first half-years cannot be reached. This is 117,358 m² and was missed by a clear 34.4 %.
Three of the top five deals were in the logistics/distribution sector and accounted for a total of 59,770 m² or 77.6 % of take-up. A large part of the half-year result is therefore attributable to a small number of large deals.
Key take-up contributors H1 2024
Company | Take-up | Type | Sector |
Euziel | 38,300 m² | New building | Retail |
EDA Cloud | 30,080 m² | New building | Logistics |
Euziel | 25,600 m² | Existing building | Retail |
TST | 15,000 m² | Existing building | Logistics |
Heinrich Dehn | 14,690 m² | Existing building | Logistics |
At 63,900 m² or 38.8 %, the retail sector once again took second place. Although it performs better in a direct comparison of the first six months, it is still not at the typical level for the Ruhr region. The growth of 35,460 m² or +124.7 % (H1 2023: 28,440 m² or 30.8 %) is not enough to reach the 5-year average of 82,248 m². The mark was missed by a clear 22.3 %. The two contracts signed by the e-commerce company Euziel, totalling 63,900 m², are the market leaders.
E-commerce is responsible for 63,900 m² of take-up in the retail category, exceeding its 5-year average by a significant 42.7 % (44,780 m²). In contrast, not a single take-up by companies in the traditional retail sector was recorded in the first six months of the current year. In the same period of the previous year, only 4,000 m² were taken up, corresponding to a share of 14.1 %. The average of the last five first six months shows that traditional retail plays a subordinate role for the market in the Ruhr region, as it currently stands at 6,833 m² - even lower than the average for the miscellaneous category, which currently stands at 8,800 m².
The manufacturing sector follows in third place with 14,900 m² or 9 %. Coming from first place with 32,600 m² or 35.3 %, manufacturing is the only sector with a decline in take-up (totalling 17,700 m² or 54.3 %). Despite the significant decline, the 5-year average was only missed by 3.7 % (15,480 m²).
The miscellaneous category “others/supply” continues to bring up the rear with 9,000 m² or 5.5 %. Compared to the previous year, this is an increase of 3,000 m².
"The additional decrease in space due to the logistics/distribution and retail sectors contributed significantly to the strong half-year result and more than compensated for the delta in the manufacturing sector. In both cases, it is a few outstanding large deals that make the difference," explains Bülent Alemdag.
Ranking of the size categories: Large spaces with +168 %
Large spaces of 10,001 m² or more are the clear winners in the size category ranking. At 123,700 m², they were responsible for three out of four square metres taken up in the past six months, up from 46,000 m² or 49.8 %, which equates to every second square metre. It is the only one of all size categories that was able to increase its proportionate importance: +25 percentage points in total take-up and by far the most significant absolute increase of +77,700 m², which corresponds to more than a doubling (+168 %). All of the top deals fall into this category.
Space in the category between 5,001 and 10,000 m² came in third place with 13,000 m² or 7.9 %, up from second place with 25,513 m². Among all space categories, they experienced a decline of 12,513 m² or -49 %. This is a halving compared to the same period last year.
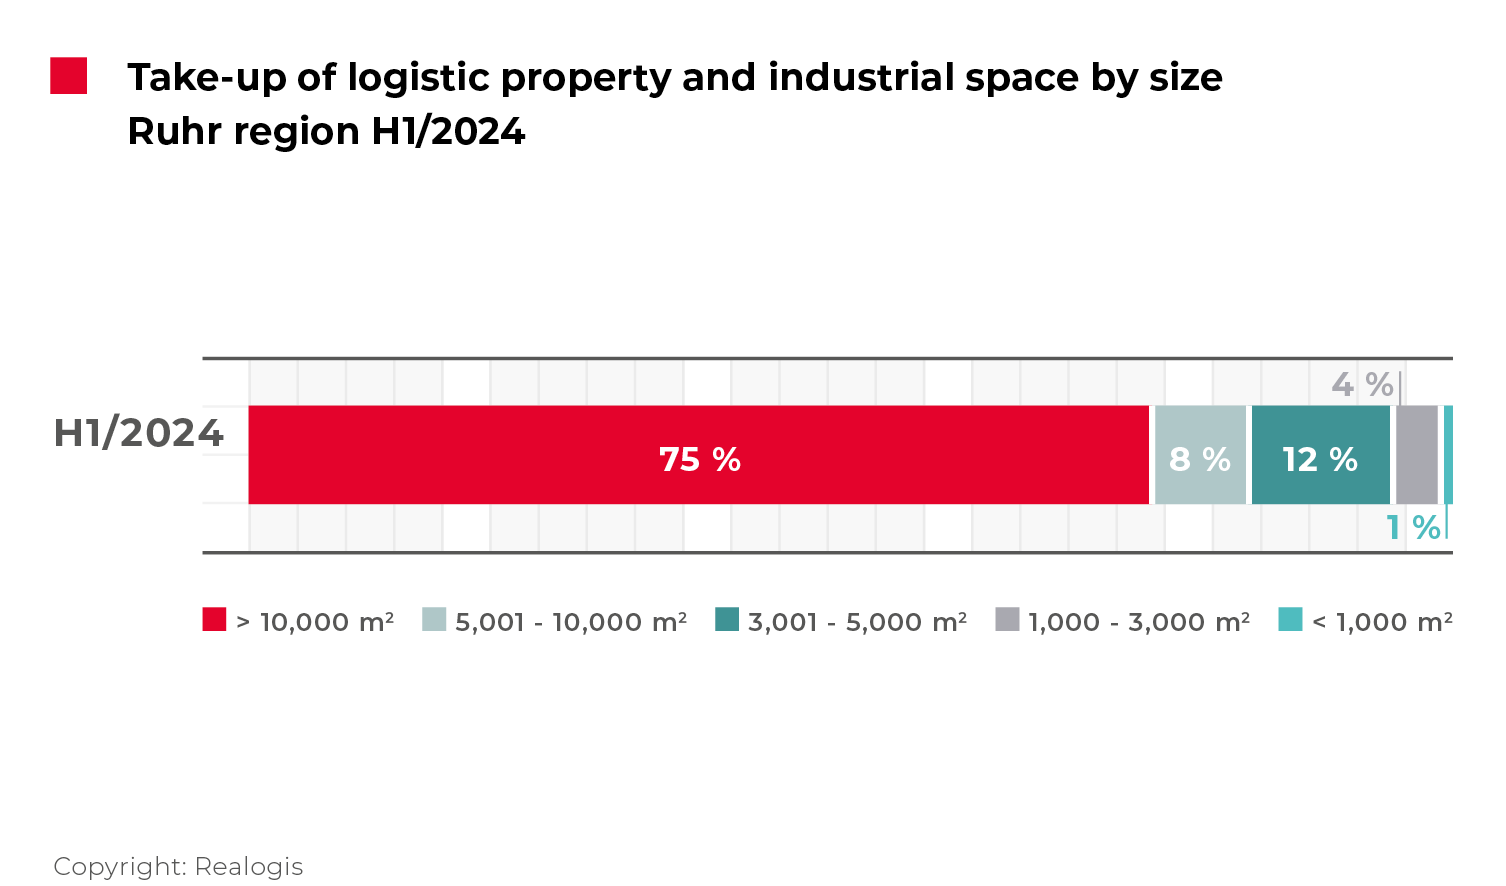
Units between 3,001 and 5,000 m² rose one place to 19,500 m² or 11.8 % and landed in second place. Smaller to medium-sized units between 1,000 and 3,000 m² reached 7,500 m² or 4.6 %, which corresponds to fourth place once again. They have thus improved by 319 m², compared with 7,181 m² or 7.8 % in the previous year. Very small spaces of less than 1,000 m² were hardly significant, with take-up totalling 1,100 m² or 0.7 %. In the previous year, this figure was also only 735 m² or 0.8 %.
Prime rent rises by 19.2 % to EUR 7.75/m²
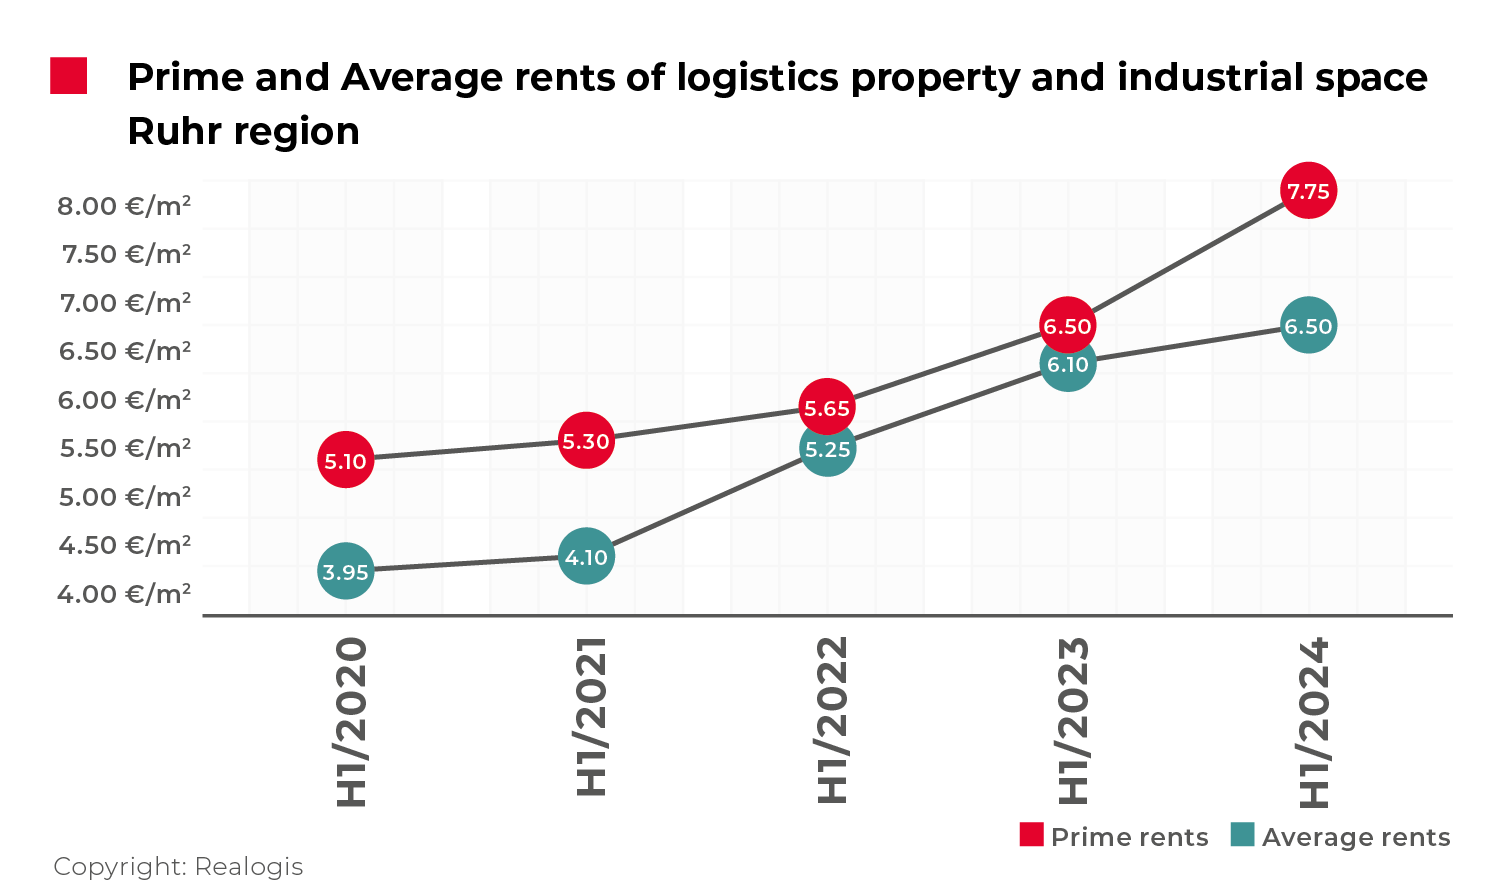
The prime rent on the logistics and industrial property market in the Ruhr region reached a new high in the past six months. It rose by a significant 19.2% to a new high of €7.75/m². Coming from €6.50/m², this is a price increase of €1.25/m². The average prime rent of the last five half-years currently stands at €6.06/m² and has thus been exceeded by 28 %.
The average rent rises to €6.50/m², an increase of 6.6%. The 5-year average of € 5.18/m² is exceeded by 25 %.
Outlook
"The market for industrial and logistics properties in the Ruhr region continues to be characterised by a very low availability of space. The situation is gradually worsening. Larger speculative new builds will not be completed and brought to the market until 2025 and 2026," says Bülent Alemdag. "Central locations in the Ruhr region such as Essen and Duisburg are seeing a large influx. On the one hand, due to the high availability of employees thanks to the high population density, and on the other hand, due to low follow-up costs due to the proximity to harbours. These areas are viewed more sustainably."
Press contact REALOGIS:
SH/Communication - Agency for Public Relations
Silke Westermann
Tel: +49/211/53 88 3-440
E-Mail: s.westermann@shcommunication.de
Company contact REALOGIS:
REALOGIS Holding GmbH
Silja Schuppler
Marketing
Leopoldstraße 154, 80804 München
Tel: +49/89/51 55 69 17
E-Mail: s.schuppler@realogis.de
www.realogis.de
REALOGIS. No. 1 for industrial and logistics properties
The REALOGIS Group is Germany’s leading player for the consulting and brokering of industrial, logistics and commercial properties. Founded in 2005 as a pioneer for the asset class of logistics and industry, the owner-operated group has enjoyed healthy growth, is crisis-resistant and knows the German market like no other. In 2022 Realogis generated nearly 1.25 million m² of usable space alone in the letting segment. The net commission revenue of all services in the financial year 2023 are around EUR 19 million.
In 2021, REALOGIS also won the German Real Estate Prize in the “Commercial Player” category, which honours companies for their outstanding commitment, creativity, innovative strength and sustainability.
Realogis is represented in the country’s seven top logistics locations of Berlin, Düsseldorf, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart, while a dedicated organisational unit ensures transparency in around 15 additional regional logistics markets. 70 real estate professionals advise national and international companies from the fields of logistics, e-commerce, retail and industry as well as private and institutional investors. Quick, flexible, regional, customer-oriented and with a high volume of transactions.
REALOGIS four core competencies are arranging highly creditworthy tenants for new and existing properties, assisting investors with property investments and project development of greenfields and brownfields, outstanding service for locating or selling sites, and the development and implementation of holistic property strategies.
In short, REALOGIS creates more room for its customers’ success in every sense. Further information: https://www.realogis.de/