
Unfortunately, there are no properties on your watch list.
Do you have a question? Leave your contact details here and we will call you back!

Press Release
REALOGIS publishes market analysis regarding Germany’s top locations for logistics, warehousing and industrial space
- Top 8 rental and owner-occupancy markets down 8.5% to 3.53 million m²
- NEW: Evaluation of take-up – the top 8 are tenants’ markets
- Retail sets the pace when it comes to take-up of logistics and warehousing space
- NEW: Size segment category: Large spaces ensure deliveries to the population and secure supply chains
- Sharp rise in prime rents
- 40 biggest deals account for 40% of take-up
“Although take-up has fallen, 2022 was a good year for the top German locations for logistics and industrial properties. Last year saw the second-highest level of take-up on the rental and owner-occupancy markets in the last five years,” said Bülent Alemdag, Managing Director at Realogis. This was also reflected in the fact that take-up exceeded the five-year average of 3.3 million m² by 6.8%.
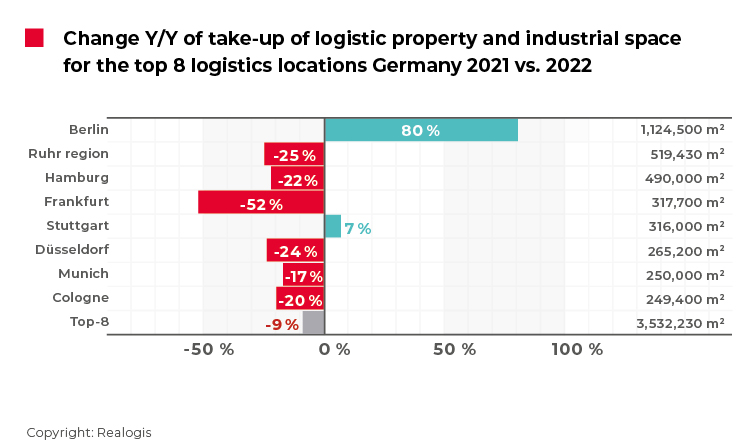
For the first time, the Berlin metropolitan region accounted for the largest share of take-up among the top 8 locations in the past year (2021: 4th place). The capital city recorded take-up of 1.12 million m² in total between January and December 2022, meaning it was responsible for almost one-third (31.8%) of total take-up across all of the top 8 locations. The main reason for this all-time high and the 80% increase as against the prior-year figure of 624,700 m² was the Tesla deal with a volume of 327,000 m².
The previous year’s champion, the Ruhr region, ended up in second place in 2022 with take-up of 519,430 m² (down 25% compared with FY 2021) and a share of 14.7%. Third place was again occupied by Hamburg with take-up of 490,000 m² (down 22% compared with FY 2021) and a share of 13.9%.
The middle places were taken by Frankfurt and Stuttgart. Take-up in Frankfurt came in at 317,700 m², which equated to a share of 9% and was down 52% on the prior-year figure of 655,700 m². Stuttgart was the only German metropolitan region other than Berlin to record growth, with take-up amounting to 316,000 m² (up 7% compared with FY 2021) for a share of 8.9%.
Three of the top German locations came in at below 300,000 m²: Düsseldorf (265,200 m² or 7.5%; down 24% compared with FY 2021), Munich (250,000 m² or 7.1%; down 17% compared with FY 2021) and Cologne (249,400 m² or 7.1%; down 20% compared with FY 2021).
In terms of take-up, the past year was not positive for every sub-market. Looking at average take-up for the last five years, Berlin (77%) and Stuttgart (41%) were the only markets to significantly outperform their five-year average in 2022 (634,878 m² and 223,352 m² respectively). Hamburg (498,000 m²), Cologne (241,480 m²) and Düsseldorf (265,240 m²) were at or close to their five-year average at -2%, 3% and 0% respectively. Munich (302,700 m²) and the Ruhr region (617,000 m²) were unable to keep pace with their recent performance, with take-up coming in at 17% and 16% lower than the five-year average respectively.
NEW: Evaluation of take-up – the top 8 are tenants’ markets
In its latest market analysis of the top locations, Realogis has also examined the user structure in greater detail for the first time. Tenants were responsible for the majority of market activity in the past year, making up almost four out of every five square metres of take-up (2.8 million m² or 79%). Owner-occupiers were responsible for only 21% or 712,500 m², with the Tesla deal alone accounting for almost half of this figure.
Retail sets the pace when it comes to take-up of logistics and warehousing space / Manufacturing up 80%
In terms of take-up by sector, retail led the way in 2022 with 1.24 million m² and a share of 35.2%, having been ranked second in the previous year at 1.35 million m².
“Retail set the pace when it came to the new use of logistics and warehousing space in 2022 as a whole, replacing logistics and distribution companies at the top of the list,” observed Jörg Lojewski, Managing Director at Realogis.
“We also examined the roles of traditional retail and e-commerce for the first time. In 2022, the majority of take-up – 739,702 m² or 59.4% – was attributable to companies operating in the area of traditional retail. E-commerce companies accounted for 505,272 m² or a share of 40.6%,” added his fellow Managing Director Stefan Imken.
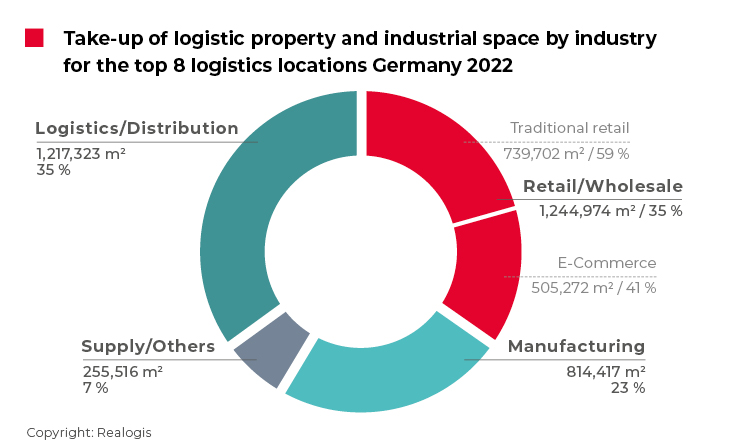
Logistics/distribution occupied second place just behind retail with take-up of 1.21 million m² or 34.5%. In the previous year, logistics/distribution was the clear winner with a share of 45.6% and take-up of 1,76 million m², meaning its share of the market declined by 11.1 percentage points in 2022. It also saw the biggest downturn in absolute take-up among all three sectors at -30.8%. Manufacturing remains in third place with take-up of 814,417 m² and a share of 23.1% (FY 2021: 451,242 m²; 11.7%). This meant it recorded the biggest proportionate rise in take-up across all three sectors at 11.4 percentage points, as well as increasing its absolute take-up by 80%. Last place once again went to the “Other” category with 255,516 m² or 7.2%.
NEW: Take-up by size category
For the first time, Realogis also analysed the most popular size segments in the top 8 German locations for logistics, warehousing and industrial properties. “Large spaces of 10,001 m² or more proved to be by far the most popular choice to meet the needs of retail, logistics and industry in the top 8 German locations when it comes to supplying goods to the population and creating functional, crisis-resistant supply chains,” said Julian Petri, Managing Director at Realogis. This size segment accounted for total take-up of 2.24 million m² or 63.4% in 2022.
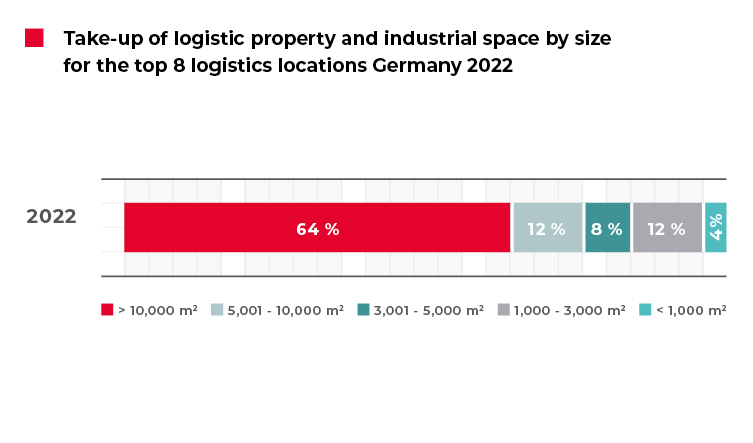
Larger spaces between 5,001 and 10,000 m² took third place with 424,078 m² or 12%, while medium-sized to larger spaces between 3,001 and 5,000 m² were ranked fourth with 291,026 m² or 8.2%. Small to medium-sized spaces were the second most popular size category, accounting for take-up of 432,060 m² and a share of 12.2%, while the smallest spaces came in last at 146,530 m² or 4.1%.
Sharp rise in prime rents
“Prime rents increased significantly in all eight of the markets included in the analysis,” said Joel Adam, Managing Director at Realogis. “Compared with 2021, the average increase across the top 8 markets was over 14.3%.”
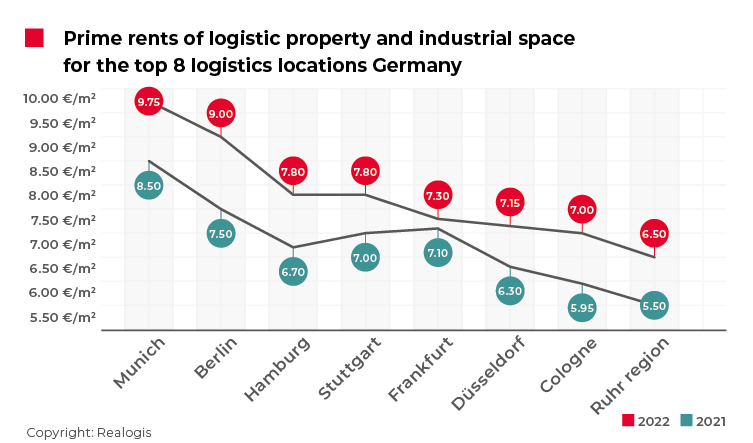
With the exception of Frankfurt, all of the markets recorded double-digit growth.
The most expensive location is still Munich at EUR 9.75/m² (up 14.7% from EUR 8.50/m²). Berlin remains in second place at EUR 9.00/m² (up 20% from EUR 7.50/m²). Having placed fifth in the previous year, Hamburg is ranked joint third at EUR 7.80/m² (up 16.4% from EUR 6.70/m²) alongside Stuttgart, last year’s fourth-placed market (up 11.4% from EUR 7.00/m²). Frankfurt, which was the third most expensive location in the previous year, occupies fifth place at EUR 7.30/m² (up 2.8% from EUR 7.10/m²) Düsseldorf is ranked sixth at EUR 7.15/m² (up 13.5% from EUR 6.30/m²). Despite recording the third-highest growth rate among the top 8 locations, Cologne remains near the bottom of the list and is the second most affordable market at EUR 7.00/m² (up 17.6% from EUR 5.95/m²). As previously, the Ruhr region is the most affordable location at EUR 6.50/m² (up 18.2% from EUR 5.50/m²), making it the only market with prime rent below EUR 7.00/m².
40 biggest deals account for almost 40% of total take-up
“With a total of 1.35 million m², the 40 biggest deals by all market participants accounted for around 38% of total take-up in 2022 across all of the top 8 locations,” said Julian Petri, Managing Director at Realogis.
| No. | Region | User | Take-up | Industry | Type |
1 | Berlin | Tesla | 327,000 m² | Manufacturing | New build |
2 | Ruhr region | ITG | 50,000 m² | Logistics/distribution | New build |
3 | Ruhr region | Picnic | 50,000 m² | E-commerce | New build |
4 | Ruhr region | LIDL | 50,000 m² | Traditional retail | New build |
5 | Hamburg | Aldi | 42,500 m² | Traditional retail | New build |
6 | Berlin | Sonepar | 41,250 m² | Traditional retail | New build |
7 | Frankfurt | B+S | 39,500 m² | Logistics/distribution | Existing property |
8 | Berlin | Tesla | 38,887 m² | Manufacturing | New build |
9 | Stuttgart | REWE | 35,000 m² | Traditional retail | Existing property |
10 | Stuttgart | Unknown | 33,263 m² | Logistics/distribution | New build |
11 | Berlin | LIDL | 32,738 m² | Traditional retail | New build |
12 | Düsseldorf | Vaillant Group | 32,000 m² | Manufacturing | New build |
13 | Berlin | Schnellecke | 30,800 m² | Logistics/distribution | New build |
14 | Hamburg | Airbus | 30,000 m² | Manufacturing | Existing property |
15 | Cologne | LIDL | 30,000 m² | Traditional retail | Existing property |
16 | Cologne | Hammer | 30,000 m² | Logistics/distribution | New build |
17 | Hamburg | Pfaff Logistik | 29,500 m² | Logistics/distribution | Existing property |
18 | Ruhr region | WM Group | 29,423 m² | Logistics/distribution | New build |
19 | Munich | Winning BLW | 28,000 m² | Manufacturing | Existing property |
20 | Cologne | Computacenter | 28,000 m² | Other | Existing property |
21 | Ruhr region | ALT Finecom | 28,000 m² | Logistics/distribution | Existing property |
22 | Frankfurt | Rexel | 26,000 m² | Traditional retail | New build |
23 | Hamburg | Picnic | 25,000 m² | E-commerce | New build |
24 | Hamburg | JYSK | 24,000 m² | Traditional retail | New build |
25 | Cologne | Siewert & Kau | 23,000 m² | E-commerce | New build |
26 | Stuttgart | E. Breuninger | 22,282 m² | E-commerce | Existing property |
27 | Düsseldorf | Picnic | 20,000 m² | E-commerce | New build |
28 | Düsseldorf | Bohnen Logistik | 19,356 m² | E-commerce | New build |
29 | Stuttgart | Krannich Solar | 16,000 m² | Traditional retail | New build |
30 | Stuttgart | Tesla Motors Netherlands | 15,460 m² | Manufacturing | Existing property |
31 | Munich | DHL | 14,000 m² | Logistics/distribution | New build |
32 | Düsseldorf | Galaxus | 14,000 m² | E-commerce | New build |
33 | Cologne | Offergeld | 14,000 m² | Logistics/distribution | New build |
34 | Düsseldorf | Gate 41 Logistics | 13,364 m² | Logistics/distribution | Existing property |
35 | Munich | Proton Motor Fuel Cell | 13,200 m² | Manufacturing | Existing property |
36 | Frankfurt | Atrikom | 12,532 m² | Logistics/distribution | New build |
37 | Munich | Mynaric | 11,000 m² | Manufacturing | Existing property |
38 | Frankfurt | Grieshaber Logistics Group | 10,495 m² | Logistics/distribution | New build |
39 | Frankfurt | Breitfeld und Schliekert | 10,177 m² | Traditional retail | Existing property |
40 | Munich | FS.COM | 8,800 m² | E-commerce | Existing property |
REALOGIS media contact:
Silke Westermann
Senior public relations specialist
Tel: +49/211/53 88 3-440
e-mail: s.westermann@shcommunication.de
REALOGIS company contact:
REALOGIS Holding GmbH
Silja Schuppler
Marketing
Rundfunkplatz 4, 80335 Munich
Tel: +49/89/51 55 69 17
e-mail: s.schuppler@realogis.de
www.realogis.de
REALOGIS. No. 1 for industrial and logistics properties
The REALOGIS Group is Germany’s leading player for the consulting and brokering of industrial, logistics and commercial properties. Founded in 2005 as a pioneer for the asset class of logistics and industry, the owner-operated group has enjoyed healthy growth, is crisis-resistant and knows the German market like no other. In 2021 Realogis generated nearly 1,3 million m² of usable space alone in the letting segment. The net commission revenue of all services in the financial year 2021 are EUR 25 million.
In 2021, REALOGIS also won the German Real Estate Prize in the “Commercial Player” category, which honours companies for their outstanding commitment, creativity, innovative strength and sustainability.
Realogis is represented in the country’s seven top logistics locations of Berlin, Düsseldorf, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart, while a dedicated organisational unit ensures transparency in around 15 additional regional logistics markets. 70 real estate professionals advise national and international companies from the fields of logistics, e-commerce, retail and industry as well as private and institutional investors. Quick, flexible, regional, customer-oriented and with a high volume of transactions.
REALOGIS four core competencies are arranging highly creditworthy tenants for new and existing properties, assisting investors with property investments and project development of greenfields and brownfields, outstanding service for locating or selling sites, and the development and implementation of holistic property strategies.
In short, REALOGIS creates more room for its customers’ success in every sense. Further information: https://www.realogis.de/