
Unfortunately, there are no properties on your watch list.
Do you have a question? Leave your contact details here and we will call you back!

Press Release
NRW: REALOGIS analyses the market for logistics and industrial properties in the first half of 2024
- Take-up growth: declining trend broken
- No owner-occupier contracts
- Big box spaces remain the dominant building type
- Ranking of the top three markets: Cologne with an increase of over 100,000 m² of take-up
- Industry ranking: First-placed retail triples previous year's result
- Two thirds of take-up take place in units of 10,000 m² or more
- Prime rents rise significantly in all NRW submarkets
- Outlook: New construction areas are not planned until 2025/2026
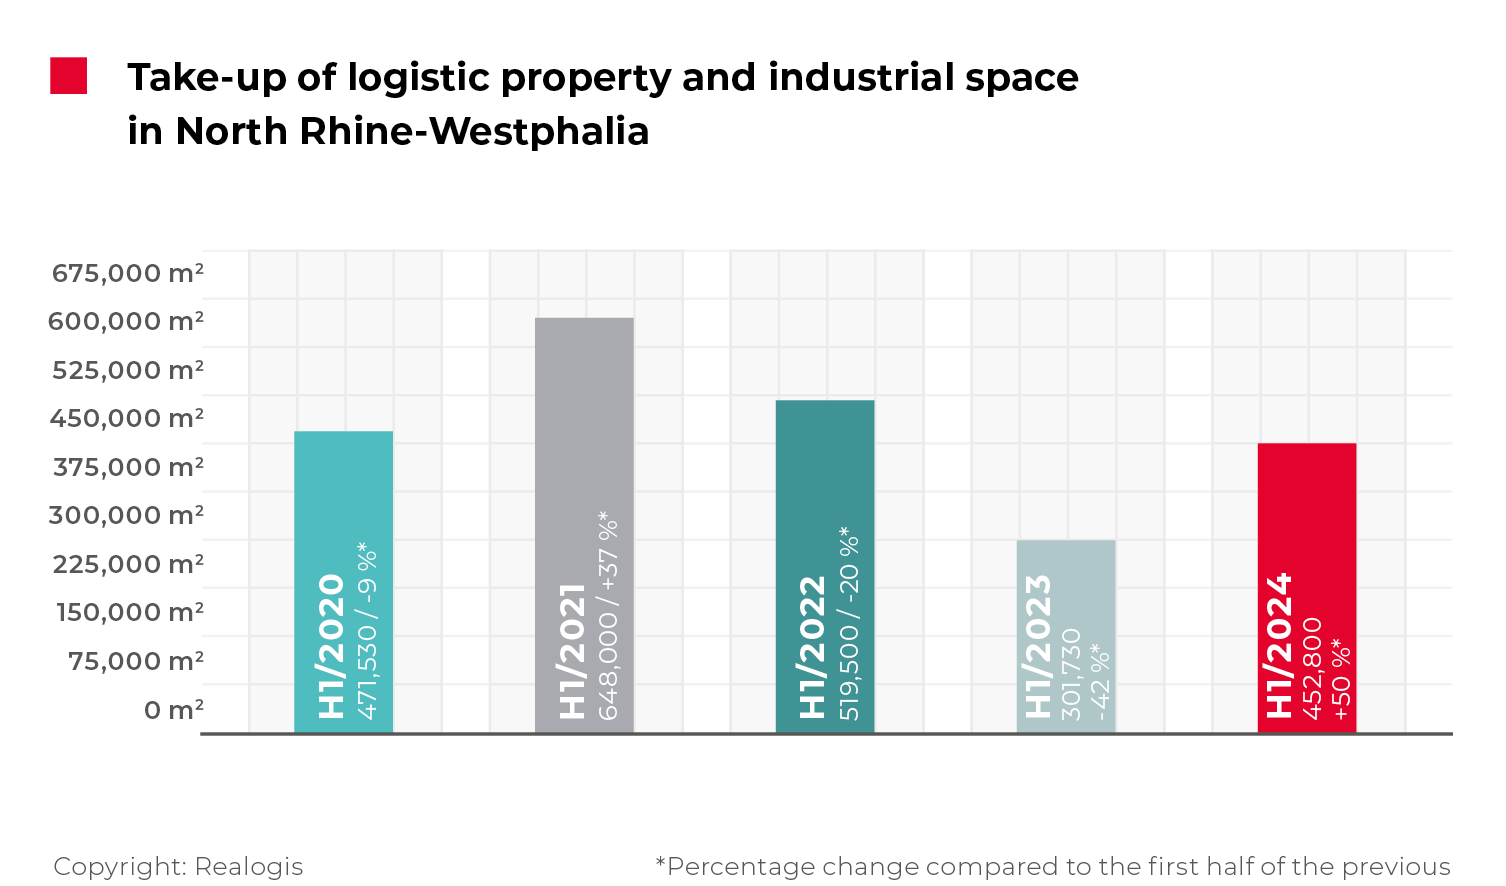
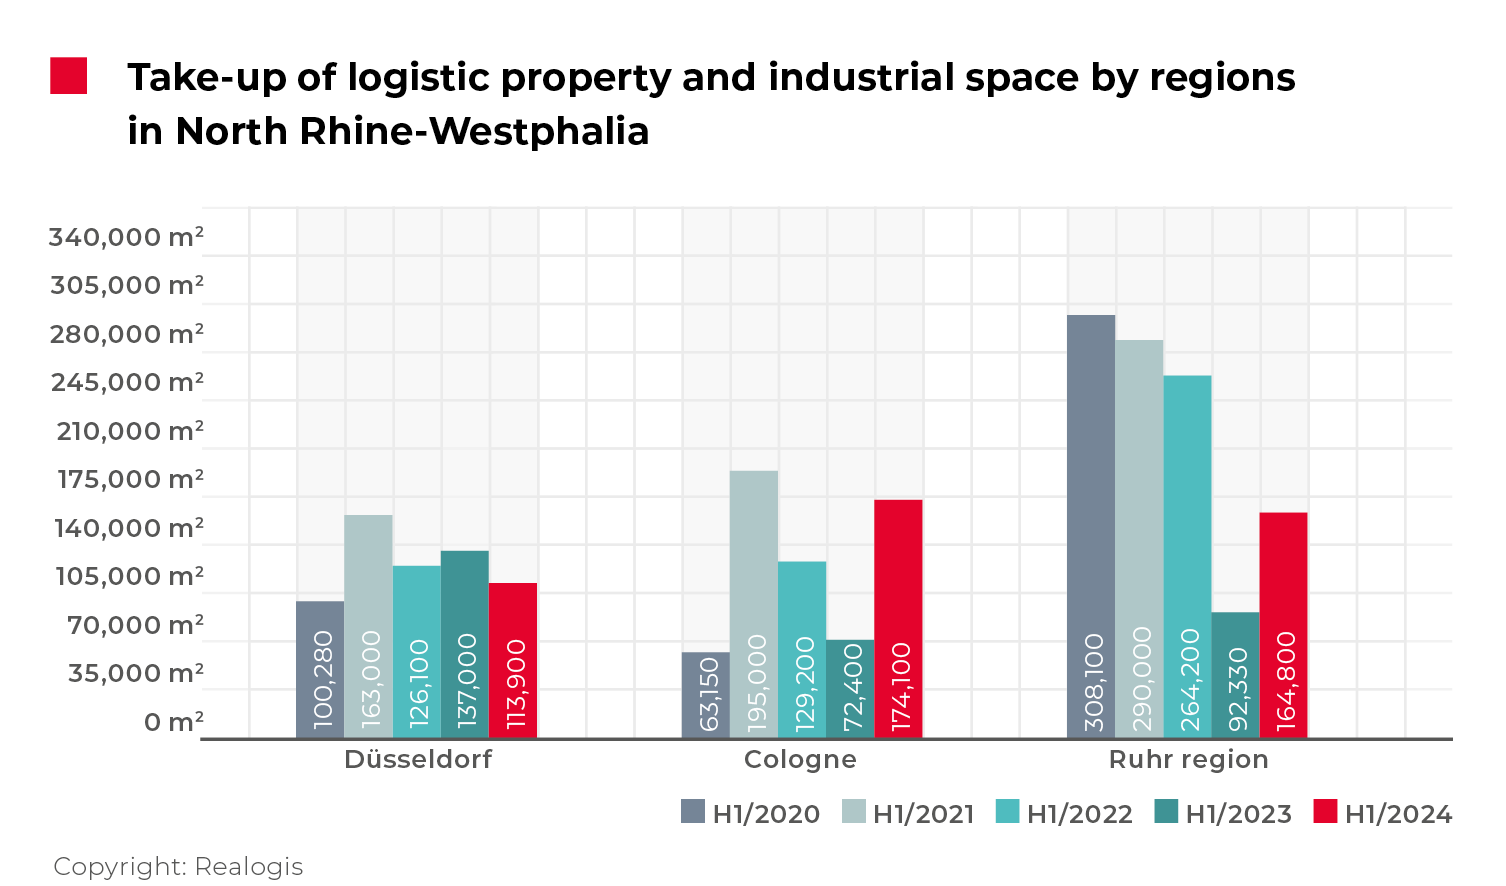
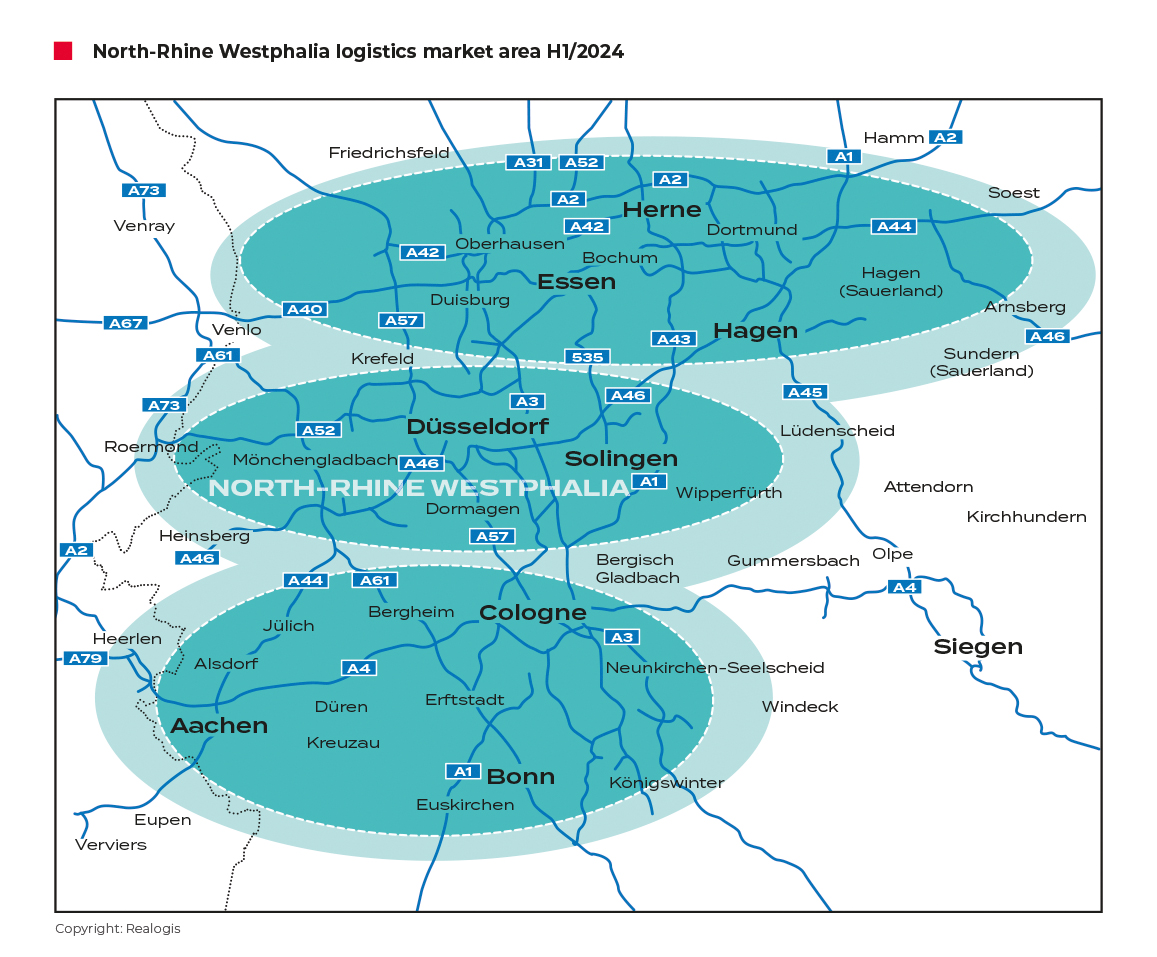
The result achieved by all market participants in the conurbations of Cologne, Düsseldorf and the Ruhr area is 151,070 m² or 50 % up on the same period last year.
These and other results are provided by the latest market report from Realogis, Germany's leading consultancy for industrial and logistics properties and commercial land.
This breaks the downward trend of the last two prior-year periods (H1 2023: 301,730 m², which represented a slump of -41.9 % or -217,770 m² compared to 519,500 m² in H1 2022; H1 2022: 519,500 m², -19.8 % or -128,500 m² compared to 648,000 m² in H1 2021).
After the 5-year average was missed by a significant 39 % in the same period of the previous year (H1 2023: 491,506 m²), it is almost on a par with the current total take-up in the first half of 2024 at 478,712 m². Accordingly, it is currently only 5% below the average. Nevertheless, the past six months only ranked fourth out of five. Only the first half of 2023 was lower at 301,730 m².
"The market is dominated by lettings in existing space with 299,650 m² or 66.2%," reports Bülent Alemdag, Managing Director of Realogis Immobilien Düsseldorf GmbH, which manages all three NRW top markets. At +124,050 m² or +70.6% compared to the same period last year, they represent the most significant increase of all types of agreements (H1 2023: 175,600 m² or 58.2%). New build lettings account for 96,050 m² or 21.2 %. Coming from 126,130 m² or 41.8 %, they are therefore significantly less important and also lost 30,080 m² of take-up in absolute terms (or -23.8 %).
Rental transactions in properties on former brownfield sites totalled 57,100 m² or 12.6 %. Realogis did not observe any transactions on former brownfield sites in the previous year.
"As in the same period last year, there were no rental transactions by owner-occupiers," says Bülent Alemdag. The last contracts for properties for owner-occupation were concluded in the 1st half of 2022 with 38,900 m² of 519,500 m² (or 7.5 %).
In terms of building type, big box space continues to dominate at 311,600 m² or 68.8 % with a significant absolute increase of 103,534 m² or 49.8 % (H1 2023: 208,066 m² or 69 %). Other properties that cannot be categorised as big boxes or business parks account for 86,360 m² or 19.1 % (H1 2023: 49,633 m² or 16.4 %). This corresponds to an absolute increase of 36,727 m² or 74%. Business parks increased by 10,809 m² or 24.5 % to 54,840 m² or 12.1 % (H1 2023: 44,031 m² or 14.6 %).
"All property types recorded growth, especially large-scale lettings, although their share of total take-up remained almost the same compared to the previous year," reports Bülent Alemdag.
Ranking of the top three markets: Cologne with an increase of over 100,000 m² of space take-up
In terms of submarkets, Cologne's logistics and industrial lettings market is the strongest with 174,100 m² or a share of 38.4 %, putting it slightly ahead of the Ruhr region. With an increase of +101,700 m², the Cologne market recorded the most significant growth of all sub-markets. This corresponds to more than a doubling and is accompanied by a significant increase in importance in relation to the total take-up of space in NRW (+14.5 percentage points).
The Ruhr region remains in second place with take-up of 164,800 m² or 36.4 % (H1 2023: 92,330 m² or 30.6 %). An increase in take-up of 72,470 m² compared to the same period last year represents an increase of 78.5 %.
Only the Düsseldorf sub-market is in decline and currently stands at 113,900 m² or a share of 25.2 %. Starting from 137,000 m², this represents a decline of 16.9 % or 23,100 m².
Bülent Alemdag: "However, the two submarkets of Cologne and the Ruhr region were able to more than compensate for this decline, resulting in an increase of 151,070 m² for the NRW market as a whole in a half-year comparison."
Sector ranking: First-placed retail sector triples previous year's result
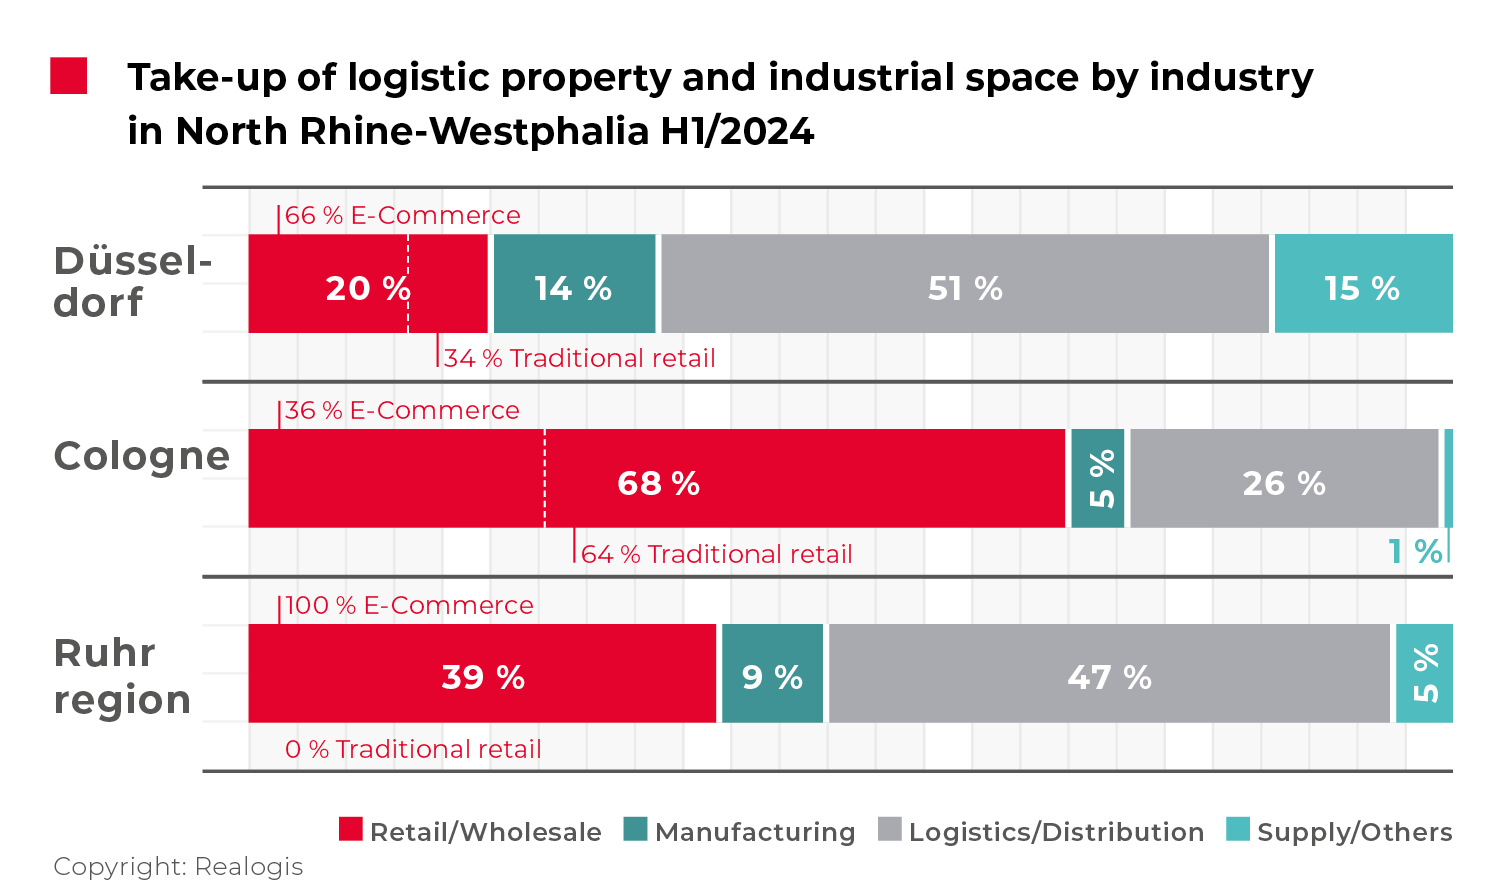
The strongest sector in NRW in H1 2024 is the previously second-placed retail sector with 204,800 m² or 45.2% after 70,260 m² or 15.5% in the same period of the previous year. With +134,540 m² or an almost tripling of the previous year's result, it recorded by far the most significant growth of all sectors.
However, a look at the 5-year average shows how weak demand from retailers was in the previous year: despite the very significant increase, the average of 191,043 m² was only exceeded by 7.2% and is therefore slightly above average.
The driving force behind demand for space was e-commerce with 121,400 m² or a share of 59.3%, which increased by 60,190 m² or 98.3% from 61,210 m² or 87.1%. Traditional retail accounted for 83,400 m² or 40.7%, which corresponds to an increase of 74,350 m² or more than a ninefold increase from just 9,050 m² or 12.9% in the previous year.
As a result of this strong growth, traditional retail was able to increase its share of take-up in the retail category by 27.8 percentage points (the dominance of e-commerce from the previous year was reduced accordingly by these 27.8 percentage points).The logistics/distribution sector follows in second place with 181,600 m² or 40.1 % (H1 2023: first place with 148,185 m² or 49.1 %). The growth of 33,415 m² or 22.5 % is not enough to maintain first place. The 5-year average of 227,636 m² was also missed by a significant 20.2 % despite the growth.
Manufacturing is again in third place with 39,000 m² or 8.6 % (H1 2023: 53,070 m² or 17.6 %). With a decrease of 14,070 m² or 26.5 %, this is the sharpest decline of all sectors. Nevertheless, the 5-year average of 37,276 m² will be exceeded by 4.6 %.
The miscellaneous “supply/other” category remains at the bottom of the table with 27,400 m² or 6.1 %, down by a moderate 2,815 m² or 9.3 % from 30,215 m² or 10 %. The declines in manufacturing and the miscellaneous category were more than compensated for by the in some cases significant increases in retail and logistics/distribution.
Two thirds of take-up take place in units of 10,000 m² or more
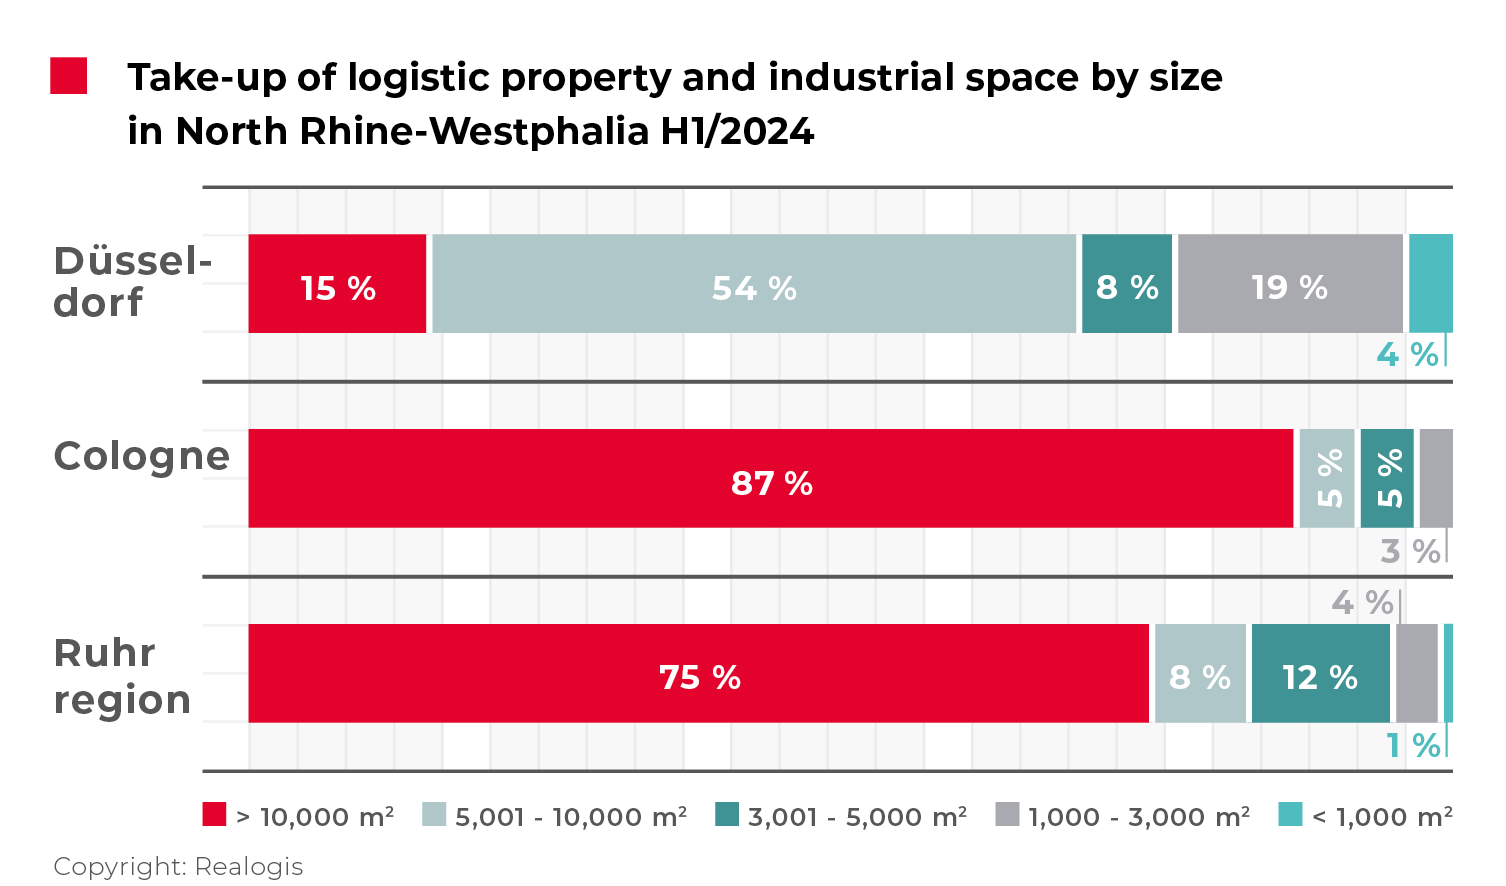
When analysing the size categories, large spaces of 10,000 m² or more continue to dominate. At 291,700 m² or 64.4 %, they account for almost two thirds of take-up in NRW. Starting from 170,547 m² or 56.5 %, this represents a significant increase of 121,153 m² or 71 %.
Units in the 5,001 m² to 10,000 m² range accounted for 82,485 m² or 18.2 % and remained in second place, up from 56,332 m² or 18.7 % (second-highest growth of +26,153 m² +46.4 %).
"Together with the large spaces, 82.7% of total take-up is therefore accounted for by spaces over 5,001 m²," reports Bülent Alemdag. "In the previous year, this figure was around 7 percentage points lower at 75.2 %."
In third place comes the size category between 3,001 and 5,000 m² with 37,800 m² or 8.3 %, down by 3,315 m² or 8.1 % from 41,115 m² or 13.6 % (the only year-on-year decline). The next smallest category between 1,000 and 3,000 m² follows in fourth place with 7.8 % or 35,315 m² after 30,406 m² or 10.1 %, which corresponds to an increase of 4,909 m² or 16.1 %.
In last place are micro-spaces of less than 1,000 m², which at 1.2 % or 5,400 m² continue to be of comparatively minor importance and were able to increase by 2,070 m² from 3,330 m² or 1.1 %.
Prime rents rise significantly in all NRW submarkets - average rents also rising
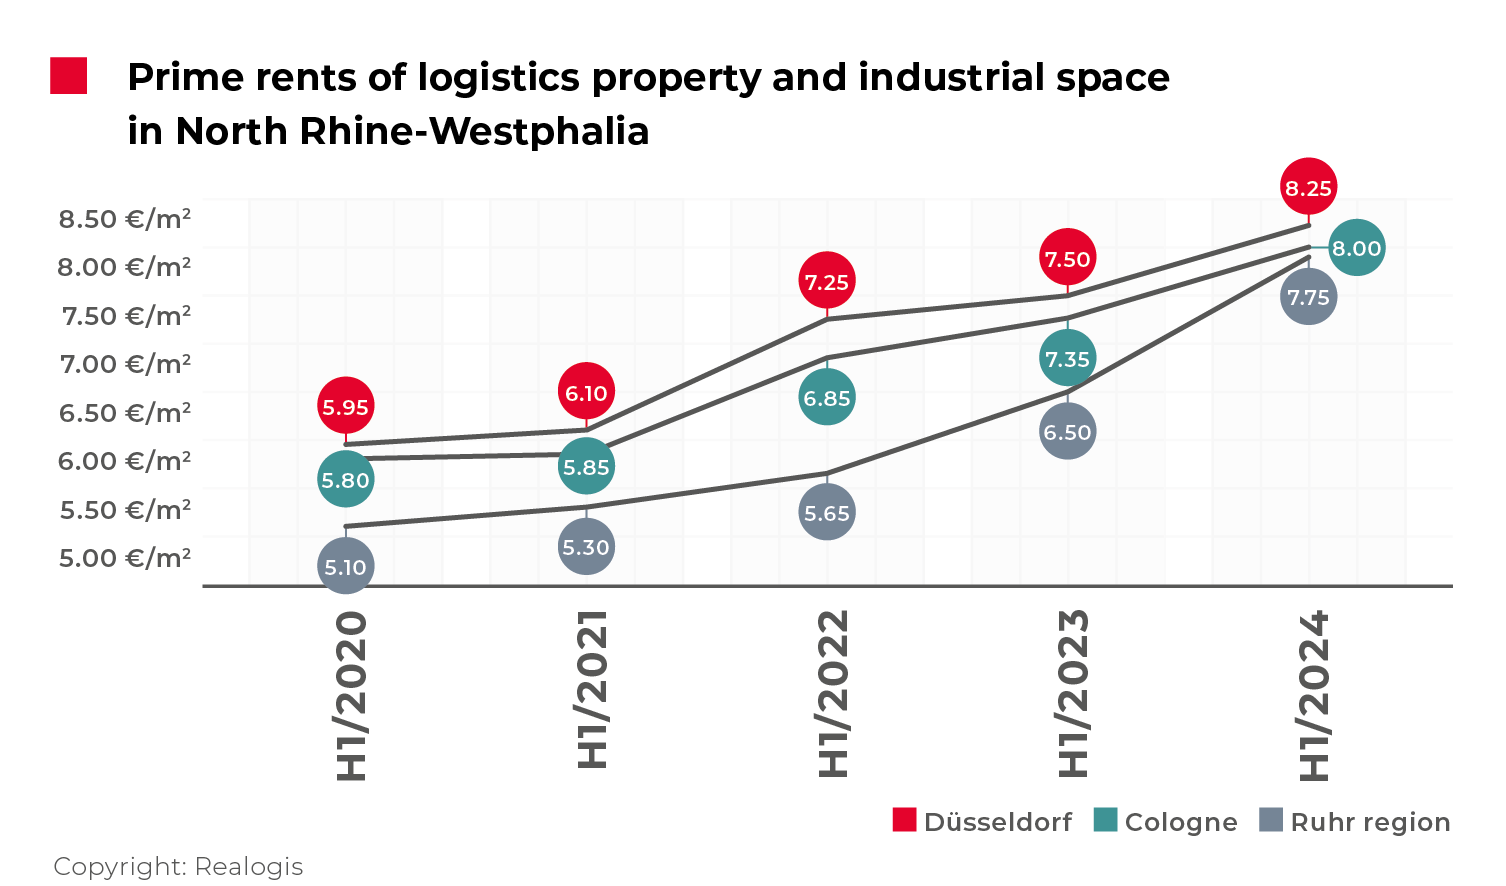
Prime rents rose significantly in all 3 markets and reached their respective highs in all 3 submarkets:
- Düsseldorf: € 8.25/m², coming from € 7.50/m² (+10 %)
- Cologne: €8.00/m², up from €7.35/m² (+8.8 %)
- Ruhr area: € 7.75/m², coming from € 6.50/m² (+19.2 %)
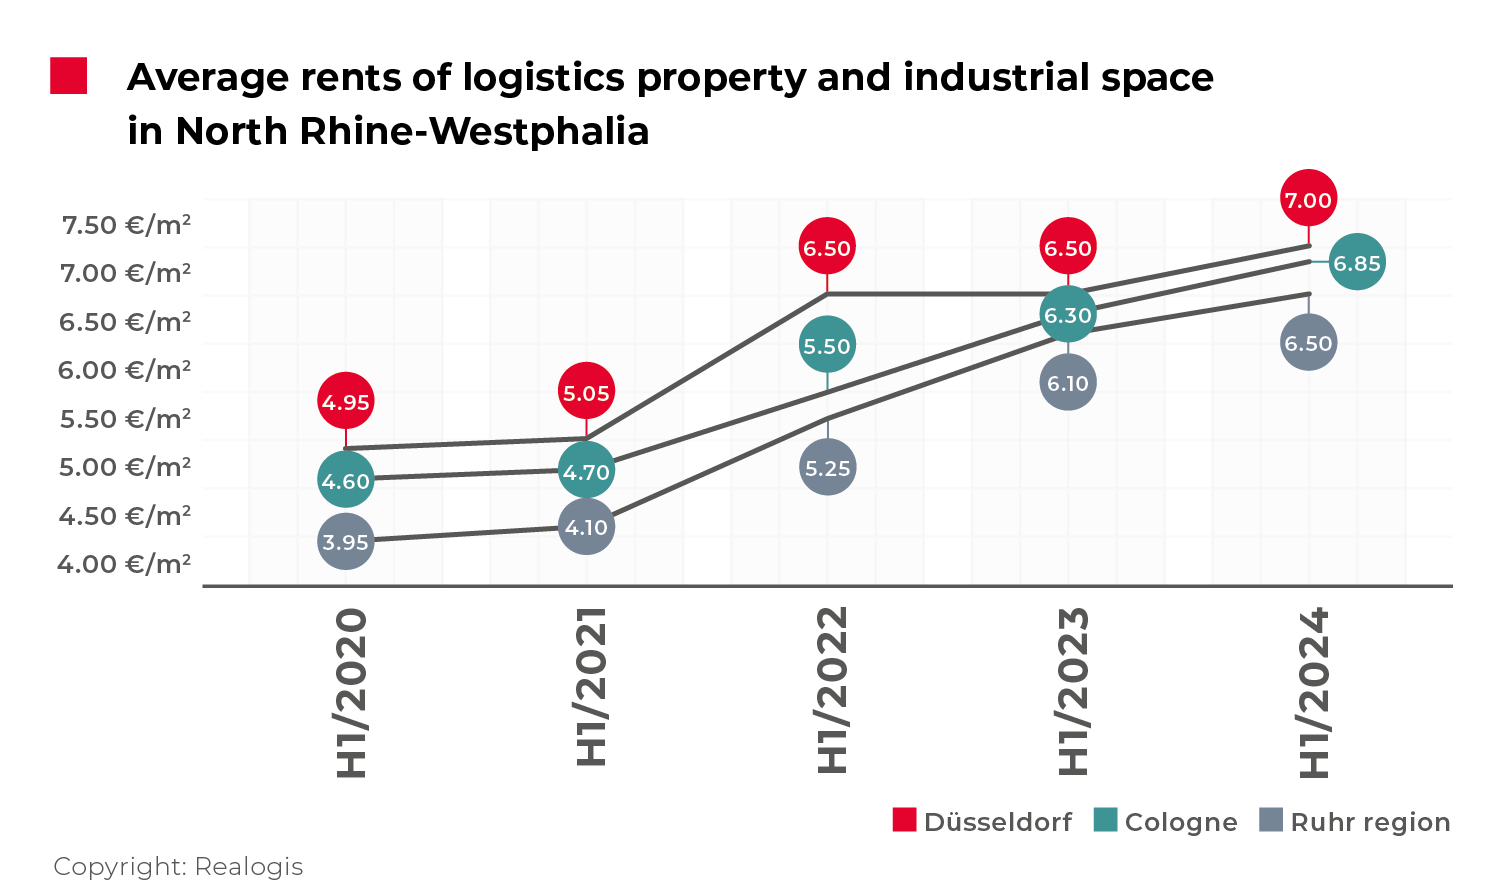
Average rents also increased across the board:
- Düsseldorf: € 7.00/m² (+7.7 %), coming from € 6.50/m²
- Cologne: €6.85/m² (+8.7 %), coming from € 6.30/m²
- Ruhr region: €6.50/m² (+6.6 %), coming from € 6.10/m²
Outlook
"Due to the economic situation, the top NRW markets for industrial and logistics properties have returned to their normal level. Demand is moderate and companies are no longer making short-term decisions. New builds are not planned until 2025/2026; whether they will be developed speculatively depends on whether investors and property developers become more courageous again," says Bülent Alemdag, outlining the next 24 months.
Press contact REALOGIS:
SH/Communication - Agency for Public Relations
Silke Westermann
Tel: +49/211/53 88 3-440
E-Mail: s.westermann@shcommunication.de
Company contact REALOGIS:
REALOGIS Holding GmbH
Silja Schuppler
Marketing
Leopoldstraße 154, 80804 Munich
Phone: +49/89/51 55 69 17
E-mail: s.schuppler@realogis.de
www.realogis.de
REALOGIS. The No. 1 for industrial and logistics properties
The REALOGIS Group is Germany's leading address for consulting and brokerage services for industrial and logistics properties and commercial land. Founded in 2005, the owner-managed, healthily grown and crisis-proof group of companies knows the German market like no other. In 2022, REALOGIS achieved a turnover of 1.251 million m² of brokered usable space in the lettings segment alone. Net commission income from all services totalled around 19 million euros in the 2023 financial year.
REALOGIS won the 2021 German Real Estate Award in the "Commercial Player" category. The award recognises companies for their special commitment, creativity, innovative strength and sustainability.
The group of companies includes the eight branches in Berlin, Düsseldorf, Germany South/North, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart.
74 REALOGIS property professionals provide advice and support to national and international companies from the logistics, e-commerce, retail and industrial sectors as well as private and institutional investors. Fast, flexible, regional and customer-orientated.
The four core competences include finding tenants with strong credit ratings for existing and new properties, supporting investors in property investments and in the project development of greenfield and brownfield sites, providing a perfect service for finding or selling properties and developing and implementing holistic property strategies. This covers the entire property cycle - from location analysis and optimisation of expansion targets to the sale of assets that are no longer required for operations.
In short: REALOGIS offers "More space for your success" in every respect.