
Unfortunately, there are no properties on your watch list.
Do you have a question? Leave your contact details here and we will call you back!

Press Release
Munich region: REALOGIS analyses the market for logistics and industrial properties in the first half of 2025
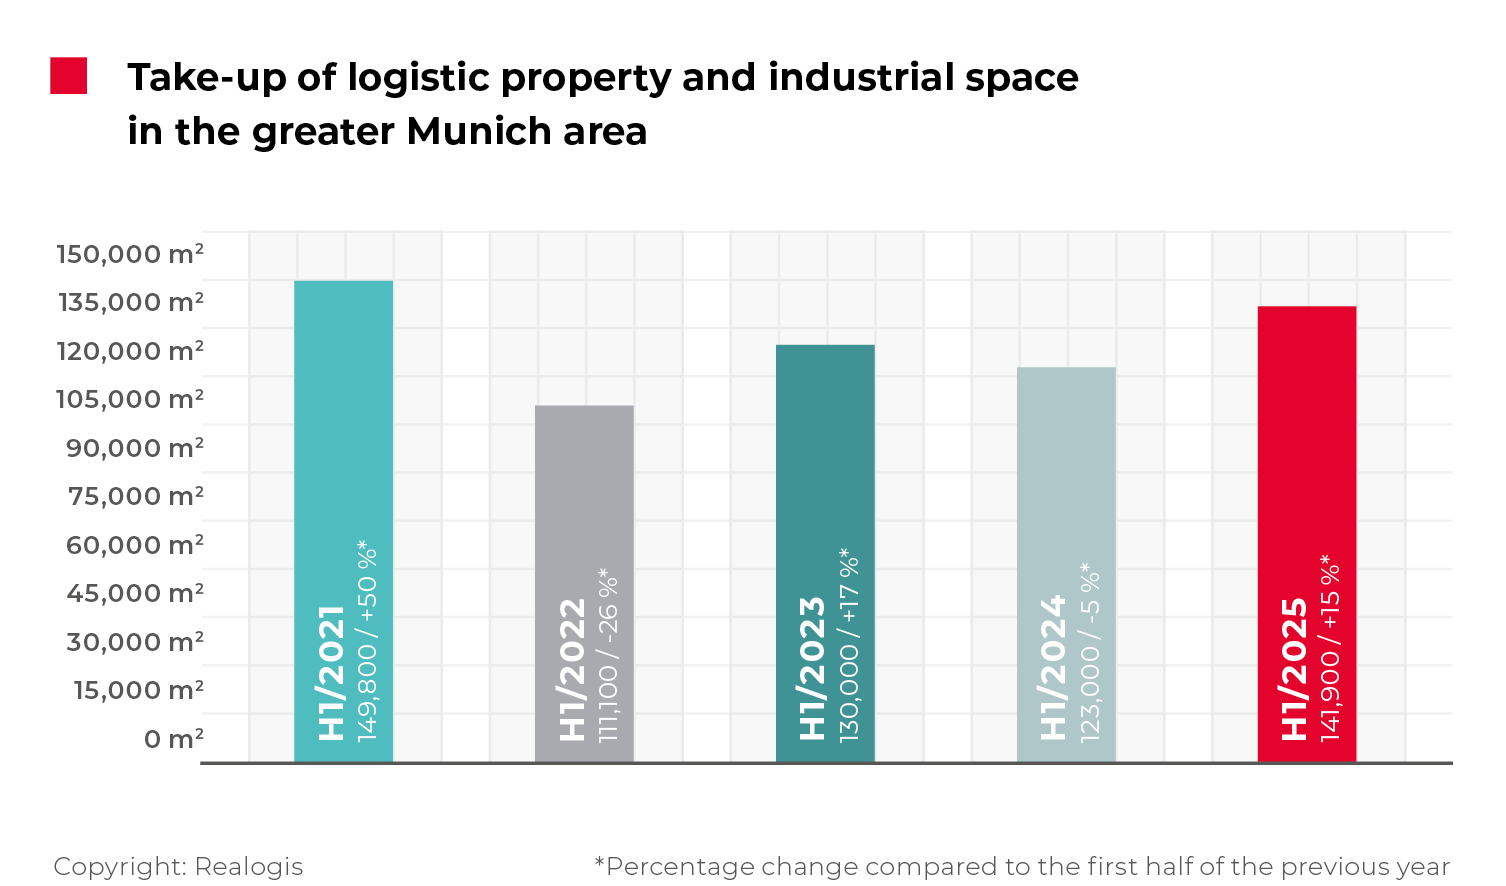
- Munich market with outstanding take-up of 141,900 m² in the first half of 2025
- Existing properties lead and increase market share by 10 %
- Big box properties multiply market share to 47 %
- Northern Munich dominates with two out of three m² taken up in the overall market
- Retail replaces manufacturing as the strongest industry in take-up
- Ranking of size categories: Large spaces with 38 % increase in take-up
- New record: prime rent increases by 29 % to €13.50/m²
- Outlook: Realogis expects a total annual take-up of 240,000 m²
"As there have been few large spaces available on the Munich market for years, units that become vacant are quickly absorbed. Market activity in the first half of the year was mainly characterized by large-scale transactions by companies that are expanding or have relocated. This trend will continue in the second half of the year due to the many registered requests for large spaces over 10,000 m²," comments Nicolas Werner, Managing Director of Realogis Immobilien München GmbH.
The year-on-year growth in H1 2025 totalled 18,900 m² in absolute terms and exceeded the 5-year average of the last five first half-years by 8 % (131,160 m²).
This was mainly due to transactions in existing properties, which accounted for 79,000 m² or 56 %. Compared to the previous year's level of 72,100 m², this represents an increase of 6,900 m² or +10 %.
"As only a few new developments are possible in the Munich region, the existing stock is being developed further. Value-add properties are being refurbished and revitalized, particularly in the ESG segment. This includes activities such as district heating or heat pumps, the conversion to LED lighting and the installation of solar systems," says Nicolas Werner.
In second place are lettings of new buildings on former brownfield sites with 32,600 m² or 23 %, which mainly attributable to a single transaction by the retail company REPA in the north of Munich. Brownfield developments did not play a role in the same period of the previous year. Lettings in new buildings on greenfield sites accounted for the remaining 21 % or 30,300 m², representing a significant decline of 20,600 m² or -40 % (H1 2024: 50,900 m² or 41 %).
Key take-up drivers
Company | Market area | Take-up | Type | Industry |
REPA | North | 32,600 m² | New building (brownfield) | Retail/Wholesale |
Producer | North | 10,930 m² | New building | Manufacturing |
Logistician | North | 10,830 m² | Existing building | Logistics/Distribution |
Public sector | North | 9,000 m² | Existing building | Others |
Trading company | East | 8,700 m² | New building | Retail/Wholesale |
In terms of building type, lettings in big box properties lead with a market share of 47 % or 66,500 m², more than doubling their result by 39,300 m² or 145 % (H1 2024: 27,200 m² or 22 %). Rentals in business parks totalled 31,200 m² or 22% (H1 2024: 26,500 m² or 22%). The increase is 4,700 m², while the proportionate importance for the market remains unchanged. Properties that cannot be allocated to either big boxes or business parks totalled 44,200 m² or 31 % (H1 2024: 69,300 m² or 56 %, significant decline of 25,100 m² or 36 %).
Regional ranking: Northern Munich dominates
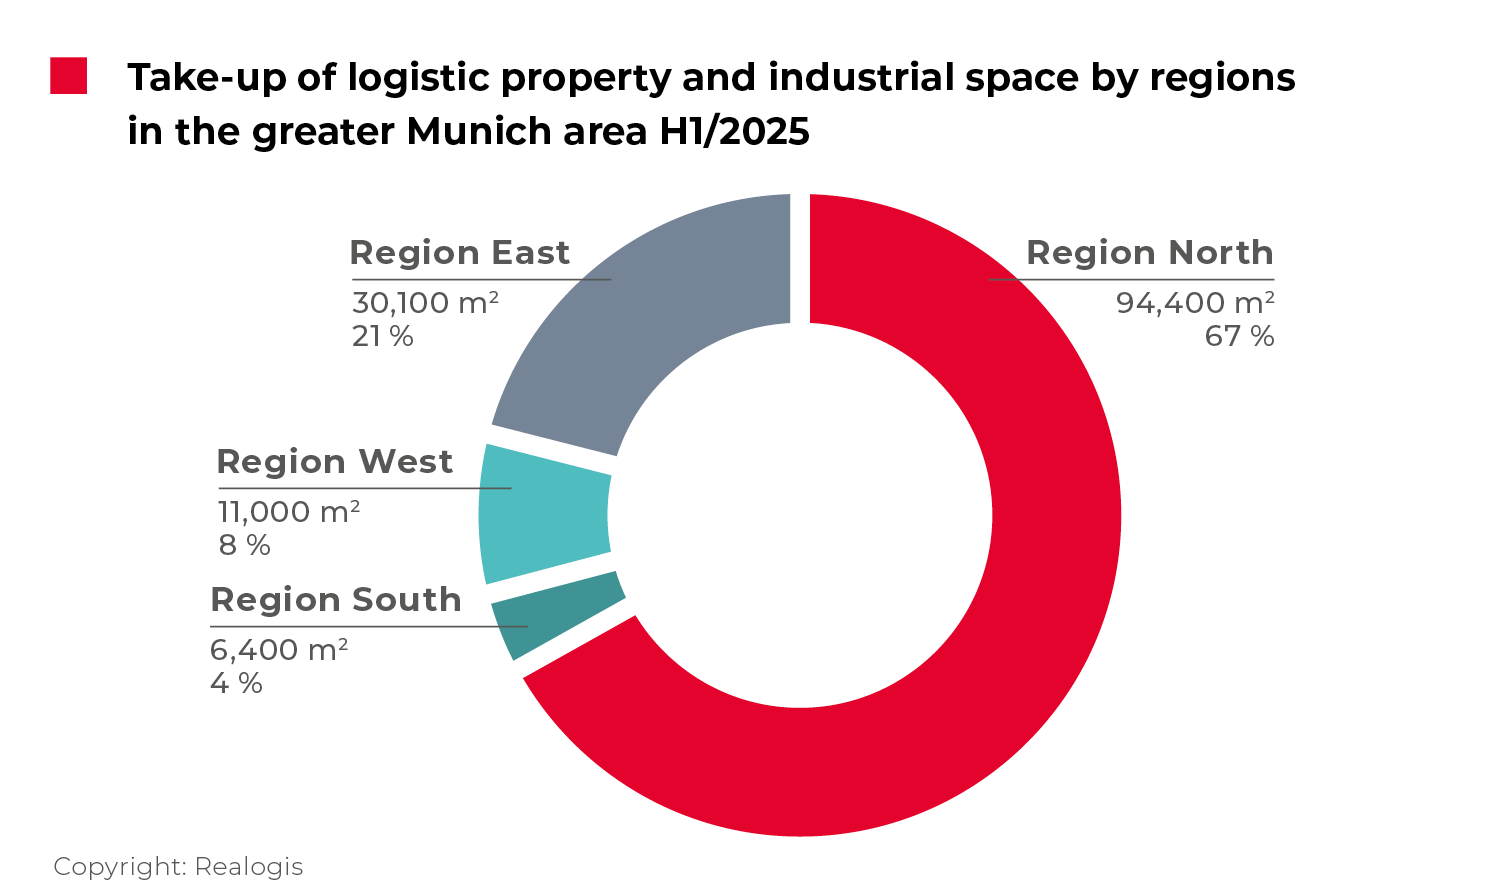
Logistics and industrial space was most in demand in the north of Munich with 94,400 m² or two out of three square metres taken up in the overall market (or 67%). Compared to the previous year's result of 35,900 m², this represents a more than doubling or a significant increase of 58,500 m².
"The dominance of the northern Munich Region in the first half of 2025 is above average and tops the average take-up of the last five comparable periods by a significant 49 %," reports Nicolas Werner.
The four largest deals in the first half of the year made an important contribution: REPA (32,600 m²), a manufacturing company (10,930 m²), a logistics company (10,830 m²) and a public sector deal (9,000 m²) accumulated 63,360 m² or two thirds of the take-up in the North region.
The previously top-ranked East region dropped one place and fell by 38,300 m² or 34 % compared to the same period of the previous year to currently 30,100 m² or 21 % (H1 2024: 68,400 m² or 56 %). Of all significant new rental agreements, only one retail company with 8,700 m² is located in this market area. Munich West remains in third place with 11,000 m² or 8 %, following a sideways movement with moderate growth of 900 m², up from 10,100 m² or 8 %. The Munich South region remains in last place with 6,400 m² or 4 %, down from 8,600 m² or 7 % (-2,200 m² or -26 %).
Sector ranking: Retail/Wholesale replaces Manufacturing as the largest sector of tenants
Coming from second place, the Retail/Wholesale sector is currently the largest sector of space take-up with 57,700 m² or a 41% share of total take-up and recorded growth of 26,800 m² or 87 % (H1 2024: 30,900 m² or 25 %). The 5-year average for the sector, which currently stands at 33,800 m², was exceeded by 71 %.
All of the take-up observed in Retail/Wholesale in the first six months was accounted for exclusively by companies in the "traditional retail" sub-category (H1 2024: 26,500 m²), which more than doubled its 5-year average of 24,640 m². No transactions by companies in the e-commerce sub-category have currently been observed. The take-up by REPA (32,600 m²) and a retail company (8,700 m²) accounted for a total of 41,300 m² or 72 % or almost three quarters of the take-up in the retail sector.
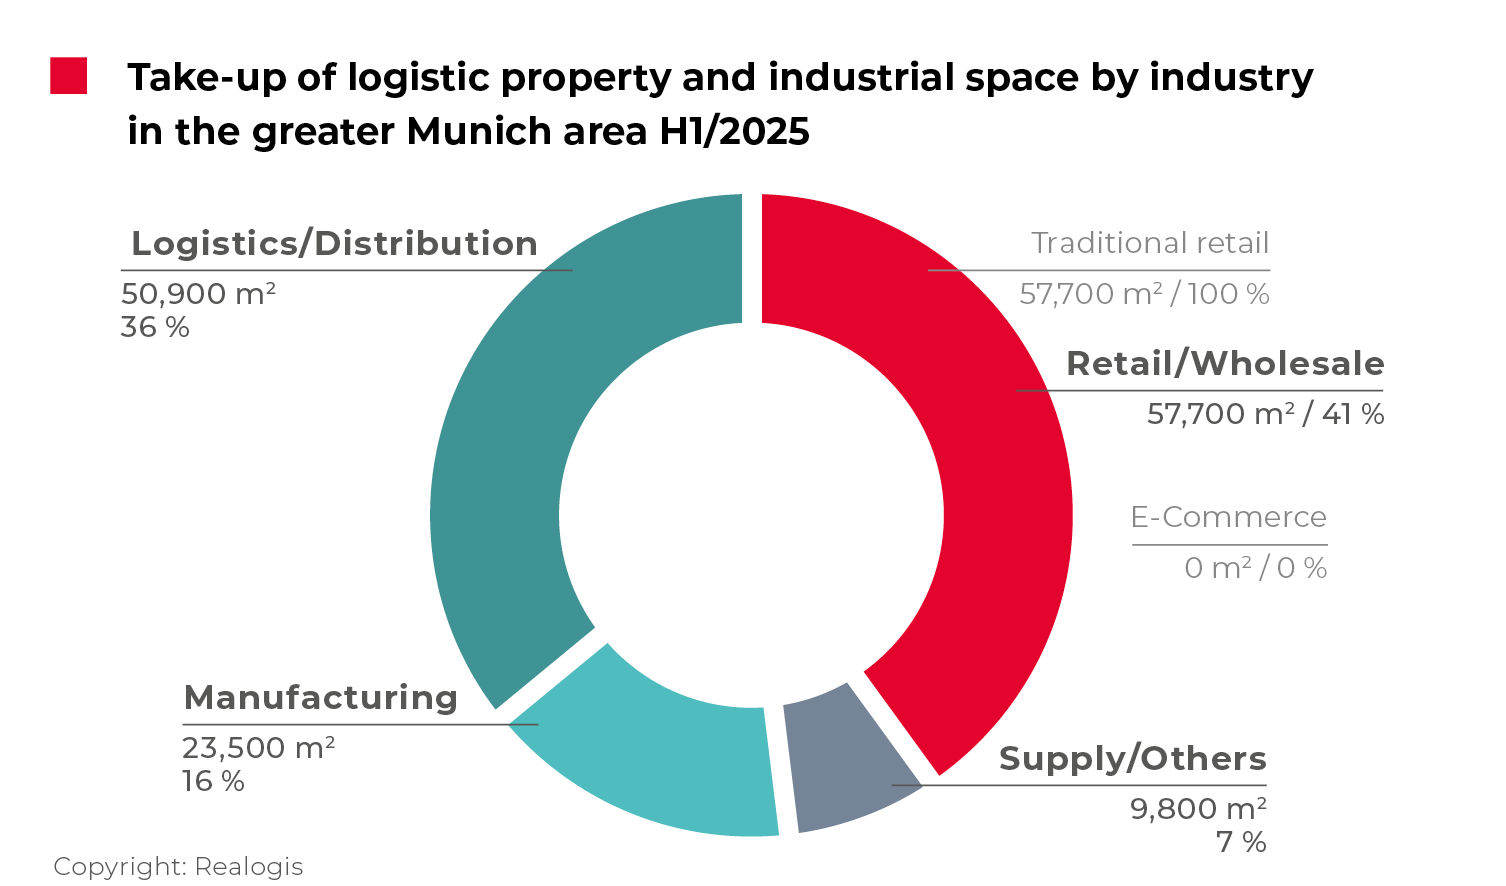
In second place in the sector ranking is Logistics/Distribution with 50,900 m² or 36 %. Coming in third place with 18,500 m² or 15 %, this sector recorded the most significant increase in take-up of all sectors, totalling 32,400 m², which is more than double the previous year's figure. Here, too, a clearly above-average half-year result can be attested: The 5-year average of 35,200 m² was exceeded by 45 %. A major deal by an unnamed logistics company for 10,830 m² contributed 21 %.
The penultimate place was taken by Manufacturing with 23,500 m² or 16 %, which fell short of the first place in the first half of the previous year with 58,400 m² by a clear 34,900 m² or 60 % and the current 5-year average of 48,540 m² by 52 %. The second largest take-up in the first half of the year was contributed by an unnamed manufacturing company with 10,930 m².
The sector category "Other" continues to be in last place with 9,800 m² or 7 %, down from 15,200 m² or 13 %. A public sector contract accounted for the lion's share here with 9,000 m² or 92 %.
Ranking of the size categories: Large spaces with 40 % increase in take-up
With 54,400 m² or 38 % of total take-up, the largest takers were units of 10,001 m² or more (H1 2024: 56,000 m², 45 % or a decrease of 3 %). They therefore exceed their 5-year average of 38,720 m² in the first half of the year by 40 %.
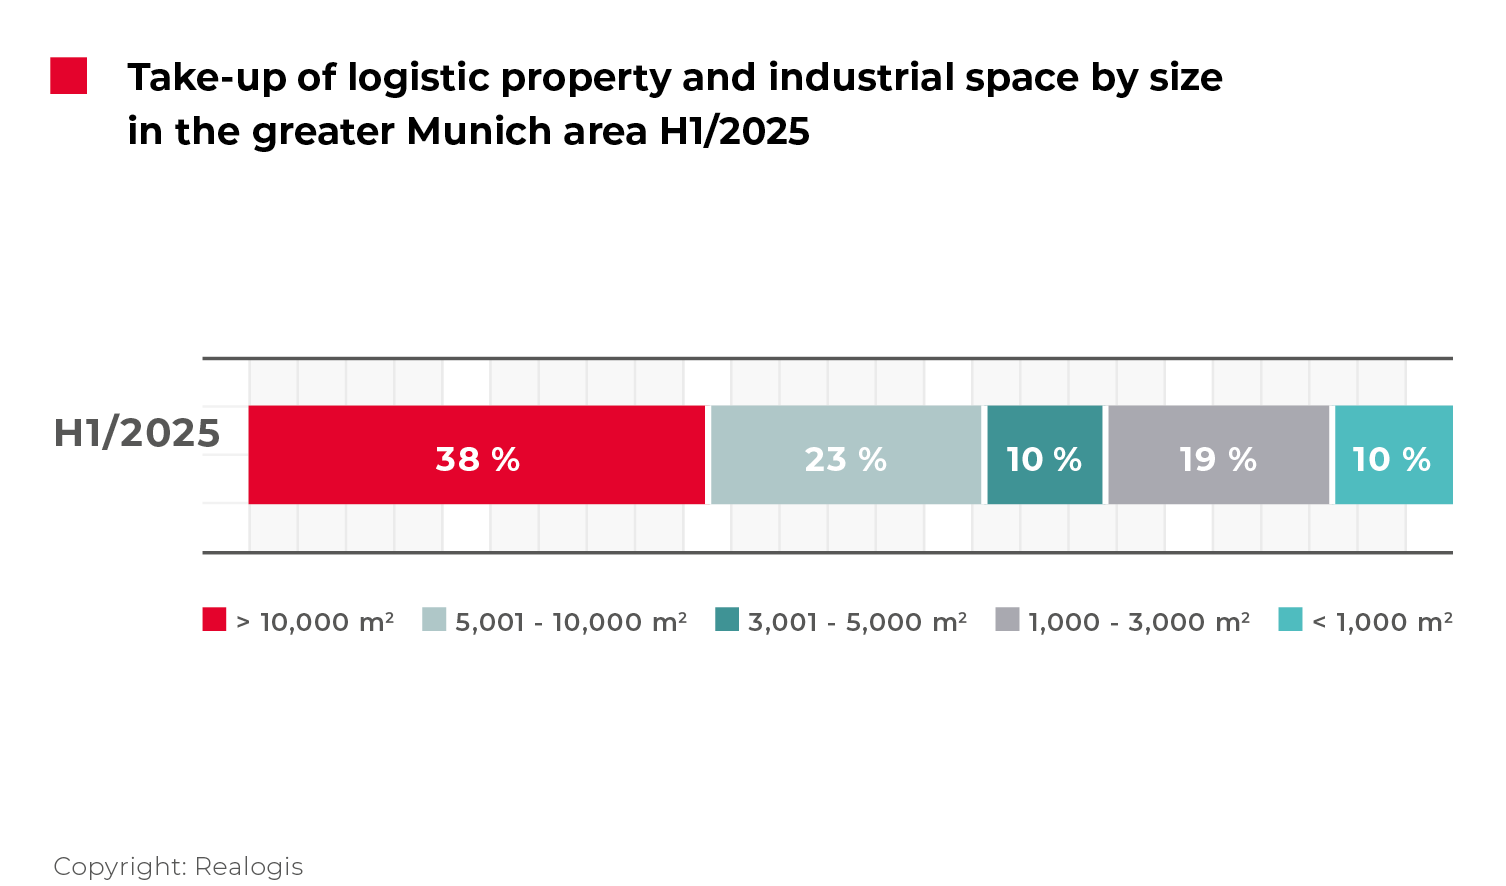
The next smallest category, i.e. units between 5,001 and 10,000 m², account for 32,000 m² or 23 % (H1 2024: 17,200 m² or 14 %). Space between 3,001 and 5,000 m² recorded take-up of 14,400 m² or 10 % in the past six months (H1 2024: 9,500 m² or 8 %). The category between 1,000 and 3,000 m² is currently at 26,800 m² or 19 % (coming from 30,700 m² or 25 %) and micro-space under 1,000 m² ranks at 14,300 m² or 10 %.
New record: prime rent increases by 29 % to €13.50/m²
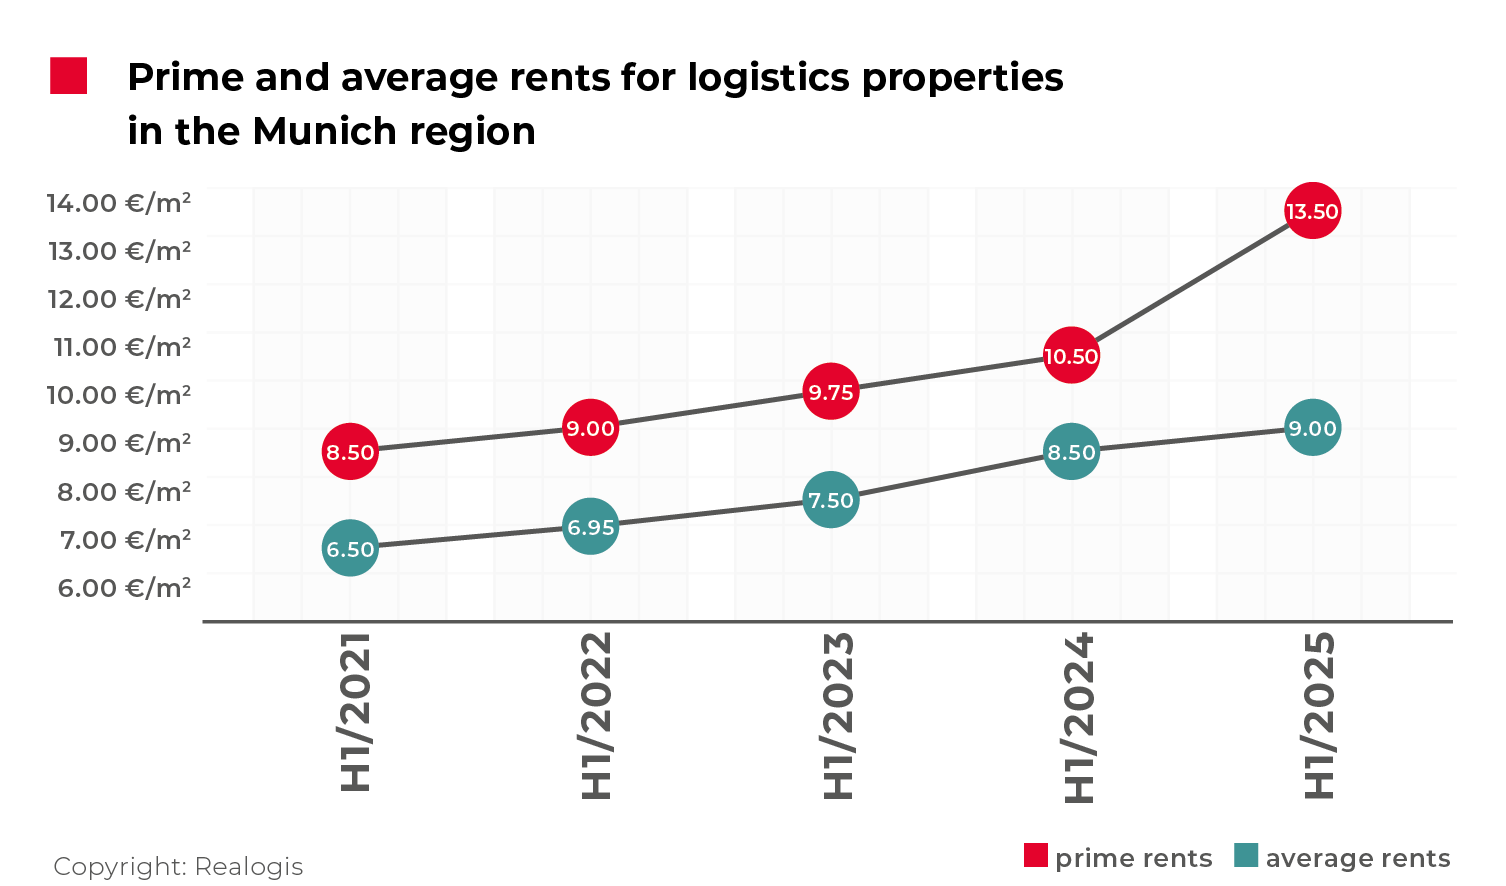
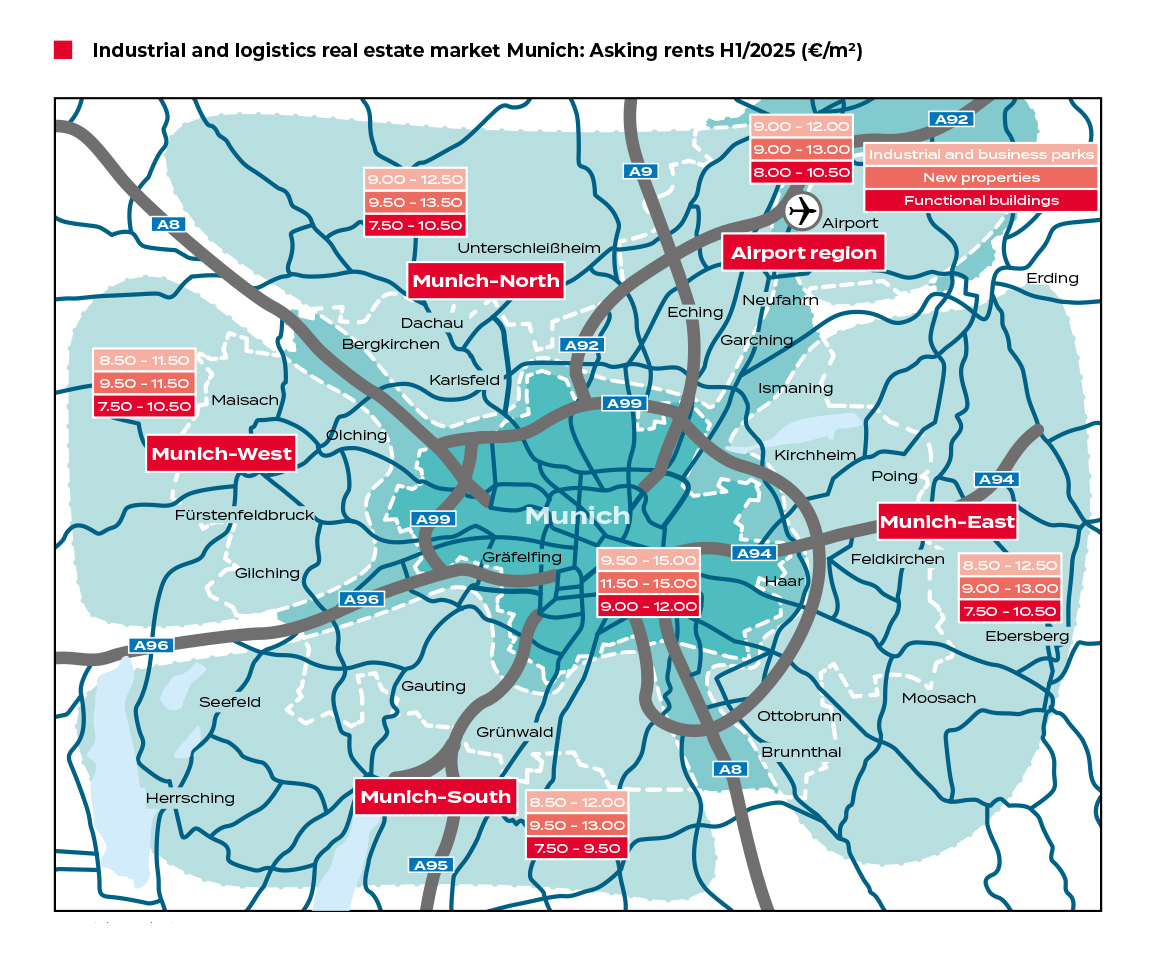
Compared to the first half of 2024, the prime rent has reached a new provisional high of €13.50/m², a significant increase of 29 %. Coming from € 10.50/m² in the first half of 2024, this represents an increase of € 3/m². The average of the last five first half-years of € 10.25/m² was exceeded by 32 %.
"Due to the increasing last-mile-delivery to end consumers, the take-up of space in last mile properties in the city centre is increasing. This is accompanied by an adjustment in prime rents, which is also due to the high land prices," says Nicolas Werner.
The average rent also developed dynamically, but less significantly than the prime rent. With an increase of 6 %, it currently stands at €9/m², up from €8.50/m², and thus around 17 % above the 5-year average of €7.69/m².
Outlook
"We expect a further take-up of around 100,000 m² in new-build and existing properties in the second half of the year and thus a total annual take-up of 240,000 m². Some of the demand will come from companies in the defence and infrastructure sectors," forecasts Nicolas Werner.
Press contact REALOGIS:
SH/Communication - Agency for Public Relations
Silke Westermann
Tel: +49/211/53 88 3-440
E-mail: s.westermann@shcommunication.de
Company contact REALOGIS:
REALOGIS Holding GmbH
Silja Schuppler
Marketing Manager
Leopoldstraße 154, 80804 Munich
Phone: +49/89/51 55 69 17
E-mail: s.schuppler@realogis.de
www.realogis.de
REALOGIS. The No. 1 for industrial and logistics properties
The REALOGIS Group is Germany's leading address for consulting and brokerage services for industrial and logistics properties and commercial land and has a 20-year track record of success. Founded in 2005, the owner-managed, organically grown and crisis-proof group of companies knows the German market like no other.
In the 2023 financial year, Realogis' audited net commission income across all services totalled around 15.76 million euros. In the lettings segment alone, the group achieved take-up of 982,232 m² in 2023, which corresponds to 16.5% of the total take-up of all market participants in Germany in that year and also represents a doubling of Realogis' market share since 2016.
Around 70 property professionals provide advice and support to national and international companies from the logistics, e-commerce, retail and industrial sectors as well as private and institutional investors. Fast, flexible, regional and customer-orientated. The group has eight branches in Berlin, Düsseldorf, Germany South/North, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart.
Its four core competences include finding tenants with strong credit ratings for existing and new-build properties, supporting investors in property investments and in the development of greenfield and brownfield projects, providing a perfect service for property searches and sales and developing and implementing holistic property strategies. This covers the entire property cycle - from location analysis and optimisation of expansion targets to the sale of assets that are no longer required for operations.
In short: REALOGIS offers "More space for your success" in every respect.