
Unfortunately, there are no properties on your watch list.
Do you have a question? Leave your contact details here and we will call you back!

Press Release
Frankfurt region: REALOGIS analyses the market for logistics and industrial properties in the first half of 2025
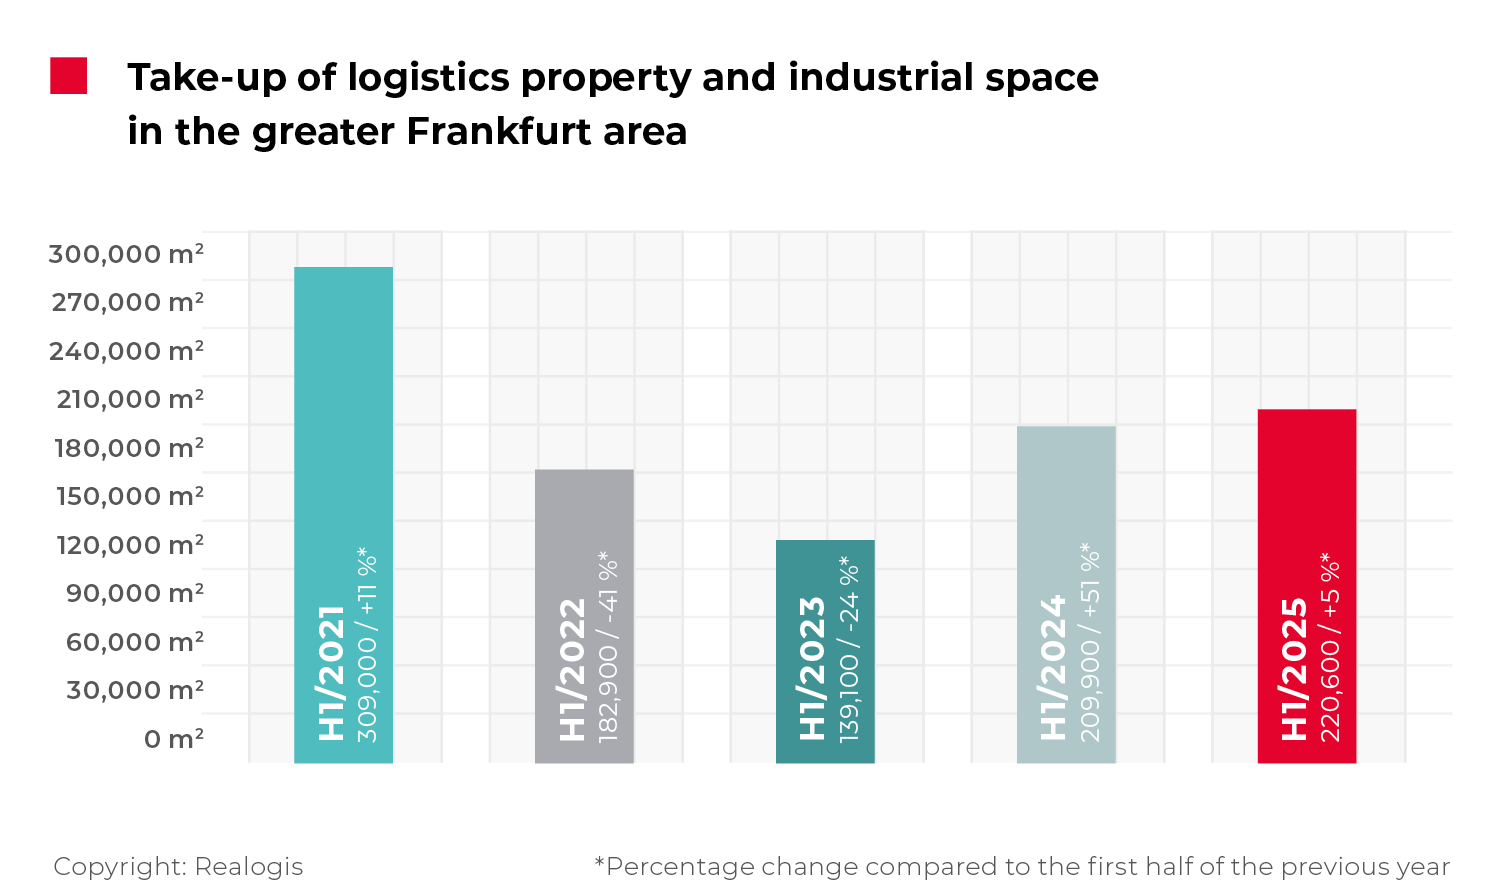
- Slight increase in take-up: +5 %
- 5-year average exceeded: +4 %
- Transactions in existing properties dominate 70 % of market activity
- Greenfields and brownfields decline significantly
- Subletting remains relevant to the market
- Regional ranking: Rhine-Main-South accounts for two thirds of total take-up
- Sector ranking: Logistics/forwarding and retail at a similar level
- Space units between 5,001 and 10,000 m² increase by 58 % to 1st place
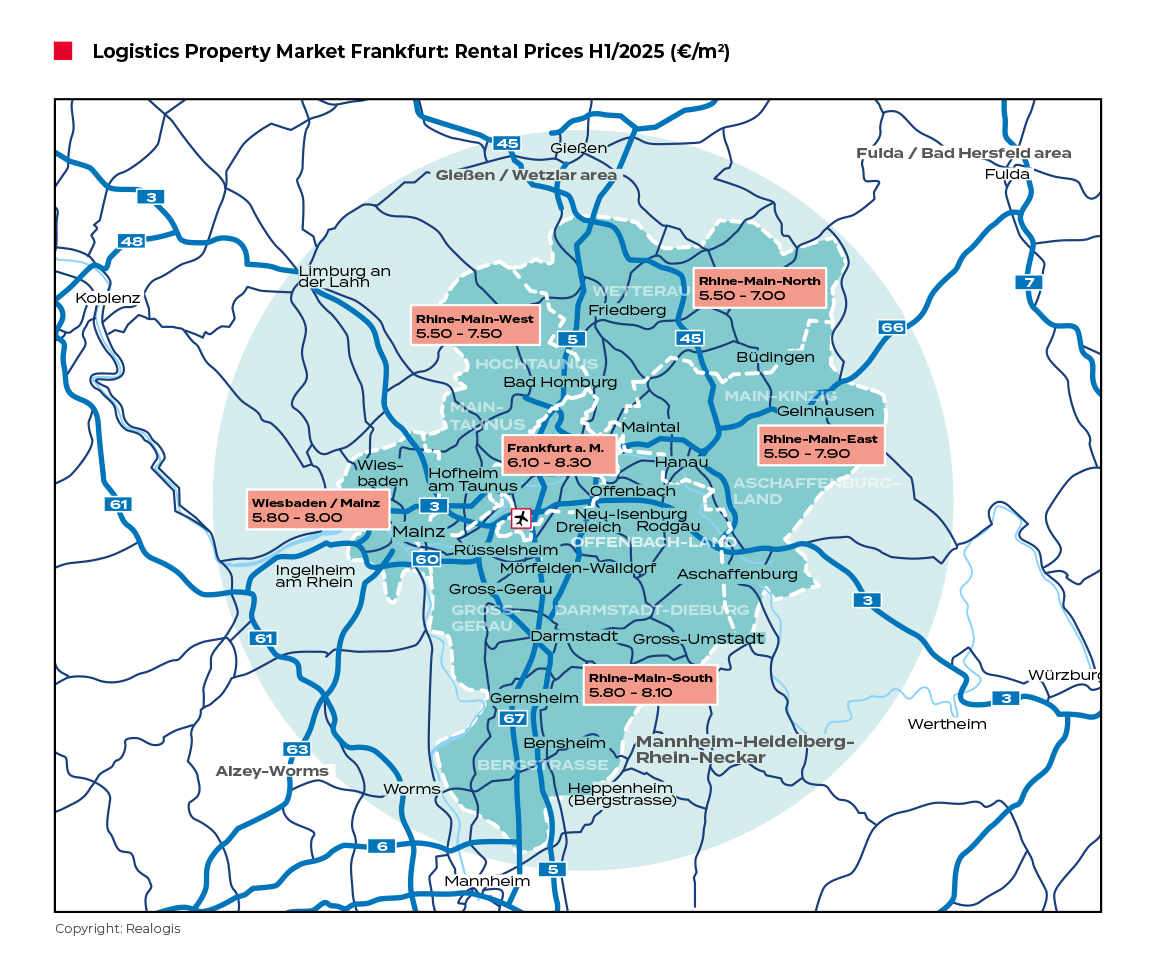
- Prime rent: slight increase of 5 % to €8.30/m²
- Outlook: The market is on the move - the full-year result will be slightly higher than the previous year
"As in the football business, contracts in the logistics property sector can also be terminate prematurely. Due to the prematurely released space, several more contracts were signed in the first six months than expected at the beginning of the year," comments Julian Petri, Managing Director of Realogis Immobilien Frankfurt GmbH.
Existing properties dominated the market with a share of 70 % or 155,400 m². Coming from just 19 % or 40,200 m², their take-up has more than tripled. Over the last five years, this is the highest figure observed for transactions in existing properties on the Frankfurt market. The major deals by Pirelli and the Adam Hall Group together accounted for 23,500 m² or just 15 % of take-up.
New-build properties on greenfield sites followed with 24% or 53,100 m², coming from 122,600 m² or 58 %. According to Realogis, this result marks the sharpest decline of all categories by 69,500 m² and is equivalent to more than a halving (-57 %). Alnatura and Sinotrans Air Transportation were the biggest takers of space with a total of 35,900 m² and 68 % respectively.
Lettings in new-build properties on former brownfield sites continue to rank last with 12,100 m² or 5 % (H1 2024: 47,100 or 22 %). They also fell significantly by 35,000 m², meaning that only around a quarter of the previous year's level has been reached. DB Schenker accounted for a significant share of the take-up with 9,540 m² or 79 %.
"The delta in new builds in the first half of 2025 - i.e. both on greenfield sites and on former brownfield sites - was more than offset by new contracts for existing space," says Julian Petri.
Key revenue drivers
Company | Market area | Take-up of space | Type | Sector |
Alnatura | Rhine-Main-South | 27,200 m² | New building (greenfield) | Retail/Wholesale (classic) |
Pirelli Deutschland GmbH | Rhine-Main-South | 14,000 m² | Existing building | Retail/Wholesale (classic) |
DB Schenker | Rhine-Main-South | 9,540 m² | New building (brownfield) | Logistics/Distribution |
Adam Hall Group | Rhine-Main-North | 9,500 m² | Existing building | Manufacturing |
Sinotrans Air Transportation GmbH | Rhine-Main-South | 8,700 m² | New building (greenfield site) | Logistics/ Distribution |
"The user side is more interested in tenancies and is reluctant to build owner-occupied properties. As in the same period of the previous year, transactions by tenants exceed those by owner-occupiers, albeit with increasing clarity," reports Julian Petri.
In the differentiation between tenants and owner-occupiers, the Frankfurt region was an almost pure rental market at 98 % or 215,600 m². In the same period of the previous year, 34,100 m² or 16 % were owner-occupier transactions.
In terms of building type, big box properties remained largely stable, while business parks and other properties almost swapped take-up. Accordingly, deals in business parks were the most sought-after properties in the first half of the year with 90,400 m² or 41 % (H1 2024: 3rd place with 52,600 m² or 25 %). Their growth was significant at +37,800 m² or +72 %.
Big-box properties remain in second place with 72,200 m² or 33 %, showing almost a sideways movement (H1 2024: 70,300 m² or 34 %).
The previously top-ranked other properties dropped to last place with 58,000 m² or 26 % (H1 2024: 87,000 m² or 41 %) and were the only building type to record a decline with -29,000 m² or -33 %.
Subletting remained stable at around 17 % or 36,800 m² (H1 2024: 17 % or 36,700 m²), almost identical to the same period of the previous year.
Regional ranking: Rhine-Main South accounts for two thirds of total take-up
Rhine-Main South remains the region with the highest take-up of warehouse and industrial space for rent in the first half of the year. With 149,100 m² or two-thirds of total take-up (67%), it achieved the most significant growth of all regions with 45,100 m² or +43% (H1 2024: 104,000 m² or 49 %). Four of the five largest contracts signed in the first half of the year including the two largest contracts signed by Alnatura in a project development currently under construction by Aurelis and Pirelli Deutschland - contributed a total of 59,440 m² or 40 %.
Rhine-Main North was once again in second place with 24,600 m² or 11 %. However, take-up in the region slumped by a significant 27,500 m², which is equivalent to a halving (-53 %). However, according to the 5-year average, take-up in the same period last year was well above the typical level for the region. The major take-up by the Adam Hall Group contributed to the current result with 9,500 m² or 39 %.
The Frankfurt city area follows in third place with 19,600 m² or 9 %, coming from fourth place with 4,700 m² or 2 % in the same period of the previous year (+14,900 m² or +317 %).
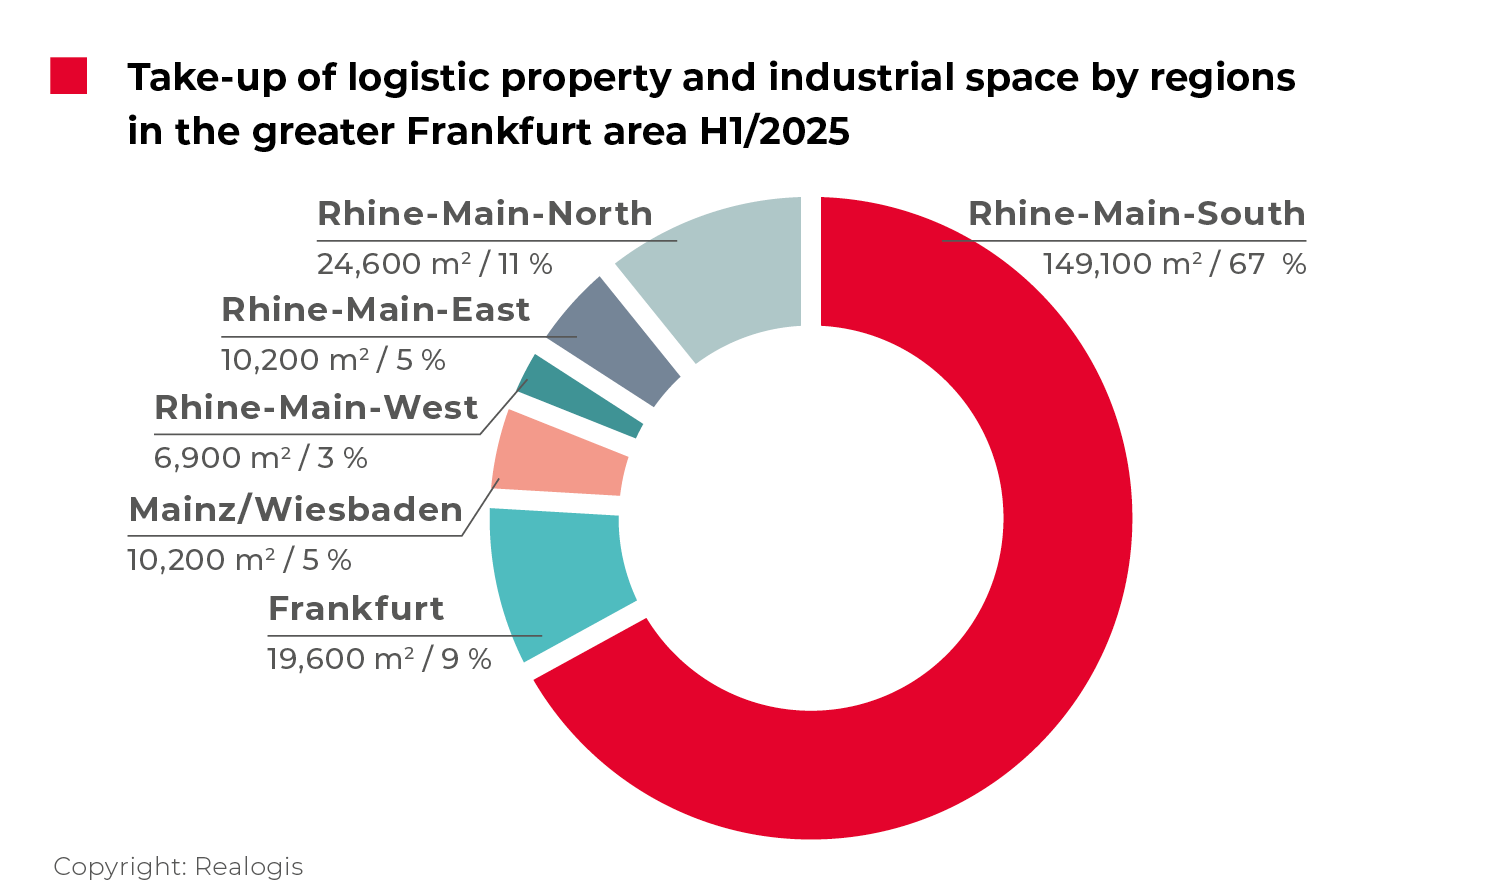
Rhine-Main East is in fourth place with 10,200 m² or 5 % together with Mainz/Wiesbaden (also 10,200 m² or 5 %). For this region, this represents a drop of one rank: coming from 43,600 m² or 21 %, the largest drop in take-up of all regions is -33,400 m² (-77 %). For Mainz/Wiesbaden, fourth place means a rise of one place, coming from 3,300 m² or 2 % (+6,900 m² or more than tripling). Rhine-Main West remains in last place with 6,900 m² or 3 %, up from 2,200 m² or 1 % (+4,700 m² or also more than tripled).
"With the exception of the Rhine-Main East region - whose average take-up was 51,800 m², a significant 80% shortfall - all submarkets exceeded their respective 5-year averages," reports Julian Petri. "All other regions exceeded their respective figures by at least 10 %, with the Frankfurt city area outperforming its average for the last five first half-years by 43 %."
Sector ranking: Logistics/Distribution and retail at a similar level
Both key sectors recorded similar levels of take-up from January to June 2025. At 78,000 m² or 35 %, the Logistics/Distribution sector is in the lead (H1 2024: 99,100 m² or 47 %). However, it fell by -21,100 m² or -21% compared to the previous year and is the only sector to fall short of its 5-year average (-15 %). The largest deals were signed by DB Schenker and Sinotrans Air Transportation, which contributed a total of 18,240 m² or 23 % of the sector's overall result.
This was followed only just behind by the previously third-placed Retail/Wholesale sector with 77,600 m² or 35 %, coming from 28,900 m² or 14 %. It increased by a significant 48,700 m² compared to the previous year, which is more than double the previous year's take-up. Half of this is attributable to lettings by Alnatura and Pirelli, totaling 41,200 m² or just over half of take-up in the retail sector (53%). The 5-year average was exceeded by 24,660 m² or 6 %, after the previous year's typical level was missed by a significant 68%.
The lion's share was once again contributed by the "traditional retail" sub-category with 73,500 m² or 95 %, which increased by +46,800 m² compared to the same period of the previous year and thus almost tripled (H1 2024: 26,700 m² or 92 %). By contrast, companies focusing on "e-commerce" only took up 4,100 m² or 5 % of space, up from 2,200 m² or 8 % (+1,900 m² or almost double).
Within the Retail/Wholesale sector, the take-up of space in traditional retail is significantly 61 % above the typical level (average of the last five first half-years), while the total take-up of e-commerce is below average (falls short of the average by 66 %).
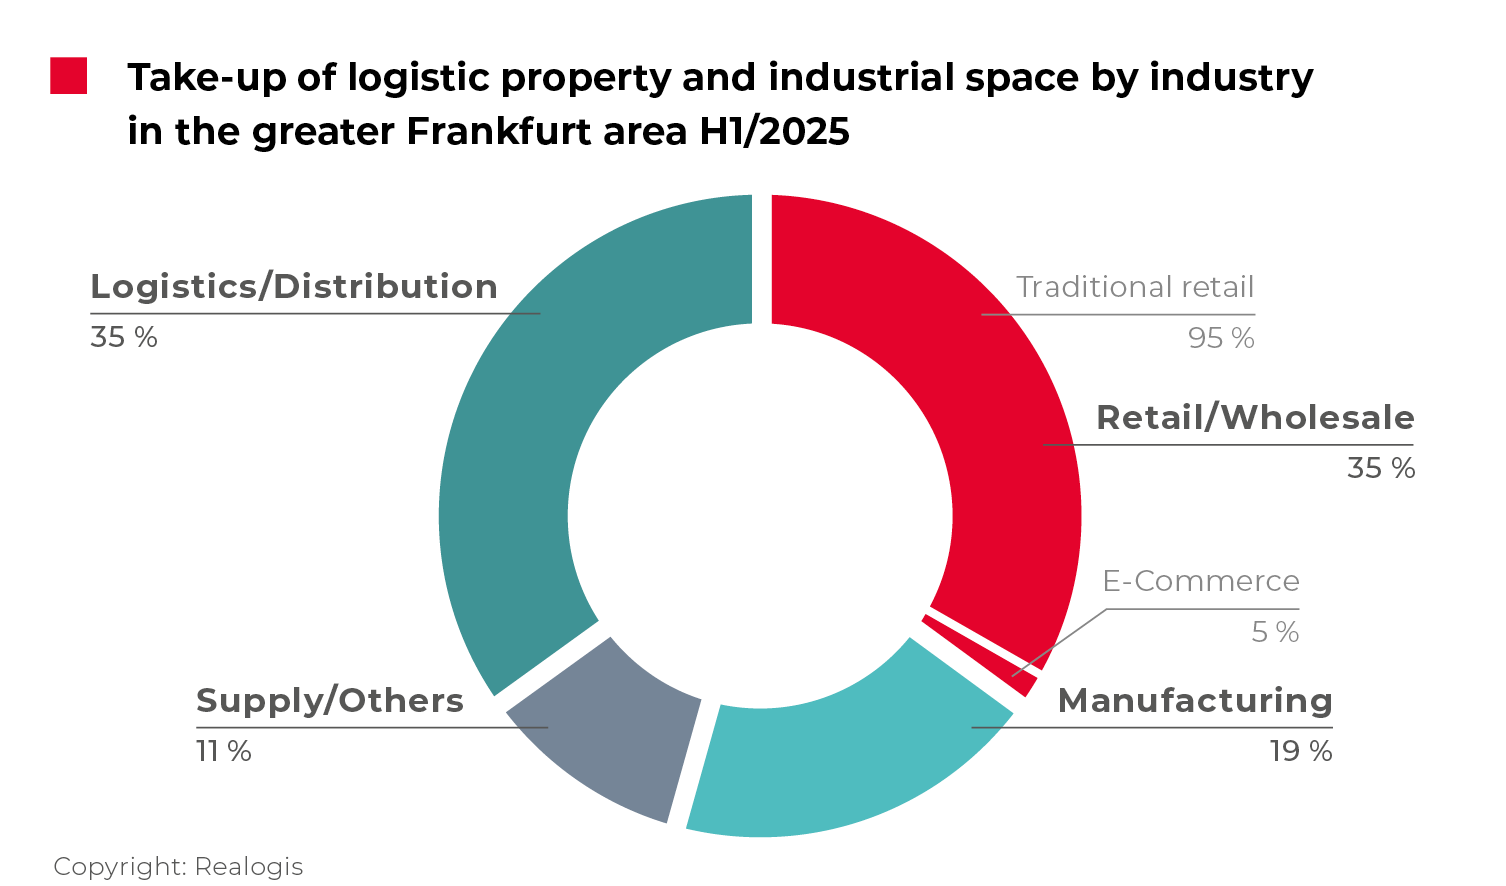
In third place is the industry Manufacturing with 41,500 m² or 19 %, followed by 66,900 m² or 32 %. Although this is the clearest delta in the comparison of 25,400 m² or 38 % in the first half of 2024, it still represents an above-average result, as the 5-year average was exceeded by 31 %. Just under a quarter of the take-up (23%) is attributable to the 9,500 m² signed by the Adam Hall Group.
The last place was once again taken by the collective category "Other" with 23,500 m² or 11%, coming from 15,000 m² or 7% (growth of 8,500 m² or +57%).
Space units between 5,001 and 10,000 m² increase by 58 % to 1st place
The size category of large units of 10,001 m² or more accounted for a total of 41,200 m² or 19 % (3rd place) in the past six months. Coming from first place with 71,000 m² or 34 %, the most significant delta of all size categories is 29,800 m² or -42 %. In addition to the smallest spaces, the category of the largest spaces also fell well short of the average of the last 5 years by 41 %. The deals concluded by Alnatura and Pirelli were solely responsible for the take-up of 41,200 m².
The previously second-placed category between 5,001 and 10,000 m² climbed to the top spot and, with a result of 92,100 m² or 42 %, saw the most significant increase of all space units with +33,700 m² or +58 %. It not only exceeds the previous year's result of 58,400 m² or 28 %, but is also a significant 52 % above the average of the last five first half-years. The agreements concluded by DB Schenker, the Adam Hall Group and Sinotrans Air Transportation accounted for a total of 30 % (or 27,740 m²).
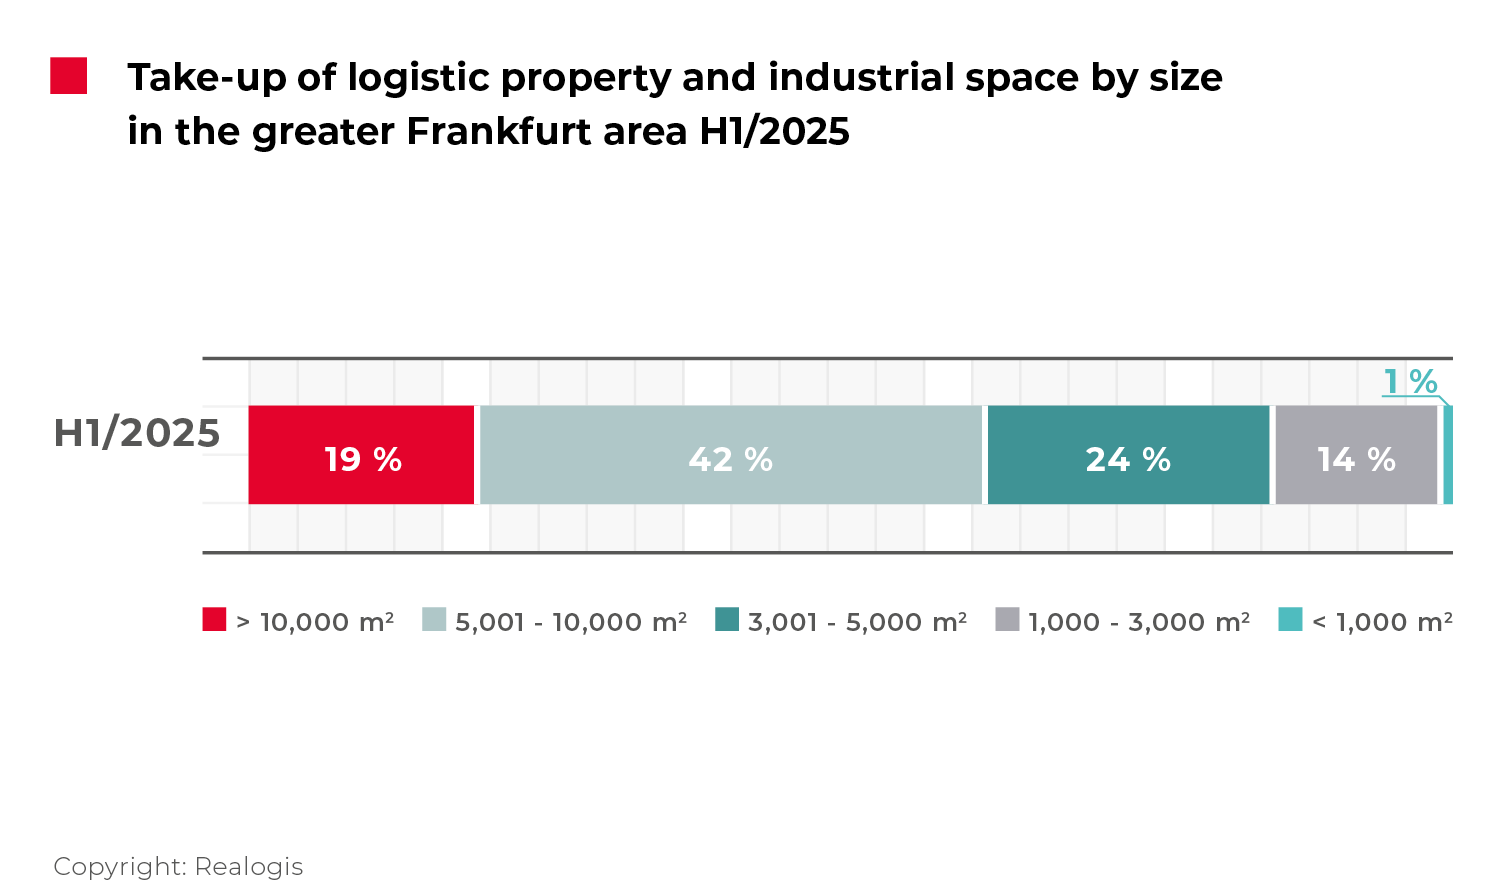
Space units between 3,001 and 5,000 m² moved up one place to second place with 53,400 m² or 24 % (H1 2024: 48,550 m² or 23 %).
Smaller spaces between 1,000 and 3,000 m² are still in penultimate place with 31,500 m² or 14 %, up from 24,750 m² or 12 %. Micro-space of less than 1,000 m² remains in last place with 2,400 m² or 1 %, down from 7,200 m² or 3 %.
Prime rents increase by 5%
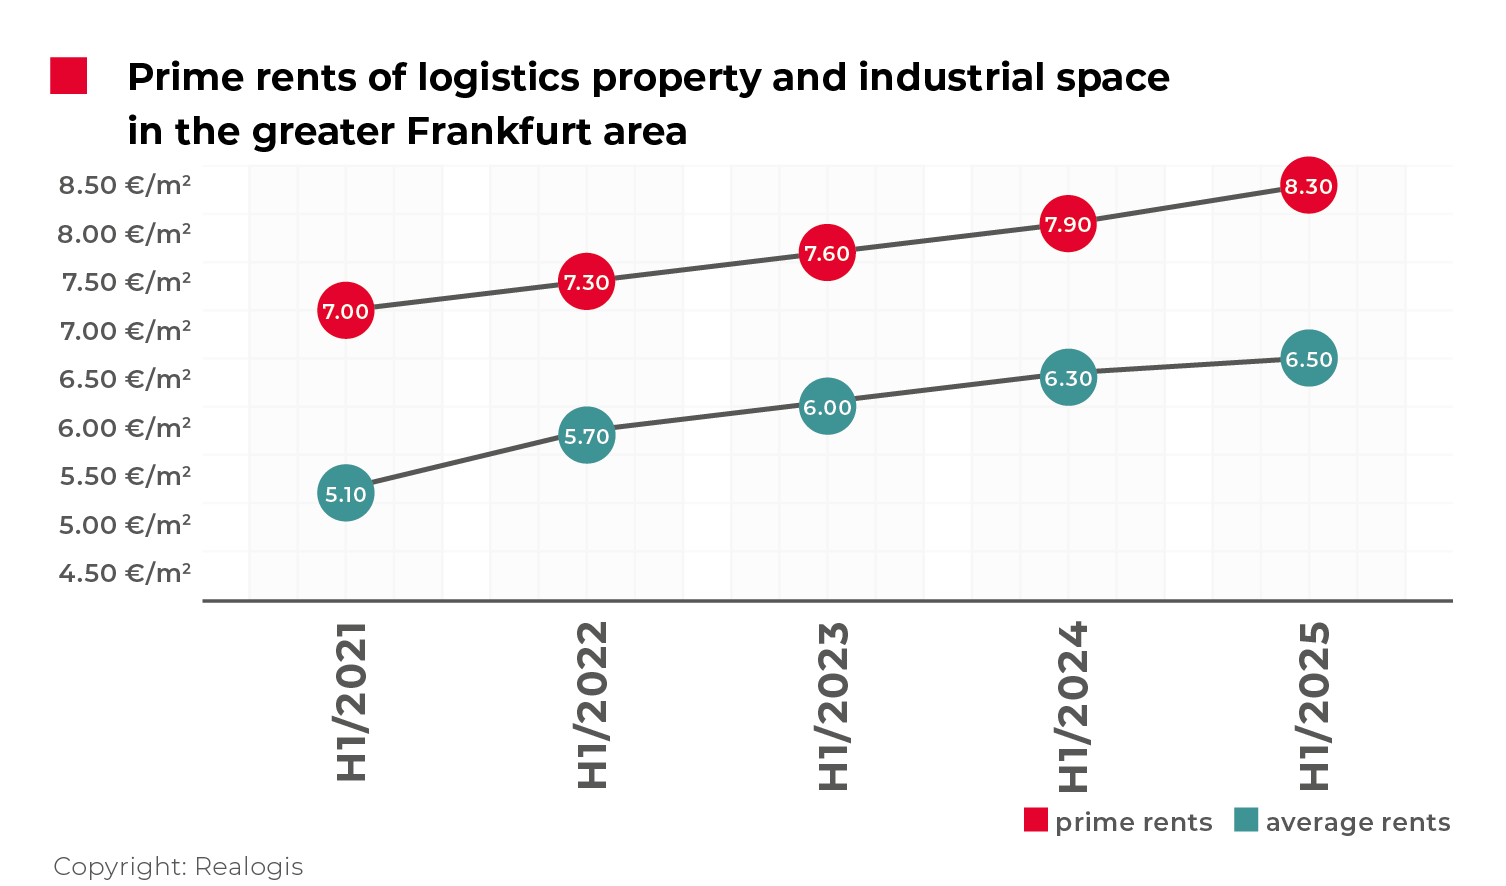
Prime rents reached their provisional peak at €8.30/m², up from €7.90/m² in the same period of the previous year, which corresponds to an increase of 5 % and continues the rising price trend of the same period of the previous year. The 5-year average of €7.62 /m² was exceeded by 9 %.
The average rent developed slightly dynamically and rose by 3 % to €6.50/m², up from €6.30/m² in the same period of the previous year. However, the 5-year average of €5.92/m² was exceeded by 10 %.
Outlook
"The market is moving. The retail sector in particular is still very strong as a buyer of space. This is a good signal for both portfolio holders and project developers of new-build properties. As always, we expect the Frankfurt market for logistics and industrial space to pick up more strongly in the second half of the year. We expect the full-year result for 2025 to be slightly above last year's figure of 423,300 m²," explains Julian Petri.
Press contact REALOGIS:
SH/Communication - Agency for Public Relations
Silke Westermann
Tel: +49/211/53 88 3-440
E-mail: s.westermann@shcommunication.de
Company contact REALOGIS:
REALOGIS Holding GmbH
Silja Schuppler
Marketing Manager
Leopoldstraße 154, 80804 Munich
Phone: +49/89/51 55 69 17
E-mail: s.schuppler@realogis.de
www.realogis.de
REALOGIS. The No. 1 for industrial and logistics properties
The REALOGIS Group is Germany's leading address for consulting and brokerage services for industrial and logistics properties and commercial land and has a 20-year track record of success. Founded in 2005, the owner-managed, organically grown and crisis-proof group of companies knows the German market like no other.
In the 2023 financial year, Realogis' audited net commission income across all services totalled around 15.76 million euros. In the lettings segment alone, the group achieved take-up of 982,232 m² in 2023, which corresponds to 16.5% of the total take-up of all market participants in Germany in that year and also represents a doubling of Realogis' market share since 2016.
Around 70 property professionals provide advice and support to national and international companies from the logistics, e-commerce, retail and industrial sectors as well as private and institutional investors. Fast, flexible, regional and customer-orientated. The group has eight branches in Berlin, Düsseldorf, Germany South/North, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart.
Its four core competences include finding tenants with strong credit ratings for existing and new-build properties, supporting investors in property investments and in the development of greenfield and brownfield projects, providing a perfect service for property searches and sales and developing and implementing holistic property strategies. This covers the entire property cycle - from location analysis and optimisation of expansion targets to the sale of assets that are no longer required for operations.
In short: REALOGIS offers "More space for your success" in every respect.