
Unfortunately, there are no properties on your watch list.
Do you have a question? Leave your contact details here and we will call you back!

Press Release
Düsseldorf region: REALOGIS analyses the market for logistics and industrial properties in the first half of 2024
- Take-up almost 17 % below the same period last year
- Sector ranking: Logistics/distribution clearly ahead, but almost halved compared to H1 2023
- Lack of large areas
- Prime rent with significant price increase
- Outlook: Shortage in the middle space segment from 2,000 to 7,000 m²
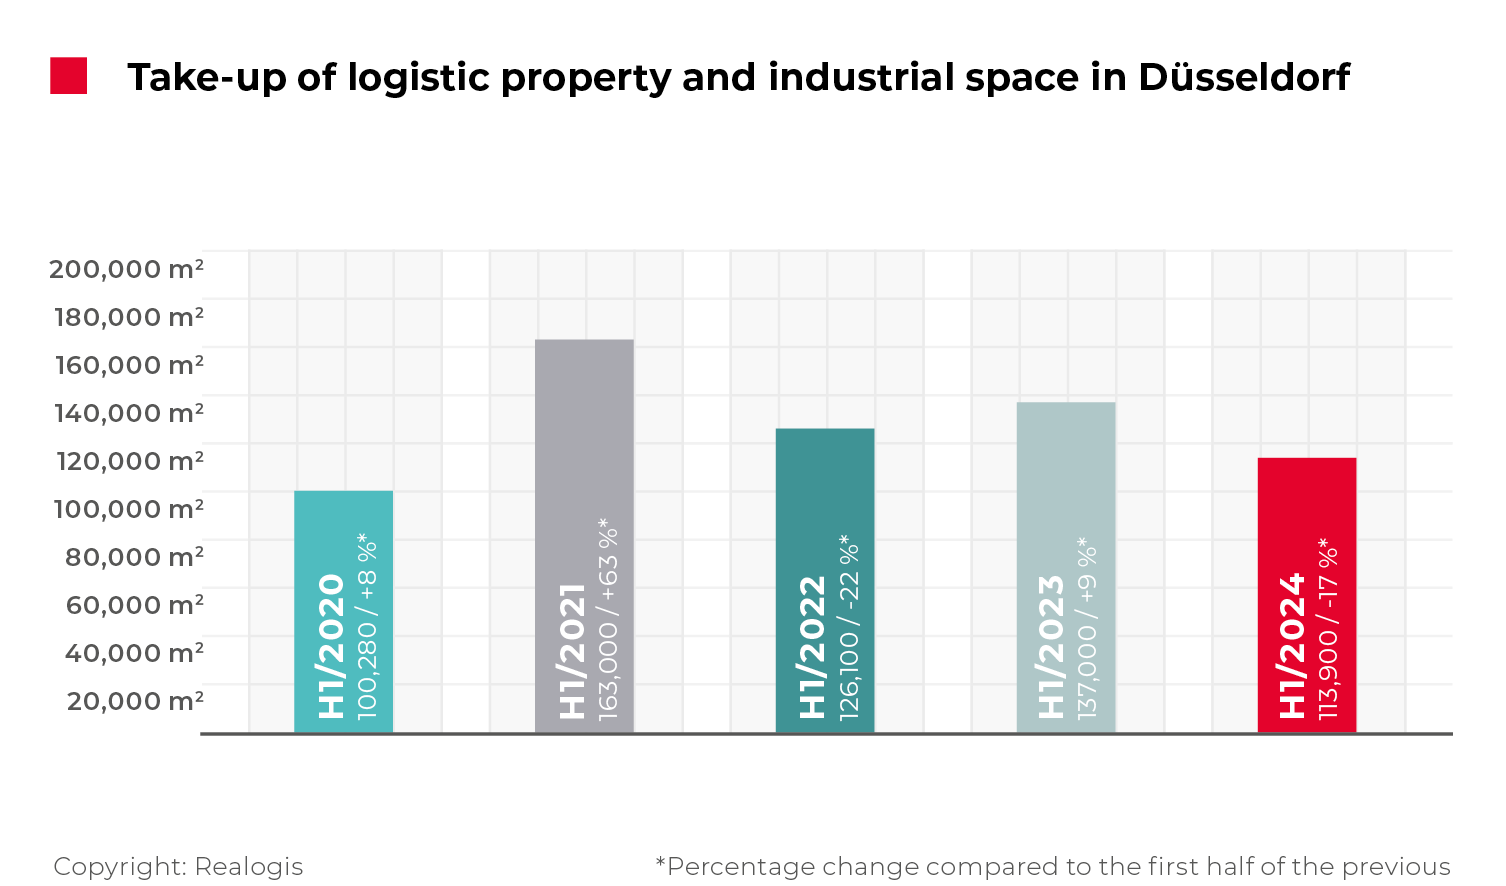
These and other results are provided in the latest market report by Realogis, Germany's leading consultancy for industrial and logistics properties and commercial plots.
Four out of five square metres were taken up in existing properties (93,450 m² or 82 %), which corresponds to an increase of 27,350 m² or 41.4 %. In contrast, take-up in new builds plummeted from 70,900 m² or 51.8 % in H1 2023 to 20,450 m² or 18 %, which is just over a fifth of the previous year's figure. Brownfield space continues to play no role on the Düsseldorf market.
As in the previous year, the Düsseldorf industrial and logistics property market is purely a letting market. Realogis did not register any owner-occupier transactions.
In contrast to the previous year, lettings in other properties, i.e. not big box properties or business parks, led the way in terms of building type with 46,260 m² or 40.6% (H1 2023: 23,580 m² or 17.2%), which is almost double the previous year's figure. Big box properties follow in second place, contributing 37,300 m² or 32.7 % to take-up and thus recording a significant decline of 68,850 m² or -64.9 %. Business parks once again brought up the rear with 30,340 m² or 26.6 %, more than quadrupling or increasing by 23,070 m² after 7,270 m² or 5.3 % in the same period of the previous year.
Sector ranking: Logistics/distribution clearly ahead, but almost halved compared to H1 2023
"The leading sector of rental space in the Düsseldorf industrial and logistics market is once again the logistics/distribution sector," comments Bülent Alemdag, Managing Director of Realogis Immobilien Düsseldorf GmbH.
58,200 m² or more than every second square metre (51.1%) is accounted for by this sector in the months from January to June 2024. It is also responsible for all of the top deals, which cumulatively account for 37,300 m² or 64.1% of take-up in the sector.
Key take-up drivers H1 2024
Company | Take-up | Type | Sector |
Goodcang Logistics | 17,500 m² | Existing building | Logistics |
Nelo GmbH | 10,000 m² | Existing building | Logistics |
Pharmaserv Logistics | 9,800 m² | New building | Logistics |
However, at -49,830 m² or -46.1 %, the take-up of 108,030 m² has also halved the most significantly of all sectors. The sector thus recorded the largest and only loss of importance compared to retail, manufacturing and other, with -27.8 percentage points of the share of total take-up. The 5-year average of 70,765 m² is currently being missed by a significant 17.8 %.
Retail is again in second place with 22,800 m² or 20 %, up from 18,280 m² or 13.3 %. Due to the slump in logistics/distribution, the sector was able to gain 6.7 percentage points in proportionate take-up, with absolute growth of 4,520 m² or 24.7 %. However, the 5-year average of 39,175 m² was missed by 41.8 %, meaning that take-up in the retail sector is still well below the sector average despite the growth. The e-commerce sub-category accounts for 65.8% or 15,000 m² (H1 2023: 13,230 m² or 72.4%), while traditional retail accounts for 7,800 m² or 34.2% (H1 2023: 5,050 m² or 27.6%).
The penultimate category is “supply/others” with 16,900 m² or 14.8%, which did not record any completions in the previous year. At the bottom of the ranking is the manufacturing sector with 16,000 m² or 14 %, coming from 10,690 m² or 7.8 % (+ 5,310 m² or +49.7 %), which thus exceeded the 5-year average of 11,712 m² by a clear 36.6 %.
Lack of large spaces
Large spaces of 10,001 m² or more recorded a slump from 87,560 m² or -83.3 % in absolute terms to 17,500 m² or just 15.4 % (H1 2023: 105,060 m² or 76.7 %). The take-up in this size category is attributable to the single take-up by Goodcang Logistics with 17,500 m².
The space segment between 5,001 and 10,000 m² rose by one place to 61,385 m² or 53.9% (H1 2023: 13,105 m² or 9.6%). "This size category thus recorded the most significant absolute growth of 48,280 m² or more than a fourfold increase. This is also the most significant increase of 44 percentage points in the proportion of take-up," says Bülent Alemdag.
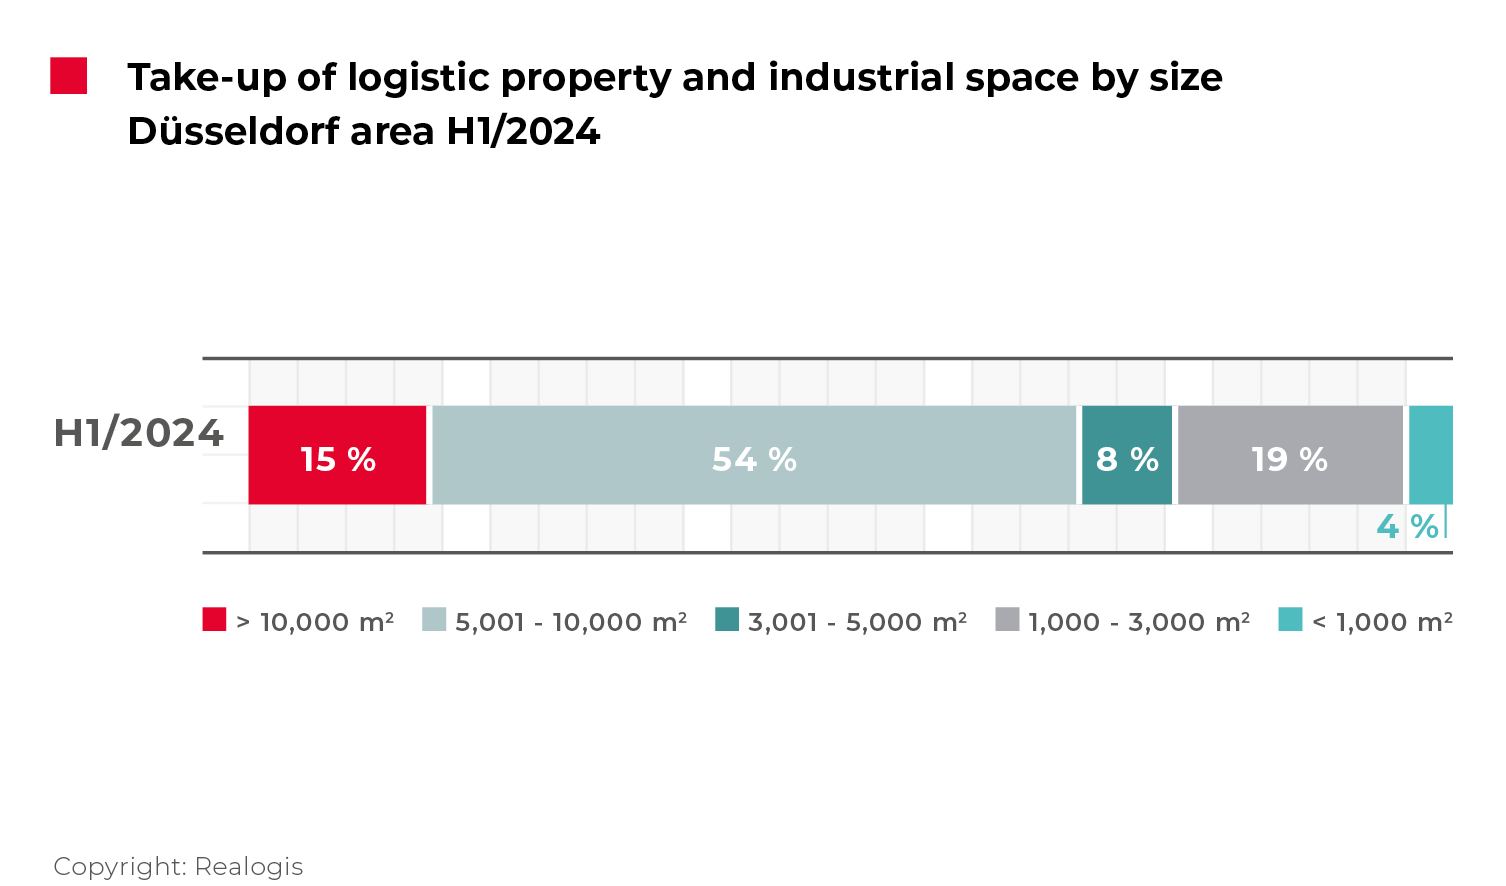
Units between 3,001 and 5,000 m² account for 9,200 m² or a share of 8.1 % and thus once again occupy fourth place (H1 2023: 4,465 m² or 3.3 %). Small to medium-sized spaces between 1,000 and 3,000 m² achieved the second-highest take-up in the past six months with 21,815 m² or 19.2 % (H1 2023: 12,275 m² or 9 %) and recorded growth of 9,540 m² or 77.7 %. At 4,000 m² or 3.5 %, micro spaces of less than 1,000 m² once again played a subordinate role in terms of take-up after 2,095 m² or 1.5 % in the first half of 2023.
Prime rent with significant price jump
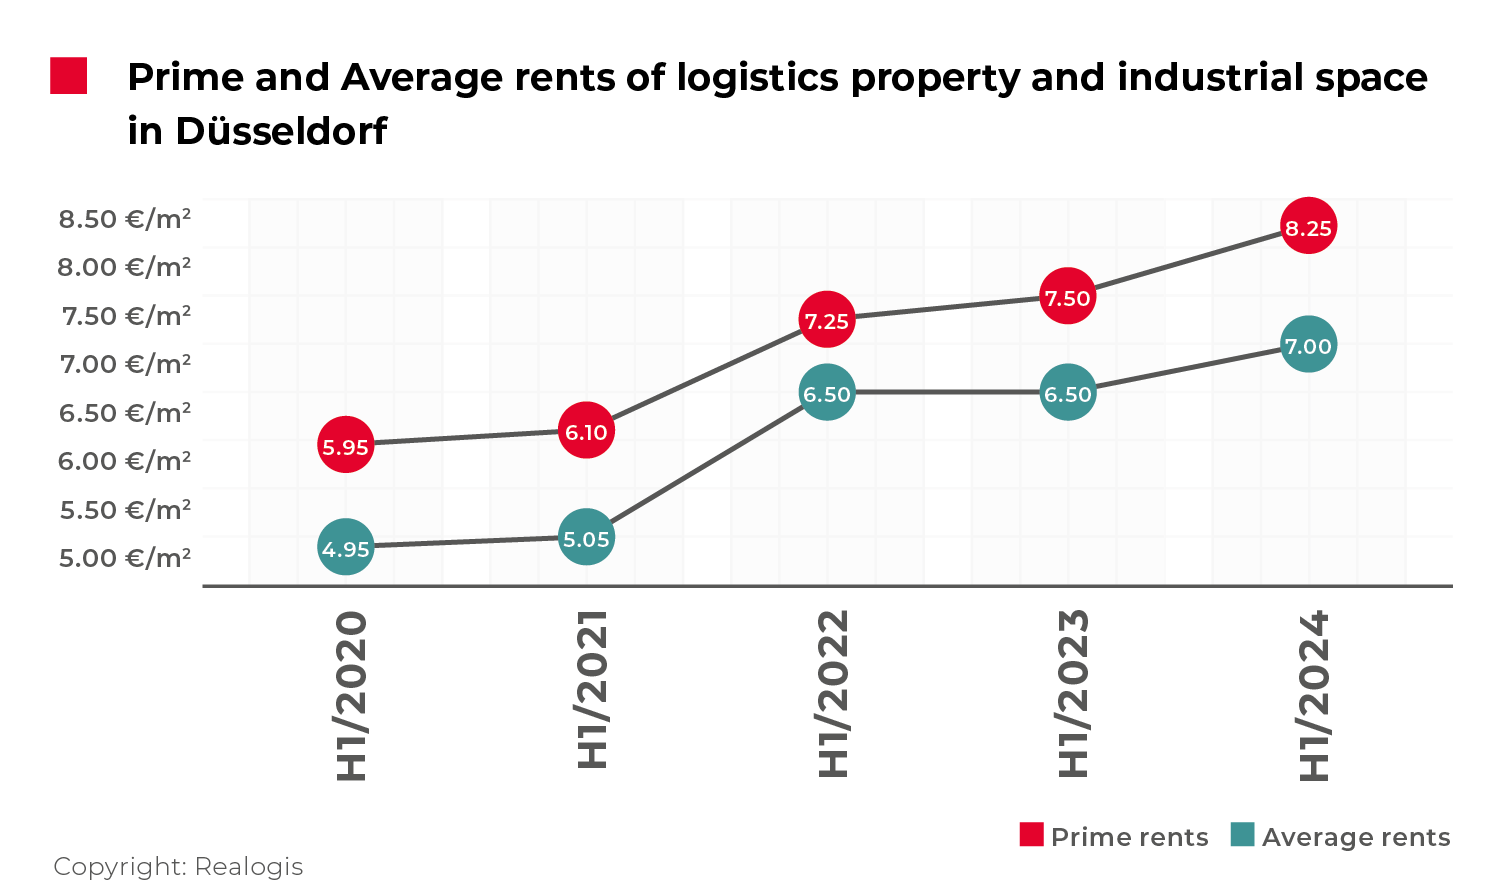
The prime rent for industrial and logistics properties in the Düsseldorf region rose by 10% to €8.25/m² in the first half of 2024. This represents a provisional peak, up from €7.5/m² in the same period of the previous year. After the first half of the previous year, this is the second most significant increase since records began (H1 2022: +18.9% from €6.10/m² to €7.25/m²). The 5-year average currently stands at €7.01/m² and is exceeded by the rent increase by a significant 17.7 %.
The average rent rose to €7.00/m² (+7.7 %), exceeding the 5-year average of €6.00/m² by 16.7 %.
Outlook
"The Düsseldorf industrial and logistics property market is characterised by a shortage in the mid-range space segment of 2,000 to 7,000 m². There is virtually no space available in this size range. Rents have now reached a high level and further developments remain to be seen, although we assume that the peak has slowly been reached," predicts Bülent Alemdag.
Press contact REALOGIS:
SH/Communication - Agency for Public Relations
Silke Westermann
Tel: +49/211/53 88 3-440
E-Mail: s.westermann@shcommunication.de
Company contact REALOGIS:
REALOGIS Holding GmbH
Silja Schuppler
Marketing
Leopoldstraße 154, 80804 München
Tel: +49/89/51 55 69 17
E-Mail: s.schuppler@realogis.de
www.realogis.de
REALOGIS. No. 1 for industrial and logistics properties
The REALOGIS Group is Germany’s leading player for the consulting and brokering of industrial, logistics and commercial properties. Founded in 2005 as a pioneer for the asset class of logistics and industry, the owner-operated group has enjoyed healthy growth, is crisis-resistant and knows the German market like no other. In 2022 Realogis generated nearly 1.25 million m² of usable space alone in the letting segment. The net commission revenue of all services in the financial year 2023 are around EUR 19 million.
In 2021, REALOGIS also won the German Real Estate Prize in the “Commercial Player” category, which honours companies for their outstanding commitment, creativity, innovative strength and sustainability.
Realogis is represented in the country’s seven top logistics locations of Berlin, Düsseldorf, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart, while a dedicated organisational unit ensures transparency in around 15 additional regional logistics markets. 70 real estate professionals advise national and international companies from the fields of logistics, e-commerce, retail and industry as well as private and institutional investors. Quick, flexible, regional, customer-oriented and with a high volume of transactions.
REALOGIS four core competencies are arranging highly creditworthy tenants for new and existing properties, assisting investors with property investments and project development of greenfields and brownfields, outstanding service for locating or selling sites, and the development and implementation of holistic property strategies.
In short, REALOGIS creates more room for its customers’ success in every sense. Further information: https://www.realogis.de/