
Unfortunately, there are no properties on your watch list.
Do you have a question? Leave your contact details here and we will call you back!

Press Release
Berlin region: REALOGIS analyses the market for logistics and industrial properties in the first half of 2025
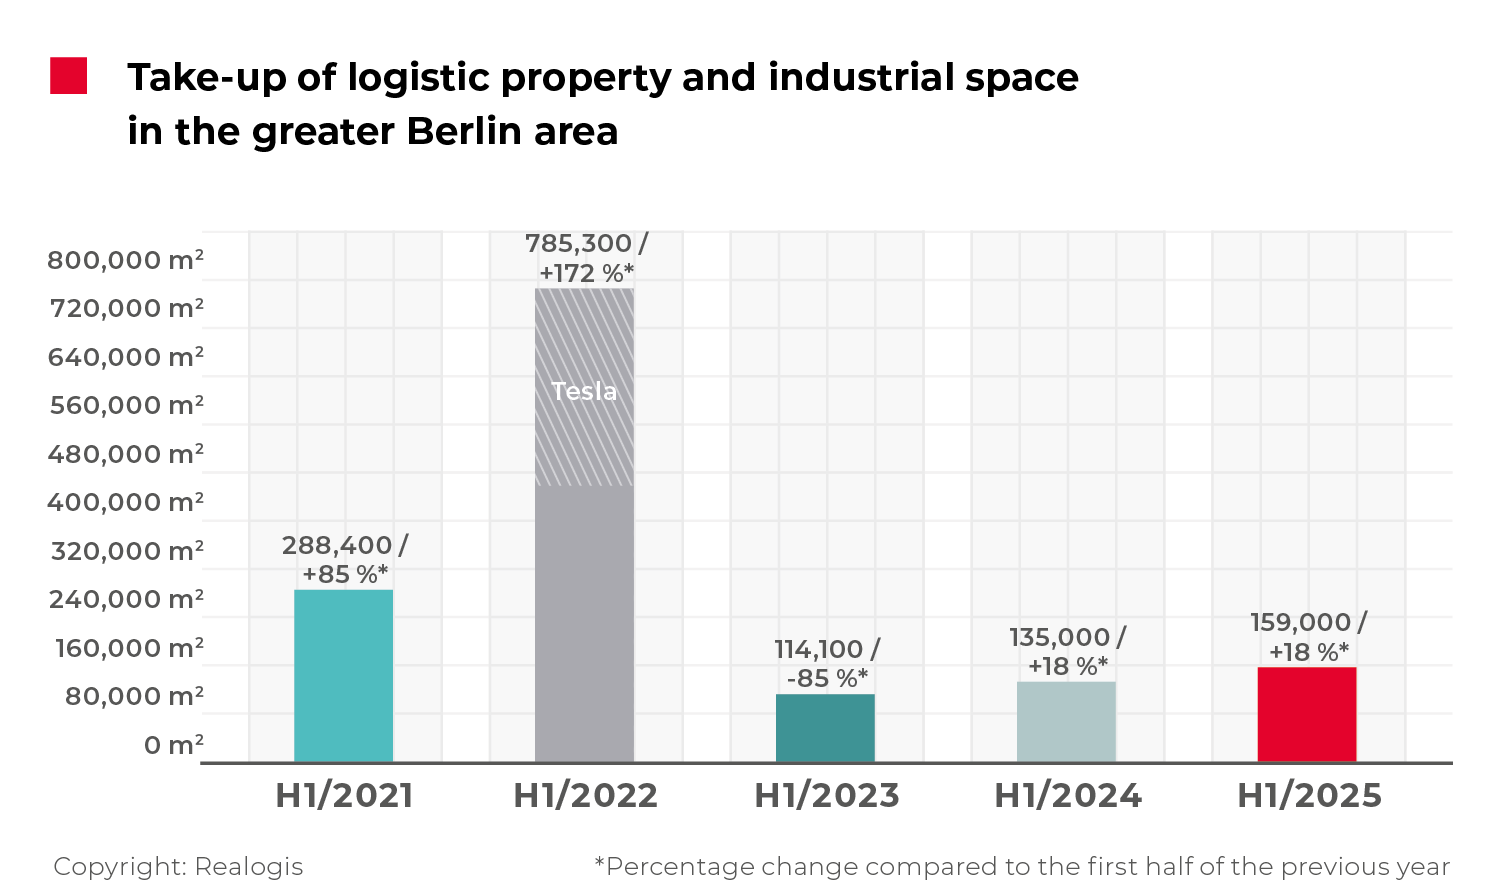
- Berlin market continues previous year's positive trend with take-up of 159,000 m² or an increase of 18 %
- New-built properties on greenfield sites increase by 64 %
- Big box properties dominate total take-up with 117,600 m²
- Western Berlin environs lead regional ranking
- Manufacturing is the strongest sector to take up space
- €10/m² exceeded: prime rent increases by 7% to €10.50/m²
- Outlook: Positive development also expected in the second half of the year
"The positive trend of the same period last year continued in the first six months, partly due to the flexibility of landlords of existing properties as well as further new property developments and the resulting space potential," comments Alexander Ego, Managing Director of Realogis Immobilien Berlin GmbH.
Looking at the last five first half-years, the take-up generated by all market participants in January to June 2025 represents the third-best result, after H1 2021 with 288,400 m² and the record half-year H1 2022 with 785,300 m² (or 458,300 m² without the Tesla deal for 327,000 m²). However, the average take-up of 296,360 m² in the last five first half-years, which is also due to the two outlier years, was missed by 46 %.
At 68,900 m², agreements for new-build properties on greenfield sites accounted for 43 % of the overall result. These include four of the largest contracts: Spedition Stenger (18,000 m²), Siemens Energy (10,460 m²), VAH Jager (10,380 m²) and a logistics service provider (9,970 m²). Compared to the same period of the previous year, new-build properties increased their result by 26,800 m² or 64 % (H1 2024: 42,100 m² or 31 %).
Key contributors to take-up:
Company | Market area | Take-up of space | Type | Industry |
Industrial company | Berlin environs East | 30,000 m² | New building (brownfield) | Manufacturing |
Spedition Stenger | Berlin environs West | 18,000 m² | New building (greenfield) | Logistics/Distribution |
Siemens Energy | Berlin environs West | 10,460 m² | New building (Greenfield) | Manufacturing |
VAH Jager | Berlin environs North | 10,380 m² | New building (Greenfield) | Logistics/Distribution |
Logistics service provider | Berlin environs West | 9,970 m² | New building (Greenfield) | Logistics/Distribution |
Conversely, deals in existing space halved year-on-year to 45,700 m² or 29 % (H1 2024: 92,900 m² or 69 %), partly due to a lack of large lettings.
The brownfield development category ranked just behind with 44,400 m² or 28 %. A major manufacturing company in Berlin's eastern suburbs accounted for 30,000 m², or 68 %, of take-up in this category. No contracts were signed in the same period of the previous year.
"The increase in take-up in new-build properties, both on greenfield and brownfield sites, compensated for the delta that arose in existing properties, resulting in a year-on-year increase of 24,000 m² in total," summarizes Alexander Ego.
While 11,600 m², or 9 %, was accounted for by owner-occupier contracts in the previous year, the market was purely a rental market in the past six months. Coming from 123,400 m² or 91 % in H1 2024, take-up increased by 35,600 m² or 29% in absolute terms.
In terms of building type, rentals in big box properties dominated with 117,600 m² or almost three quarters of total take-up (or 74%). Coming from just 39,600 m² or 30 % in the same period of the previous year, take-up in this category almost tripled compared to the first half of the year (+78,000 m² in absolute terms).
In contrast, take-up in business parks, the number one building type in the previous year, fell by a significant 31,100 m² or 60 % to currently 20,700 m² or 13 % (H1 2024: 51,800 m² or 38 %).
"All city center business park developments have now been fully let, meaning that the only space available in the near future will be in Berlin-Bohnsdorf or in the southern suburbs. However, further project developments will come onto the market again soon in various city locations, which means we expect higher sales figures here too," says Alexander Ego.
Transactions in space that cannot be allocated to business parks or big box space totaled 20,700 m² or 13% and also fell year-on-year (H1 2024: 43,600 m² or 32%).
Berlin's western environs lead the regional ranking
The largest buyer of space in the first half of 2025 was Berlin's western environs, which previously ranked third, accounting for a quarter of total take-up with 39,700 m². The lion's share (38,430 m²) was accounted for by large deals signed by the freight forwarder Stenger (18,000 m²), Siemens Energy (10,460 m²) and an unnamed logistics service provider (9,970 m²). Space take-up in the region more than doubled from 19,700 m² or 15 % in the same period of the previous year.
The southern environs of Berlin remain in second place with 36,200 m² or 23 %, up from 23,200 m² or 17 % (growth of 13,000 m² or +56 % in absolute terms).
In third place is the previously fourth-placed region of Berlin eastern region with 35,900 m² or 23 % (+33,900 m² or +1695 %), which also accounted for the largest take-up in the first half of the year (30,000 m²) by an unnamed major manufacturing company.
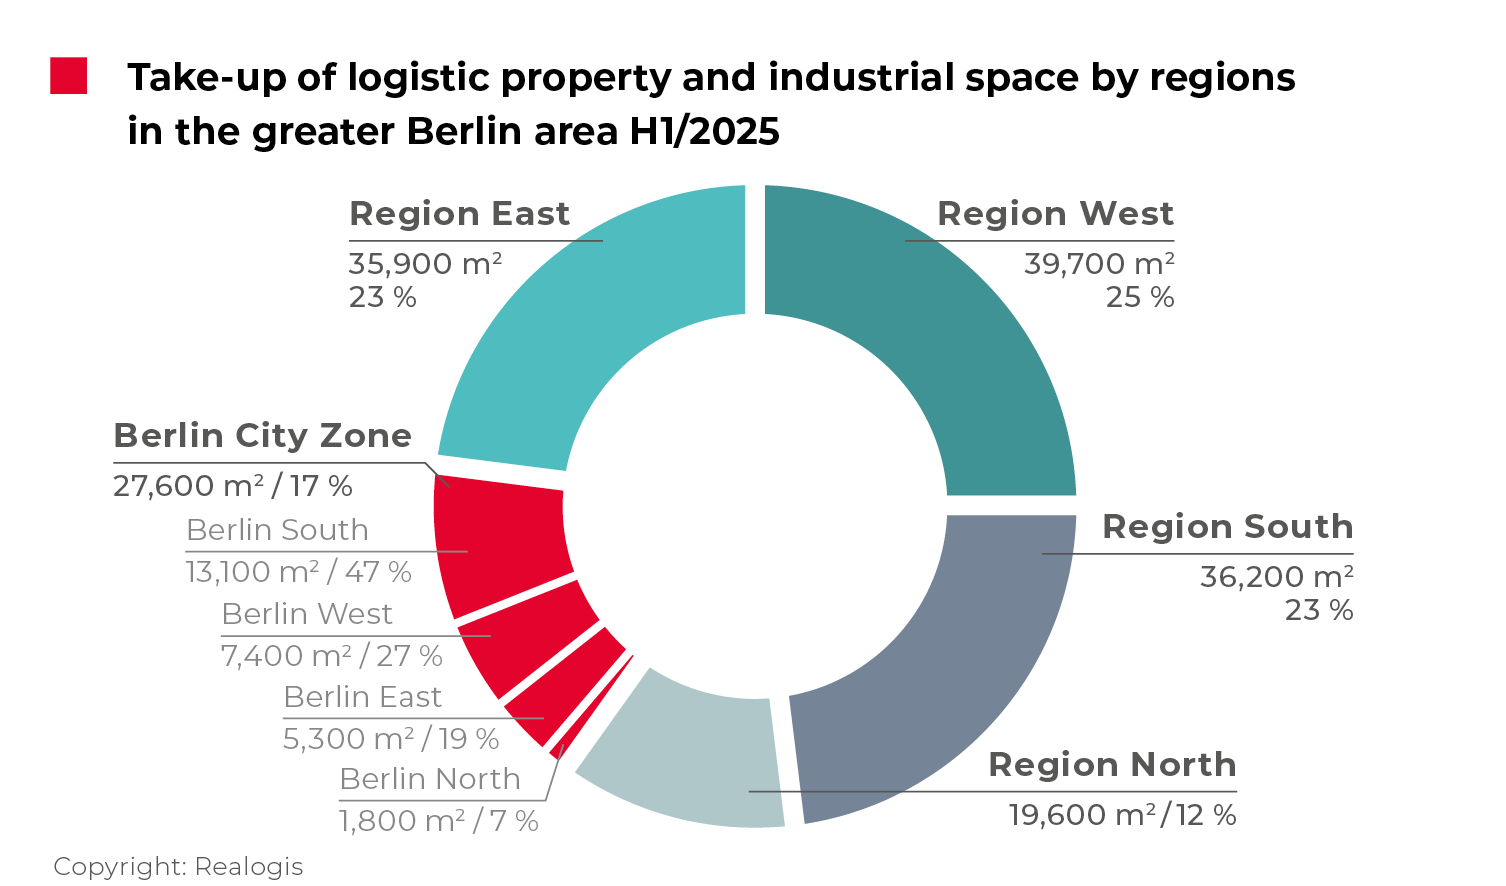
The Berlin city area is in fourth place with 27,600 m² or 17 %. Coming from 90,100 m² or 67 % in H1 2024, the only and above all significant slump in take-up here is 62,500 m², which is equivalent to more than halving (-69 %). Take-up in all five urban areas is well below average and is at least 63 % below the respective average of the last five first half-years.
Within the Berlin city area, the southern city area continued to be the largest buyer of logistics, warehouse and industrial space with 13,100 m² or 47 % (H1 2024: 26,400 m² or 29 %), followed by Berlin West with 7,400 m² or 27 % (H1 2024: 17,800 m² or 20 %) and Berlin East with 5,300 m² or 19 % (H1 2024: 25,700 m² or 29 %). Berlin North, which currently brings up the rear, recorded a decline of 91% and currently has take-up of 1,800 m² (H1 2024: 20,200 m² or 22%).
"This development is due on the one hand to the limited supply of suitable space in the city centre and on the other hand to the current comparatively favorable supply of space in the surrounding area," explains Alexander Ego.
The northern suburbs continue to rank fifth among all regions with 19,600 m² or 12 %. VAH Jager's take-up of 10,380 m² was the key factor here. The average of the last five first half-years was more than doubled (currently at 8,640 m²).
Sector ranking: Manufacturingis the strongest industry in terms of space take-up
The sector ranking in the first half of 2025 shows the Manufacturing industry - third place compared to the previous year - as the winner. Take-up rose to 62,800 m² in the first six months, or a 40% share of the overall market. Coming from 17,500 m² or 13 %, this is the second highest absolute growth of 45,300 m² or a more than threefold increase. The agreements signed by a major industrial client and Siemens Energy contributed a total of 40,460 m² or 64 % of the sector's take-up. Nevertheless, the result is below average, as the 5-year average of 112,48 m² was missed by 44 %.
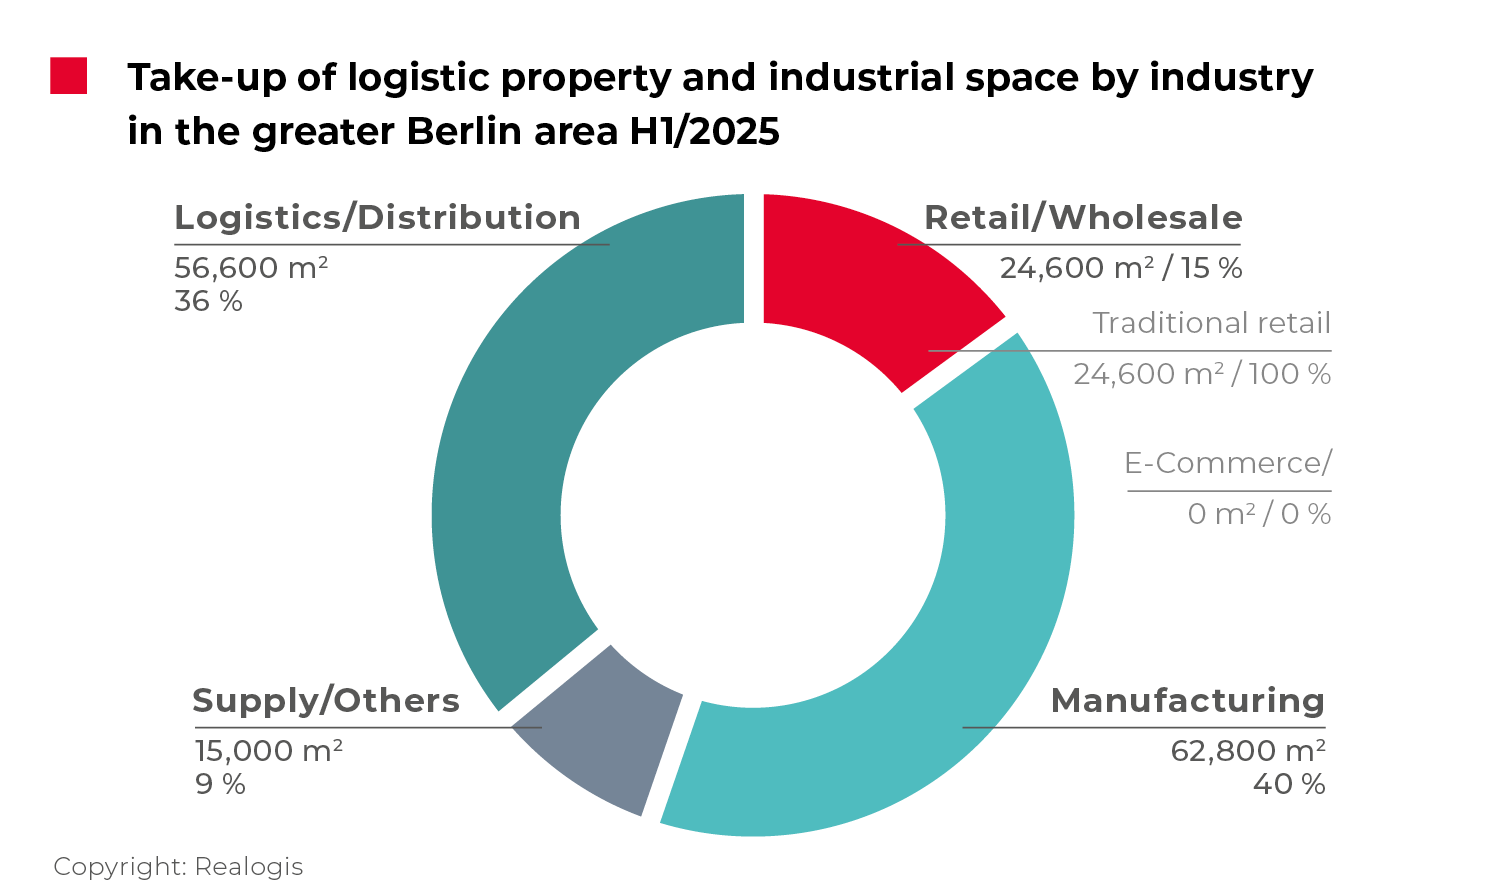
The second largest amount of space, 56,600 m² or 36 %, was rented by companies in the logistics/distribution sector. Coming from 4th place, this is the clearest absolute and percentage increase of all sectors with +46,400 m² or a more than five-fold increase (coming from 10,200 m² or 8 %). The major contracts signed by Spedition Stenger (18,000 m²), VAH Jager (10,380 m²) and an unnamed logistics service provider (9,970 m²) accumulated to 38,350 m² or 68 % of take-up. Despite the significant increase, take-up by logistics/distribution companies is still not quite at the typical level of the last five first half-years: the average figure is 65,140 m² or 13 % less.
The Retail/Wholesale sector, which was previously in first place, slipped to third place with 24,600 m² or 15 %, coming from 75,700 m² or 56 % with the most significant drop of 51,100 m² or more than halving (or -68 %). Furthermore, there were no e-commerce transactions, and the entire take-up was accounted for by transactions with companies in the traditional retail sector. In last place is the previously second-placed collective category "Other" with 15,000 m² or 9 %, down from 31,600 m² or 23 %. With a drop of 72 %, the 5-year average of currently 88,440 m² was the most significantly undercut of all sectors.
Ranking of the size categories: Large spaces back on the winner's podium
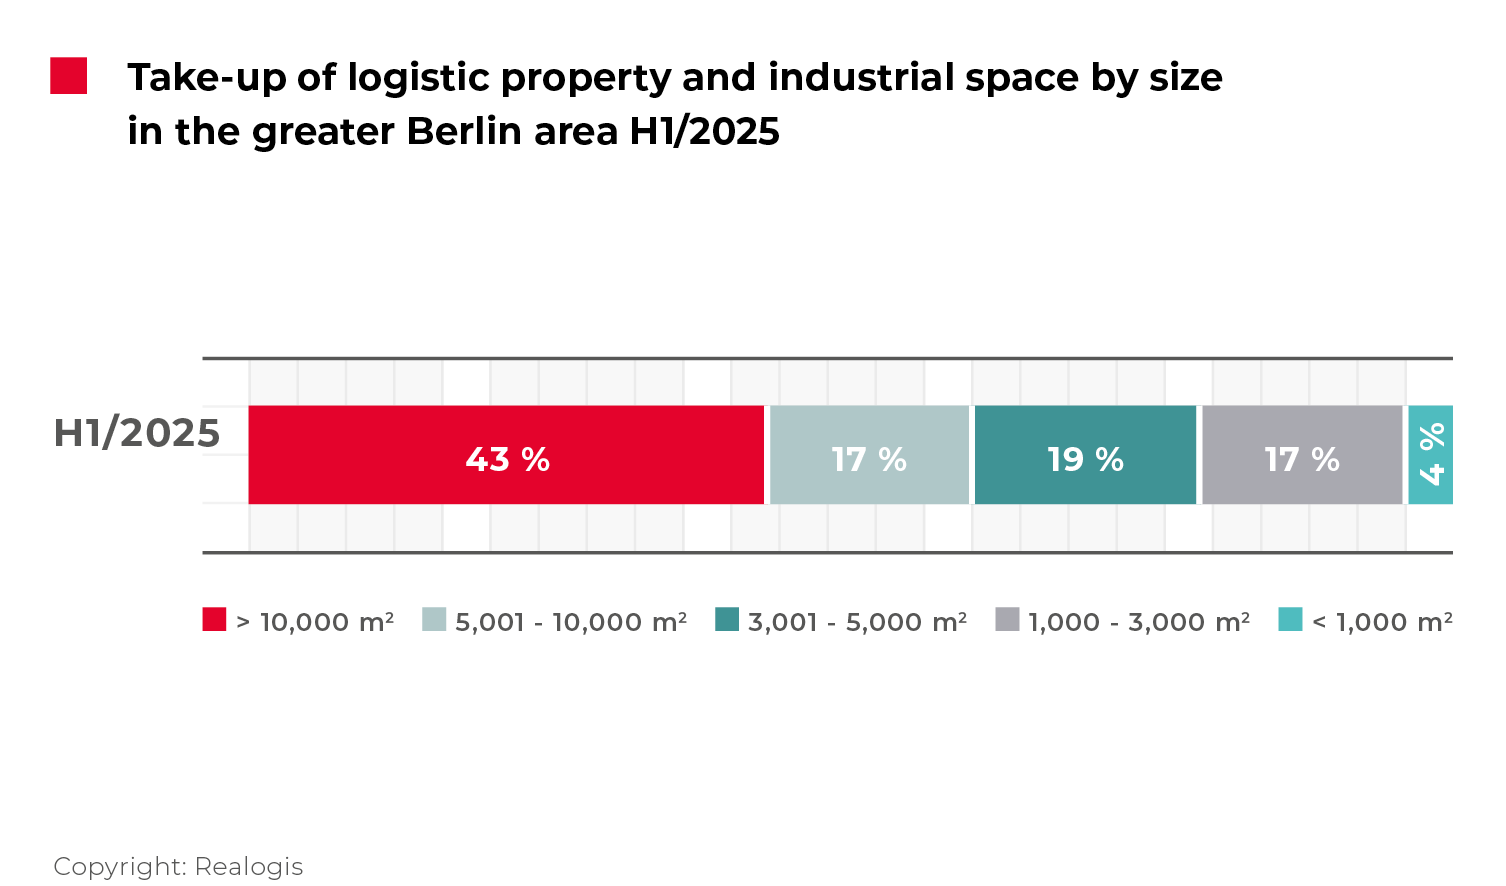
Large spaces of 10,001 m² or more are once again in the lead and have climbed one place to first place. With take-up of 68,840 m² or 43 %, up from 33,400 m² or 25 % in H1 2024, they recorded the most significant growth in take-up of all size categories with an increase of 35,440 m².
The previously second-placed take-up of space in the category between 5,001 and 10,000 m² has fallen the most and is only in fourth place with 26,000 m² or 17 %. Units between 3,001 and 5,000 m² ranked second with 30,560 m² or 19 % (H1 2024: 21,700 m² or 16 %) and recorded growth of 8,860 m² or +41 %. Units between 1,000 and 3,000 m² are in third place with 26,900 m² or 17 % (H1 2024: 29,600 m² or 22 %) and micro units of less than 1,000 m² are still in last place and continue to be the least important for take-up in the market with 6,700 m² or 4 % (H1 2024: 10,000 m² or 7 %).
With the exception of the size category of medium-sized to large spaces between 3,001 and 5,000 m², all others fall short of their respective average (of the last 5 first half-years) by at least 30 %. Only the 3,001 and 5,000 m² category achieved an above-average result.
€10/m² exceeded: prime rent increases by 7 % to €10.50/m²
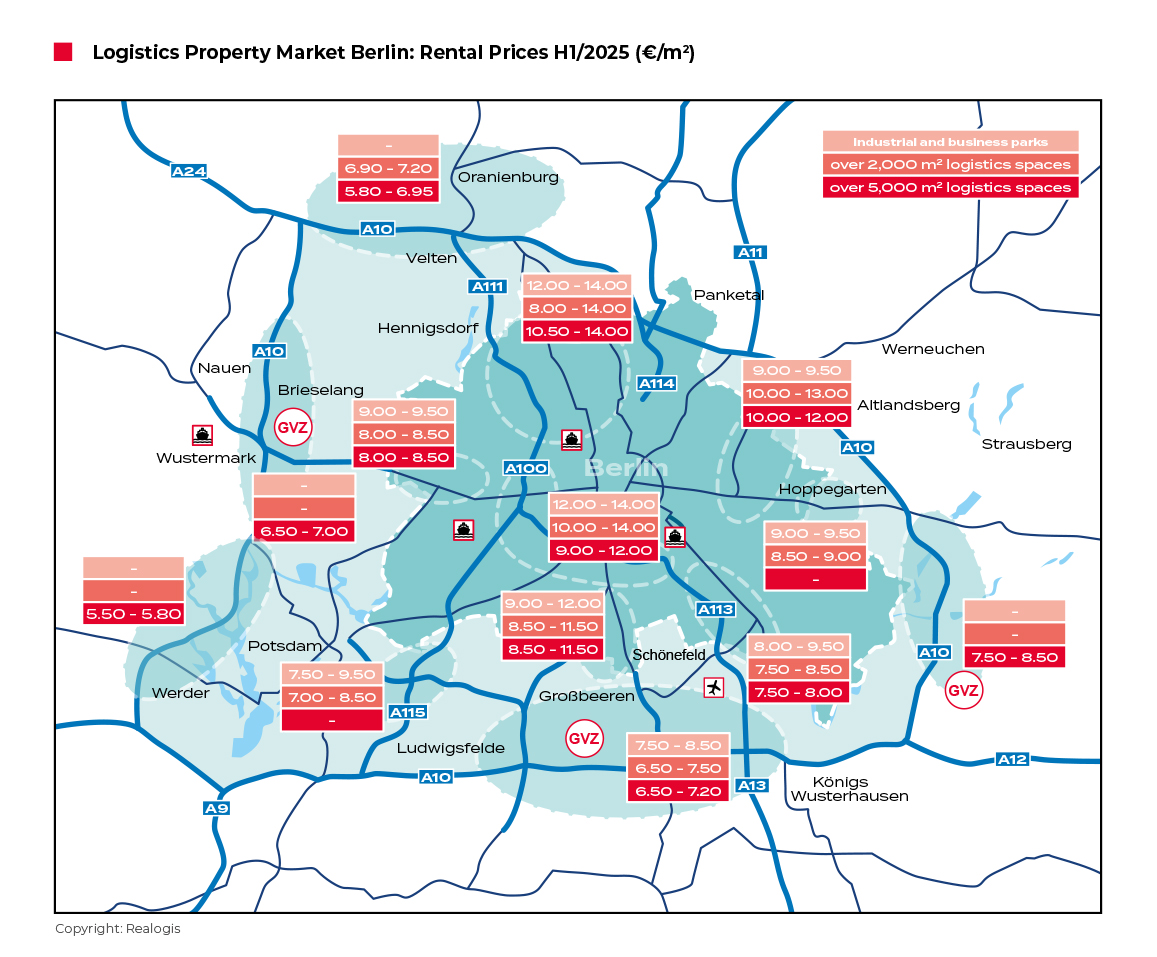
The prime rent for logistics, warehouse and industrial properties in the Berlin region increased by 7 % year-on-year from €9.85/m² to €10.50/m². Compared to the first quarter of 2025, however, this represents a sideways movement.
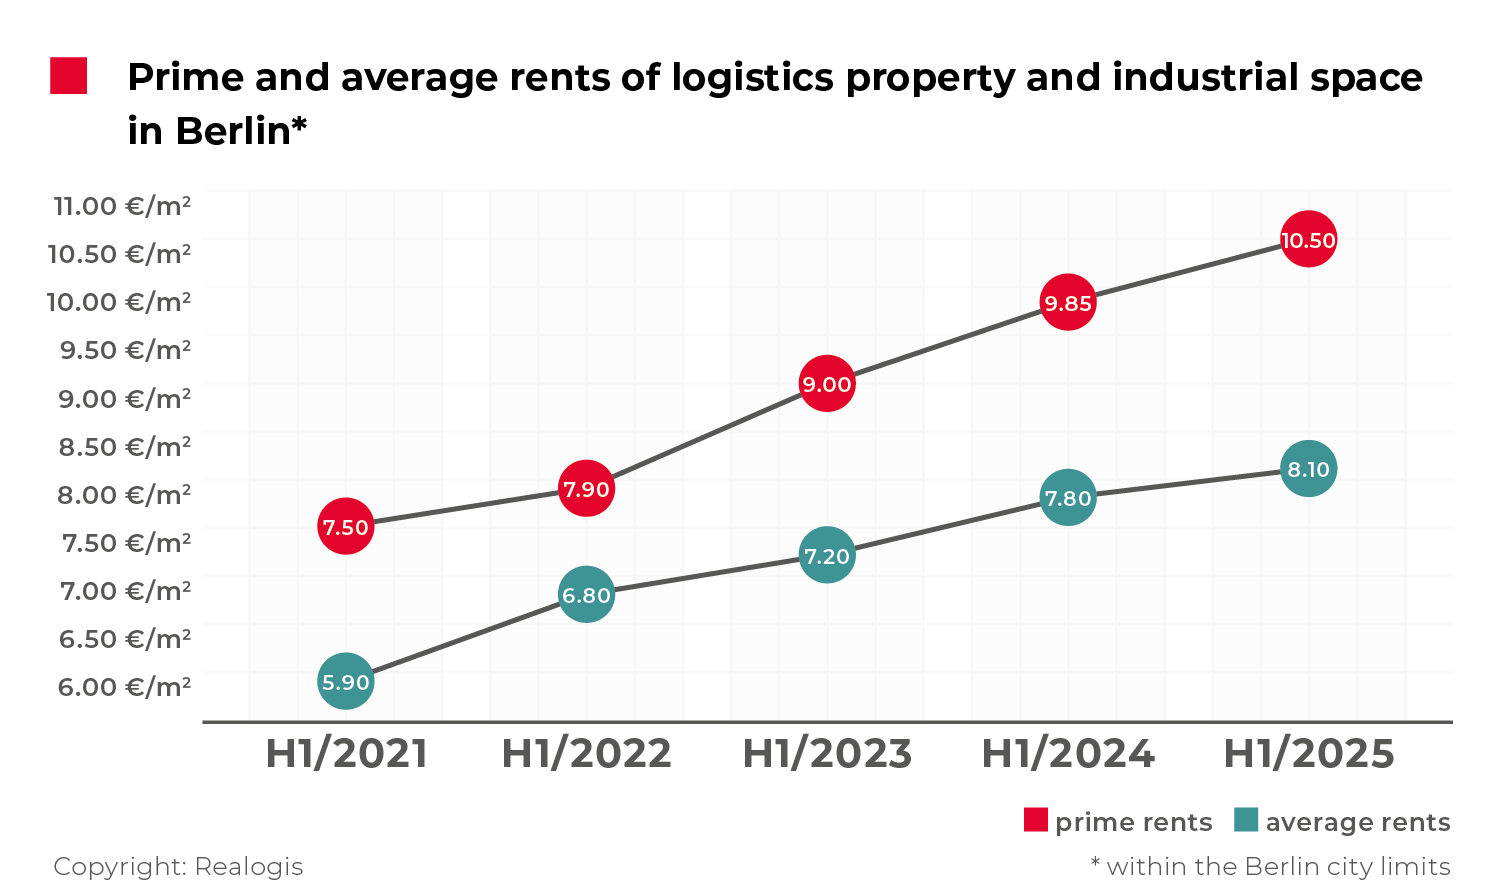
"Rents have levelled off at a high but still sustainably achievable level," comments Alexander Ego. The current prime rent is 17 % above the 5-year average of EUR 8.95/m².
The average rent is also developing dynamically, albeit more cautiously, with an increase of 4 % to €8.10/m², up from €7.80/m². It also represents the same price level as Q1 2025, i.e. the rent did not change in the first six months. The 5-year average of currently € 7.16/m² is exceeded by 13 %.
Outlook
"Our impression that the market is regaining momentum is increasingly confirmed by the current market figures. The increased activity is clearly reflected in the latest developments. We are assuming that this trend will continue in the second half of the year and that we will exceed the previous year's total of just under 300,000 m²," expects Alexander Ego.
Press contact REALOGIS:
SH/Communication - Agency for Public Relations
Silke Westermann
Tel: +49/211/53 88 3-440
E-mail: s.westermann@shcommunication.de
Company contact REALOGIS:
REALOGIS Holding GmbH
Silja Schuppler
Marketing Manager
Leopoldstraße 154, 80804 Munich
Phone: +49/89/51 55 69 17
E-mail: s.schuppler@realogis.de
www.realogis.de
REALOGIS. The No. 1 for industrial and logistics properties
The REALOGIS Group is Germany's leading address for consulting and brokerage services for industrial and logistics properties and commercial land and has a 20-year track record of success. Founded in 2005, the owner-managed, organically grown and crisis-proof group of companies knows the German market like no other.
In the 2023 financial year, Realogis' audited net commission income across all services totalled around 15.76 million euros. In the lettings segment alone, the group achieved take-up of 982,232 m² in 2023, which corresponds to 16.5% of the total take-up of all market participants in Germany in that year and also represents a doubling of Realogis' market share since 2016.
Around 70 property professionals provide advice and support to national and international companies from the logistics, e-commerce, retail and industrial sectors as well as private and institutional investors. Fast, flexible, regional and customer orientated. The group has eight branches in Berlin, Düsseldorf, Germany South/North, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart.
Its four core competences include finding tenants with strong credit ratings for existing and new-build properties, supporting investors in property investments and in the development of greenfield and brownfield projects, providing a perfect service for property searches and sales and developing and implementing holistic property strategies. This covers the entire property cycle - from location analysis and optimisation of expansion targets to the sale of assets that are no longer required for operations.
In short: REALOGIS offers "More space for your success" in every respect.